Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Aviation Cloud Market: Size, CAGR & 2035 Outlook
Aviation Cloud Market
Aviation Cloud Market: Size, CAGR & 2035 Outlook
Aviation Cloud Market by Deployment Model (Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud), by Service Model (IaaS, PaaS, SaaS, FaaS), by Application (Flight Operations, Passenger Services, Predictive Maintenance, Baggage & Cargo, BI & Analytics, Supply Chain), by End User (Airlines, Airports, MRO Providers, ANSPs, OEMs, Regulators), by Enterprise Type (Large Enterprises, SMEs), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Netherlands, Spain), by Asia Pacific (China, Japan, India, South Korea, Singapore), by Middle East & Africa (Saudi Arabia, UAE, Qatar, South Africa), by Latin America (Brazil, Mexico, Argentina, Chile) Forecast 2026-2034
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 272
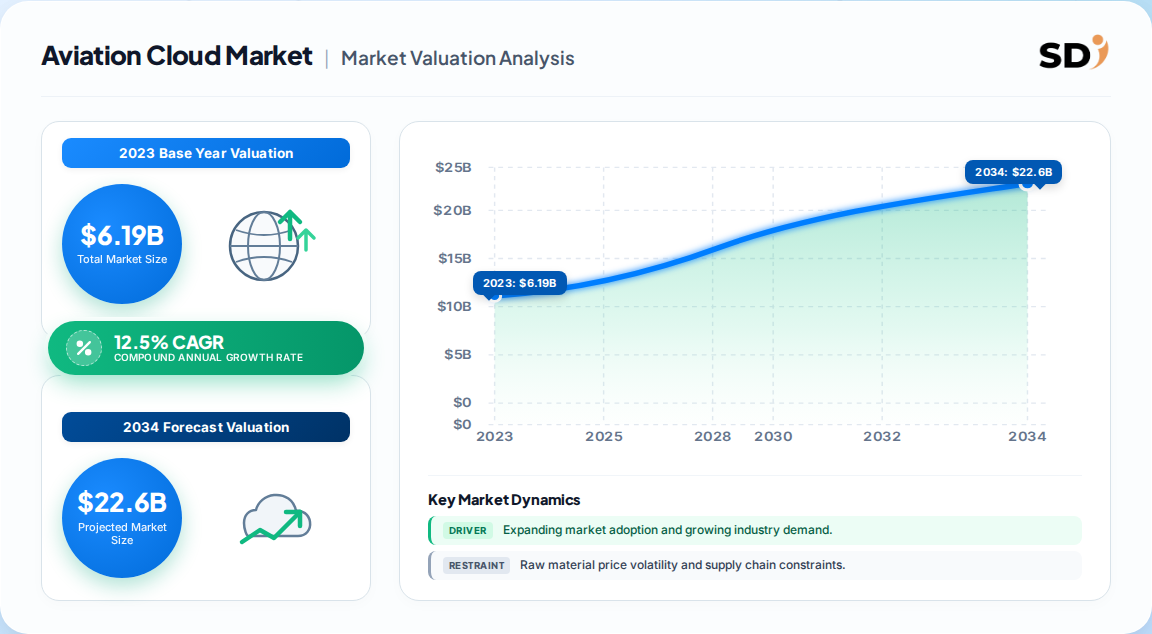
The global aviation cloud market was valued at USD 6.19 billion in 2023 and is projected to reach USD 13.64 billion by 2030, a 12.5% CAGR (secondary benchmark estimate).
A competing analysis puts 2031 at USD 15.72 billion from an 8.13 billion 2026 base at 14.08%, implying faster near-term acceleration — the divergence itself is a signal.
Public cloud leads deployment (~44–48% share), yet hybrid cloud is the fastest-growing model at a projected ~16.9% CAGR to 2031.
SaaS commands the largest service-model share (41.5–75.6% depending on definition), while IaaS grows fastest (~16.9%) on elastic workload demand.
North America holds ~36% revenue share; Asia-Pacific is the fastest-growing region at ~15.1% CAGR driven by tier-2 airport digitization.
Leading vendors include AWS, Microsoft, Google, IBM, SITA, Amadeus, SAP, Oracle and Lufthansa Systems.
Why this matters for decision-makers: The binding constraint is no longer compute cost but data-residency compliance — carriers must architect multi-region replication budgets 15–25% above single-region baselines, which will reprice vendor contract structures through 2030.
Aviation Cloud Market Size (In Billion)
15.0B
10.0B
5.0B
0
6.190 B
2023
6.960 B
2024
7.830 B
2025
8.810 B
2026
9.910 B
2027
11.15 B
2028
12.54 B
2029
Aviation Cloud Market Size (In Billion)
Year
Market Size
2023
6.190 B
2024
6.960 B
2025
7.830 B
2026
8.810 B
2027
9.910 B
2028
11.15 B
2029
12.54 B
What is the Aviation Cloud Market?
The aviation cloud market covers cloud-hosted infrastructure, platforms and software that airlines, airports, MROs and OEMs use for flight operations, passenger services, predictive maintenance, cargo and analytics. It replaces on-premise airline IT with elastic, multi-tenant capacity enabling real-time data processing, AI-driven decisioning and regulatory-grade security.
Scope: what this report covers and excludes
This analysis covers global cloud deployment (public, private, hybrid, community), service models (IaaS, PaaS, SaaS, FaaS), applications (flight operations, passenger services, maintenance, baggage and cargo, BI/analytics, supply chain) and end users (airlines, airports, MROs, ANSPs, OEMs, regulators). This analysis does not cover on-premise aviation IT hardware, standalone airline ERP licenses, or aerospace manufacturing execution systems outside cloud delivery.
How big is the market for Aviation Cloud Market?
Estimates converge on a double-digit-growth market roughly doubling between 2023 and 2030, but published figures diverge by base year and service-model definition. The table below isolates where they differ.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
USD 6.19 Billion
2023
2030
12.5%
Cloud services across airlines/airports/MROs
One published estimate
USD 8.13 Billion
2026
2031
14.08%
Deployment + service model + end user
A competing analysis
USD 7.49 Billion
2025
2035
15.17%
Enterprise-segmented, incl. SMEs
A third-party forecast
Our analysis suggests the 12.5% figure is the most defensible near-term baseline because it aligns with SITA-reported airline IT spend of USD 50.8 billion in 2025, of which cloud migration is the fastest-growing category. The higher 15%+ CAGRs likely reflect narrower SaaS-heavy definitions rather than broader infrastructure scope.
How is the market segmented?
Segmentation spans four non-geographic axes: deployment model, service model, application and end user. Deployment choice increasingly tracks compliance posture rather than cost alone.
Parent
Children
Deployment Model
Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud
North America leads with roughly 36% revenue share, but Asia-Pacific is the fastest-growing region at approximately 15.1% CAGR through 2031, with Europe close behind on sovereign-cloud mandates.
Aviation Cloud Market Regional Market Share
Loading chart...
Aviation Cloud Market Regional Market Share
Region
Market Share (%)
North America
0.36%
Europe
0.24%
Asia-Pacific
0.26%
Middle East & Africa
0.08%
Latin America
0.06%
North America — USA, Canada, Mexico
Europe — Germany, UK, France, Italy, Netherlands, Spain
Asia Pacific — China, Japan, India, South Korea, Singapore
Middle East & Africa — Saudi Arabia, UAE, Qatar, South Africa
Latin America — Brazil, Mexico, Argentina, Chile
The regional split reflects a second-order effect: hyperscalers localize edge compute in tier-2 airports to win APAC public-sector tenders, effectively subsidizing infrastructure that also serves commercial carriers. Europe's share is capped by data-residency replication costs.
What is driving growth — and what is holding it back?
Growth is driven by digital-transformation budget reallocation, real-time flight analytics and cost optimization against legacy IT; it is restrained by cyber-sovereignty costs and aviation-grade DevSecOps skill shortages.
Factor
Direction
Evidence strength
Mechanism
Airline digital-transformation budgets
Driver (+3.20% CAGR impact)
High
Capital shifted from aircraft programs to cloud platforms
Real-time flight-data analytics
Driver (+2.80%)
High
Event-driven telemetry enables fuel and maintenance savings
Cloud cost optimization over legacy IT
Driver (+2.40%)
Medium-High
Double-digit savings vs. leased data centers
Hyperscaler IaaS into tier-2 airports
Driver (+1.90%)
Medium
Sub-50ms edge latency for biometrics and baggage
Data-residency compliance costs
Restraint (−1.40%)
High
Multi-jurisdiction replication lifts capex 15–25%
Aviation DevSecOps skill shortage
Restraint (−1.10%)
Medium-High
Slows secure migration timelines
The balance favors growth, but the restraint side is structural, not cyclical. Compliance cost is a permanent tax on architecture, which means margin accrues to vendors offering certified sovereign-cloud blueprints rather than raw capacity.
Who are the leading vendors?
Competition splits into hyperscalers with aviation compliance certifications, aviation-specialist software houses, and systems integrators bridging regulatory gaps.
Vendor type
Examples
Differentiator
Moat / risk
Hyperscalers
AWS, Microsoft, Google, IBM
Scale, certified regions, AI tooling
Deep but exposed to sovereignty rules
Aviation software
SITA, Amadeus, Lufthansa Systems, Veryon
Domain workflows, airline trust
Legacy migration debt
Enterprise/ERP
SAP, Oracle, Salesforce, Infor
Back-office integration
Undercut by serverless microservices
Integrators
Accenture, DXC, Wipro, Collins Aerospace
Compliance implementation
Margin pressure from hyperscaler self-service
Our analysis suggests the durable moat is aviation-specific compliance certification, not compute economics — hyperscalers race to certify, while niche vendors use serverless microservices to undercut ERP incumbents.
What do buyers and operators need to know?
Selection hinges on compliance architecture first, workload fit second, price third. Carriers must model data-egress and cross-region transfer costs explicitly, since unchecked fees can erase projected hybrid savings. Switching costs are high once flight-operations and maintenance data pipelines are embedded, so exit provisions and data-portability clauses deserve as much scrutiny as SLAs. Regulatory alignment — EU passenger-name-record localization, national sovereign-cloud mandates in the Gulf, and biometric frameworks like India's Digi Yatra — should be validated per jurisdiction before contract signature. Buyers should also demand aviation-grade DevSecOps staffing commitments, given documented skill shortages that slow secure migration. Finally, insist on auditability of AI/ML models used in predictive maintenance, where safety-case evidence is non-negotiable.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a hybrid-first architecture as the default procurement posture through 2030, with public cloud reserved for elastic analytics and passenger-facing workloads. The strongest counter-argument is that public cloud's cost efficiency (44–48% share, capex-to-opex conversion) will simply overwhelm compliance friction as sovereign-cloud frameworks mature; if EU and Gulf regulators converge on mutual recognition, private-cloud premiums could compress sharply.
However, that convergence is unlikely before 2028. In the interim, the competitive battle shifts to certified sovereign blueprints and aviation-grade DevSecOps talent — the two scarcest inputs. Vendors that bundle compliance certification with managed security will capture disproportionate share of airline IT budgets, while pure-capacity providers face margin compression.
Airlines and airports: negotiate multi-region exit clauses and pre-validate egress costs before committing to hybrid baselines.
Vendors: prioritize aviation-specific compliance certifications and MRO-focused analytics to capture the fastest-growing end-user segment (~15.4% CAGR).
Investors: weight exposure toward PaaS/IaaS growth vectors and APAC tier-2 airport edge deployments rather than mature SaaS seat models.
Evidence that would change this conclusion: binding multilateral mutual recognition of aviation data-residency rules, or a step-change in sovereign-cloud pricing that eliminates the 15–25% hybrid premium.
Aviation Cloud Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Aviation Cloud Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 12.5% from 2020-2034
Segmentation
By Deployment Model
Public Cloud
Private Cloud
Hybrid Cloud
Community Cloud
By Service Model
IaaS
PaaS
SaaS
FaaS
By Application
Flight Operations
Passenger Services
Predictive Maintenance
Baggage & Cargo
BI & Analytics
Supply Chain
By End User
Airlines
Airports
MRO Providers
ANSPs
OEMs
Regulators
By Enterprise Type
Large Enterprises
SMEs
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Netherlands
Spain
Asia Pacific
China
Japan
India
South Korea
Singapore
Middle East & Africa
Saudi Arabia
UAE
Qatar
South Africa
Latin America
Brazil
Mexico
Argentina
Chile
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Deployment Model
5.1.1. Public Cloud
5.1.2. Private Cloud
5.1.3. Hybrid Cloud
5.1.4. Community Cloud
5.2. Market Analysis, Insights and Forecast - by Service Model
5.2.1. IaaS
5.2.2. PaaS
5.2.3. SaaS
5.2.4. FaaS
5.3. Market Analysis, Insights and Forecast - by Application
5.3.1. Flight Operations
5.3.2. Passenger Services
5.3.3. Predictive Maintenance
5.3.4. Baggage & Cargo
5.3.5. BI & Analytics
5.3.6. Supply Chain
5.4. Market Analysis, Insights and Forecast - by End User
5.4.1. Airlines
5.4.2. Airports
5.4.3. MRO Providers
5.4.4. ANSPs
5.4.5. OEMs
5.4.6. Regulators
5.5. Market Analysis, Insights and Forecast - by Enterprise Type
5.5.1. Large Enterprises
5.5.2. SMEs
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. Middle East & Africa
5.6.5. Latin America
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Deployment Model
6.1.1. Public Cloud
6.1.2. Private Cloud
6.1.3. Hybrid Cloud
6.1.4. Community Cloud
6.2. Market Analysis, Insights and Forecast - by Service Model
6.2.1. IaaS
6.2.2. PaaS
6.2.3. SaaS
6.2.4. FaaS
6.3. Market Analysis, Insights and Forecast - by Application
6.3.1. Flight Operations
6.3.2. Passenger Services
6.3.3. Predictive Maintenance
6.3.4. Baggage & Cargo
6.3.5. BI & Analytics
6.3.6. Supply Chain
6.4. Market Analysis, Insights and Forecast - by End User
6.4.1. Airlines
6.4.2. Airports
6.4.3. MRO Providers
6.4.4. ANSPs
6.4.5. OEMs
6.4.6. Regulators
6.5. Market Analysis, Insights and Forecast - by Enterprise Type
6.5.1. Large Enterprises
6.5.2. SMEs
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Deployment Model
7.1.1. Public Cloud
7.1.2. Private Cloud
7.1.3. Hybrid Cloud
7.1.4. Community Cloud
7.2. Market Analysis, Insights and Forecast - by Service Model
7.2.1. IaaS
7.2.2. PaaS
7.2.3. SaaS
7.2.4. FaaS
7.3. Market Analysis, Insights and Forecast - by Application
7.3.1. Flight Operations
7.3.2. Passenger Services
7.3.3. Predictive Maintenance
7.3.4. Baggage & Cargo
7.3.5. BI & Analytics
7.3.6. Supply Chain
7.4. Market Analysis, Insights and Forecast - by End User
7.4.1. Airlines
7.4.2. Airports
7.4.3. MRO Providers
7.4.4. ANSPs
7.4.5. OEMs
7.4.6. Regulators
7.5. Market Analysis, Insights and Forecast - by Enterprise Type
7.5.1. Large Enterprises
7.5.2. SMEs
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Deployment Model
8.1.1. Public Cloud
8.1.2. Private Cloud
8.1.3. Hybrid Cloud
8.1.4. Community Cloud
8.2. Market Analysis, Insights and Forecast - by Service Model
8.2.1. IaaS
8.2.2. PaaS
8.2.3. SaaS
8.2.4. FaaS
8.3. Market Analysis, Insights and Forecast - by Application
8.3.1. Flight Operations
8.3.2. Passenger Services
8.3.3. Predictive Maintenance
8.3.4. Baggage & Cargo
8.3.5. BI & Analytics
8.3.6. Supply Chain
8.4. Market Analysis, Insights and Forecast - by End User
8.4.1. Airlines
8.4.2. Airports
8.4.3. MRO Providers
8.4.4. ANSPs
8.4.5. OEMs
8.4.6. Regulators
8.5. Market Analysis, Insights and Forecast - by Enterprise Type
8.5.1. Large Enterprises
8.5.2. SMEs
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Deployment Model
9.1.1. Public Cloud
9.1.2. Private Cloud
9.1.3. Hybrid Cloud
9.1.4. Community Cloud
9.2. Market Analysis, Insights and Forecast - by Service Model
9.2.1. IaaS
9.2.2. PaaS
9.2.3. SaaS
9.2.4. FaaS
9.3. Market Analysis, Insights and Forecast - by Application
9.3.1. Flight Operations
9.3.2. Passenger Services
9.3.3. Predictive Maintenance
9.3.4. Baggage & Cargo
9.3.5. BI & Analytics
9.3.6. Supply Chain
9.4. Market Analysis, Insights and Forecast - by End User
9.4.1. Airlines
9.4.2. Airports
9.4.3. MRO Providers
9.4.4. ANSPs
9.4.5. OEMs
9.4.6. Regulators
9.5. Market Analysis, Insights and Forecast - by Enterprise Type
9.5.1. Large Enterprises
9.5.2. SMEs
10. Latin America Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Deployment Model
10.1.1. Public Cloud
10.1.2. Private Cloud
10.1.3. Hybrid Cloud
10.1.4. Community Cloud
10.2. Market Analysis, Insights and Forecast - by Service Model
10.2.1. IaaS
10.2.2. PaaS
10.2.3. SaaS
10.2.4. FaaS
10.3. Market Analysis, Insights and Forecast - by Application
10.3.1. Flight Operations
10.3.2. Passenger Services
10.3.3. Predictive Maintenance
10.3.4. Baggage & Cargo
10.3.5. BI & Analytics
10.3.6. Supply Chain
10.4. Market Analysis, Insights and Forecast - by End User
10.4.1. Airlines
10.4.2. Airports
10.4.3. MRO Providers
10.4.4. ANSPs
10.4.5. OEMs
10.4.6. Regulators
10.5. Market Analysis, Insights and Forecast - by Enterprise Type
10.5.1. Large Enterprises
10.5.2. SMEs
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Aviation Cloud Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Aviation Cloud Market Revenue (Billion), by Deployment Model 2026 & 2034
Figure 3: North America Aviation Cloud Market Revenue Share (%), by Deployment Model 2026 & 2034
Figure 4: North America Aviation Cloud Market Revenue (Billion), by Service Model 2026 & 2034
Figure 5: North America Aviation Cloud Market Revenue Share (%), by Service Model 2026 & 2034
Figure 6: North America Aviation Cloud Market Revenue (Billion), by Application 2026 & 2034
Figure 7: North America Aviation Cloud Market Revenue Share (%), by Application 2026 & 2034
Figure 8: North America Aviation Cloud Market Revenue (Billion), by End User 2026 & 2034
Figure 9: North America Aviation Cloud Market Revenue Share (%), by End User 2026 & 2034
Figure 10: North America Aviation Cloud Market Revenue (Billion), by Enterprise Type 2026 & 2034
Figure 11: North America Aviation Cloud Market Revenue Share (%), by Enterprise Type 2026 & 2034
Figure 12: North America Aviation Cloud Market Revenue (Billion), by Country 2026 & 2034
Figure 13: North America Aviation Cloud Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Aviation Cloud Market Revenue (Billion), by Deployment Model 2026 & 2034
Figure 15: Europe Aviation Cloud Market Revenue Share (%), by Deployment Model 2026 & 2034
Figure 16: Europe Aviation Cloud Market Revenue (Billion), by Service Model 2026 & 2034
List of Tables
Table 1: Aviation Cloud Market Revenue Billion Forecast, by Deployment Model 2020 & 2034
Table 2: Aviation Cloud Market Revenue Billion Forecast, by Service Model 2020 & 2034
Table 16: Europe Aviation Cloud Market Revenue Billion Forecast, by Deployment Model 2020 & 2034
Frequently Asked Questions
1. How fast is the aviation cloud market growing?
Published CAGRs cluster between 12.5% and 15.2% through 2030–2035. The most defensible near-term consensus sits near 12.5–14%, depending on whether infrastructure or SaaS-weighted scope is applied.
2. Which segment leads the aviation cloud market?
Public cloud leads deployment at roughly 44–48% share, and SaaS leads service model. Hybrid cloud and IaaS are the fastest-growing models as carriers balance cost elasticity against data-residency compliance.
3. Who are the leading aviation cloud vendors?
AWS, Microsoft, Google, IBM and SITA lead, alongside Amadeus, SAP, Oracle, Lufthansa Systems, and integrators such as Accenture, DXC and Wipro.
4. Which region grows fastest in aviation cloud?
Asia-Pacific posts the fastest CAGR at approximately 15.1% through 2031, while North America retains the largest revenue share at roughly 36% of the global total.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the aviation cloud value chain with hyperscale cloud infrastructure providers, aviation software and SaaS vendors, systems integrators, airport IT operators, and airline digital-transformation teams. Decision-maker designations interviewed included Chief Information Officers, Heads of Airline IT Infrastructure, Airport Technology Directors, and Procurement and Vendor Management Leads. Interviews probed deployment economics, compliance architecture and migration timelines.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
CIOs & IT Infrastructure Heads
40%
Procurement & Vendor Leads
30%
Airport Technology Directors
30%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Hyperscale Cloud Providers
40%
Aviation Software & SaaS Vendors
30%
Airports & ANSPs
18%
Systems Integrators
12%
Secondary Benchmarking & Public Trade Validation
Secondary validation drew on official multilateral and standards sources: UN Comtrade and WTO trade statistics, Eurostat digital-economy indicators, US SEC 10-K corporate filings and annual investor presentations from listed aviation-IT and cloud vendors, patent databases for cloud-aviation filings, and recognized technical standards bodies including ICAO, IATA, EUROCONTROL and RTCA. No competitor market-research publications were used as validation inputs.
Demand Modeling & Market Sizing Triangulation
Market sizing triangulates simultaneously from the top down (macro airline and airport IT budget allocation, segment share) and the bottom up (hyperscaler aviation-region capacity, subscription pricing, and end-user consumption modeling). Divergences between the two approaches were reconciled against the base-year anchor of USD 6.19 Billion.
 Aviation Cloud Market