Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
Retail Banking Market by Product (Loans, Transactional Accounts, Debit and Credit Cards, Personal Loans, Home Loans, Mortgages, Certificates of Deposits), by Channel (Online Banking, Offline Banking), by Customer Age Group (18-28 Years, 29-44 Years, 45-59 Years, 60+ Years), by Bank Type (National Banks, Private Sector Banks, Neobanks & Others, Public Sector Banks, Foreign Banks, Community Development Banks, NBFC), by Function (Bank Account Opening, Deposits and Withdrawals, Debit and Credit Card Issuance, Investment and Insurance), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy), by Asia-Pacific (China, Japan, India, South Korea, Australia), by Latin America (Brazil), by Middle East & Africa (KSA, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 241
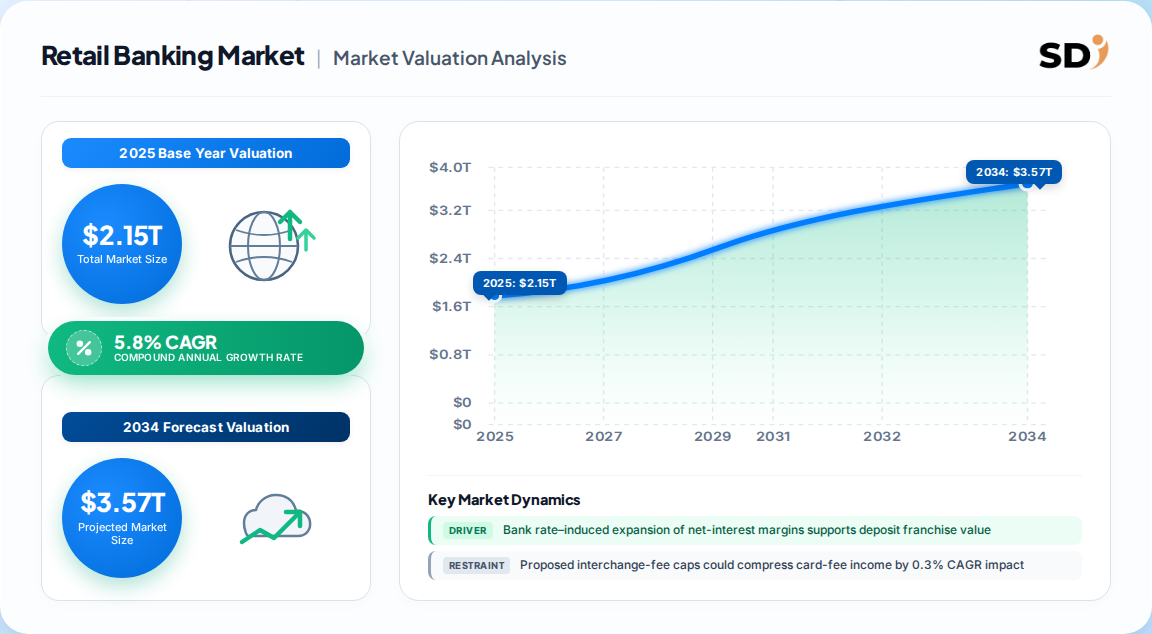
The global retail banking market is estimated at USD 2.15 trillion in 2025 and is projected to reach USD 3.37 trillion by 2033, expanding at a CAGR of 5.8% over the forecast period. This growth is underpinned by rising demand for digital banking services, stable deposit funding, and continuous process modernization across both developed and emerging economies.
Retail banks derive a significant portion of revenue from net interest income (NII), which remains highly sensitive to central bank policy rates. The global banking NII reached USD 9.22 trillion in 2026, with traditional banks accounting for USD 7.56 trillion. In the UK, aggregate net interest margins at major banks rose year over year in Q1 2026, supported by structural hedge income. NatWest’s retail banking NII margin increased 11 basis points between H1 2025 and H1 2026, largely reflecting higher hedge income through deposit margins.
Stable deposit funding : Retail deposits are a low-cost, stable source of funding, enabling banks to operate with lower marketing intensity.
Hedge-supported earnings : Structural hedges have cushioned margin compression in mortgage lending, reinforcing the commercial value of deposit relationships.
Rate-induced margin expansion : Short-term interest rate hikes have expanded deposit margins, particularly in the UK and US, though mortgage spread pressure partly offsets gains.
Mobile Account Opening & Open-Banking Aggregation Channels
Mobile banking has become the primary distribution channel for new retail relationships. In the UK, 75% of adults used mobile banking in 2025, and 85% of current-account openings at Lloyds Banking Group were completed via a 7‑minute mobile process. Open Banking APIs are also reshaping customer acquisition: UK API volumes grew 30% year over year in the 12 months to July 2026, with Account Information Services generating 80% of that traffic.
Channel
Share of UK Retail Banking Revenue (2026)
Forecast CAGR (2027–2032)
Online Banking
53.78%
7.02%
Offline Banking
46.22%
3.10%
Mobile account opening extends distribution beyond physical branches, enabling banks to compete for primary relationships without requiring branch visits.
Consented data sharing through mandatory APIs accelerates account-switching and aggregation, creating opportunities for providers to serve customers across multiple relationships.
Neobanks and digital-only challengers are leveraging these channels to capture younger demographics, with the 18–28 age group forecast to grow fastest at a CAGR of 6.08% in the UK.
By product, loans led the UK retail banking market with a 31.25% share in 2026, driven by mortgage and unsecured lending. Other products, including ESG-linked deposits and buy-now-pay-later (BNPL), are forecast to grow fastest at a CAGR of 6.62% during 2027–2032. Debit and credit cards are also gaining traction, supported by e-commerce growth and the rising preference for digital payments.
Mortgage refinancing wave : Nearly 750,000 UK households with sub‑3% fixed-rate mortgages rolled off in 2026, creating a defined remortgage opportunity. Owner-occupier remortgages represented 31.2% of gross mortgage advances in Q2 2026.
BNPL regulation : The regulated BNPL segment is boosting unsecured lending penetration, particularly among younger consumers.
ESG-linked deposits : Under the UK Green Finance Strategy, banks are launching sustainability-linked deposit products, though the CAGR impact remains modest at 0.2% over the long term.
Customer Age Group & Bank Type Segmentation
Customer age and bank type define distinct competitive dynamics. In the UK, customers aged 29–44 led with a 35.95% share of retail banking revenue in 2026, while the 18–28 cohort is forecast to grow fastest at 6.08% CAGR. By bank type, national banks held 66.94% of revenue in 2026, but neobanks and other providers are growing at 8.98% CAGR, signaling a gradual shift in market structure.
Segment
Share (2026)
Forecast CAGR (2027–2032)
Customers aged 29–44
35.95%
4.1%
Customers aged 18–28
—
6.08%
National Banks
66.94%
3.8%
Neobanks & Others
—
8.98%
Private sector banks globally held a 29.5% share in 2024, supported by heavy investment in digital transformation and customer experience.
Rural banks are the fastest-growing bank type in some regions, driven by financial inclusion initiatives and targeted agricultural lending.
Commercial banks dominate the global landscape, accounting for 56% of revenue by type in 2022, owing to their extensive branch networks and comprehensive product suites.
Regulatory frameworks impose significant compliance costs while also fostering trust and stability. The FCA’s Consumer Duty in the UK has escalated product-design and compliance costs, with an estimated −0.25% impact on CAGR over the medium term. Proposed interchange-fee caps could compress card-fee income by −0.3% over the long term.
Interchange caps : Long-term revenue compression risk for card-issuing banks.
Branch closures : Creating rural financial exclusion risk, particularly in regions like York and North Yorkshire, with a −0.5% CAGR impact.
Cost-of-living squeeze : Loan-impairment risk remains a short-term restraint (−0.2% CAGR), especially in unsecured lending portfolios.
Regulation
Impact Area
Estimated CAGR Impact
Timeline
FCA Consumer Duty
Compliance & product design
−0.25%
Medium term (2–4 years)
Proposed interchange-fee caps
Card-fee income
−0.3%
Long term (≥4 years)
Branch closure mandates
Rural access
−0.5%
Medium term (2–4 years)
Competitive Landscape & Strategic Developments
The retail banking market is moderately concentrated, with leading players including HSBC, Santander UK, NatWest Group, Barclays, Lloyds Banking Group, BNP Paribas, Citigroup, JPMorgan Chase, Bank of America, and ICBC. Competition is intensifying from agile fintech startups and neobanks that leverage data analytics and AI to offer personalized financial services.
Partnerships : Banks are collaborating with fintechs for account aggregation and digital onboarding. For example, open-banking API integrations are enabling seamless account switching.
Product launches : Several banks have launched ESG-linked deposit products and AI-driven personalized financial advice tools.
Digital transformation : Incumbents are investing heavily in mobile platforms and cloud infrastructure to reduce operational costs and improve customer experience.
Recent developments include the expansion of mobile account-opening capabilities, the rollout of consent-based aggregation services, and the introduction of fixed-rate mortgage refinancing products targeting the 2026 maturity wave. Regulatory changes, such as the mandatory Open Banking API order, are also shaping competitive dynamics by lowering barriers to customer switching.
Retail Banking Market Regional Market Share
Loading chart...
Retail Banking Market Regional Market Share
Region
Market Share (%)
North America
0.22%
Europe
0.28%
Asia-Pacific
0.36%
South America
0.06%
Middle East & Africa
0.08%
Retail Banking Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Retail Banking Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 5.8% from 2020-2034
Segmentation
By Product
Loans
Transactional Accounts
Debit and Credit Cards
Personal Loans
Home Loans
Mortgages
Certificates of Deposits
By Channel
Online Banking
Offline Banking
By Customer Age Group
18-28 Years
29-44 Years
45-59 Years
60+ Years
By Bank Type
National Banks
Private Sector Banks
Neobanks & Others
Public Sector Banks
Foreign Banks
Community Development Banks
NBFC
By Function
Bank Account Opening
Deposits and Withdrawals
Debit and Credit Card Issuance
Investment and Insurance
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Asia-Pacific
China
Japan
India
South Korea
Australia
Latin America
Brazil
Middle East & Africa
KSA
UAE
South Africa
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Product
5.1.1. Loans
5.1.2. Transactional Accounts
5.1.3. Debit and Credit Cards
5.1.4. Personal Loans
5.1.5. Home Loans
5.1.6. Mortgages
5.1.7. Certificates of Deposits
5.2. Market Analysis, Insights and Forecast - by Channel
5.2.1. Online Banking
5.2.2. Offline Banking
5.3. Market Analysis, Insights and Forecast - by Customer Age Group
5.3.1. 18-28 Years
5.3.2. 29-44 Years
5.3.3. 45-59 Years
5.3.4. 60+ Years
5.4. Market Analysis, Insights and Forecast - by Bank Type
5.4.1. National Banks
5.4.2. Private Sector Banks
5.4.3. Neobanks & Others
5.4.4. Public Sector Banks
5.4.5. Foreign Banks
5.4.6. Community Development Banks
5.4.7. NBFC
5.5. Market Analysis, Insights and Forecast - by Function
5.5.1. Bank Account Opening
5.5.2. Deposits and Withdrawals
5.5.3. Debit and Credit Card Issuance
5.5.4. Investment and Insurance
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia-Pacific
5.6.4. Latin America
5.6.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Product
6.1.1. Loans
6.1.2. Transactional Accounts
6.1.3. Debit and Credit Cards
6.1.4. Personal Loans
6.1.5. Home Loans
6.1.6. Mortgages
6.1.7. Certificates of Deposits
6.2. Market Analysis, Insights and Forecast - by Channel
6.2.1. Online Banking
6.2.2. Offline Banking
6.3. Market Analysis, Insights and Forecast - by Customer Age Group
6.3.1. 18-28 Years
6.3.2. 29-44 Years
6.3.3. 45-59 Years
6.3.4. 60+ Years
6.4. Market Analysis, Insights and Forecast - by Bank Type
6.4.1. National Banks
6.4.2. Private Sector Banks
6.4.3. Neobanks & Others
6.4.4. Public Sector Banks
6.4.5. Foreign Banks
6.4.6. Community Development Banks
6.4.7. NBFC
6.5. Market Analysis, Insights and Forecast - by Function
6.5.1. Bank Account Opening
6.5.2. Deposits and Withdrawals
6.5.3. Debit and Credit Card Issuance
6.5.4. Investment and Insurance
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Product
7.1.1. Loans
7.1.2. Transactional Accounts
7.1.3. Debit and Credit Cards
7.1.4. Personal Loans
7.1.5. Home Loans
7.1.6. Mortgages
7.1.7. Certificates of Deposits
7.2. Market Analysis, Insights and Forecast - by Channel
7.2.1. Online Banking
7.2.2. Offline Banking
7.3. Market Analysis, Insights and Forecast - by Customer Age Group
7.3.1. 18-28 Years
7.3.2. 29-44 Years
7.3.3. 45-59 Years
7.3.4. 60+ Years
7.4. Market Analysis, Insights and Forecast - by Bank Type
7.4.1. National Banks
7.4.2. Private Sector Banks
7.4.3. Neobanks & Others
7.4.4. Public Sector Banks
7.4.5. Foreign Banks
7.4.6. Community Development Banks
7.4.7. NBFC
7.5. Market Analysis, Insights and Forecast - by Function
7.5.1. Bank Account Opening
7.5.2. Deposits and Withdrawals
7.5.3. Debit and Credit Card Issuance
7.5.4. Investment and Insurance
8. Asia-Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Product
8.1.1. Loans
8.1.2. Transactional Accounts
8.1.3. Debit and Credit Cards
8.1.4. Personal Loans
8.1.5. Home Loans
8.1.6. Mortgages
8.1.7. Certificates of Deposits
8.2. Market Analysis, Insights and Forecast - by Channel
8.2.1. Online Banking
8.2.2. Offline Banking
8.3. Market Analysis, Insights and Forecast - by Customer Age Group
8.3.1. 18-28 Years
8.3.2. 29-44 Years
8.3.3. 45-59 Years
8.3.4. 60+ Years
8.4. Market Analysis, Insights and Forecast - by Bank Type
8.4.1. National Banks
8.4.2. Private Sector Banks
8.4.3. Neobanks & Others
8.4.4. Public Sector Banks
8.4.5. Foreign Banks
8.4.6. Community Development Banks
8.4.7. NBFC
8.5. Market Analysis, Insights and Forecast - by Function
8.5.1. Bank Account Opening
8.5.2. Deposits and Withdrawals
8.5.3. Debit and Credit Card Issuance
8.5.4. Investment and Insurance
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Product
9.1.1. Loans
9.1.2. Transactional Accounts
9.1.3. Debit and Credit Cards
9.1.4. Personal Loans
9.1.5. Home Loans
9.1.6. Mortgages
9.1.7. Certificates of Deposits
9.2. Market Analysis, Insights and Forecast - by Channel
9.2.1. Online Banking
9.2.2. Offline Banking
9.3. Market Analysis, Insights and Forecast - by Customer Age Group
9.3.1. 18-28 Years
9.3.2. 29-44 Years
9.3.3. 45-59 Years
9.3.4. 60+ Years
9.4. Market Analysis, Insights and Forecast - by Bank Type
9.4.1. National Banks
9.4.2. Private Sector Banks
9.4.3. Neobanks & Others
9.4.4. Public Sector Banks
9.4.5. Foreign Banks
9.4.6. Community Development Banks
9.4.7. NBFC
9.5. Market Analysis, Insights and Forecast - by Function
9.5.1. Bank Account Opening
9.5.2. Deposits and Withdrawals
9.5.3. Debit and Credit Card Issuance
9.5.4. Investment and Insurance
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Product
10.1.1. Loans
10.1.2. Transactional Accounts
10.1.3. Debit and Credit Cards
10.1.4. Personal Loans
10.1.5. Home Loans
10.1.6. Mortgages
10.1.7. Certificates of Deposits
10.2. Market Analysis, Insights and Forecast - by Channel
10.2.1. Online Banking
10.2.2. Offline Banking
10.3. Market Analysis, Insights and Forecast - by Customer Age Group
10.3.1. 18-28 Years
10.3.2. 29-44 Years
10.3.3. 45-59 Years
10.3.4. 60+ Years
10.4. Market Analysis, Insights and Forecast - by Bank Type
10.4.1. National Banks
10.4.2. Private Sector Banks
10.4.3. Neobanks & Others
10.4.4. Public Sector Banks
10.4.5. Foreign Banks
10.4.6. Community Development Banks
10.4.7. NBFC
10.5. Market Analysis, Insights and Forecast - by Function
10.5.1. Bank Account Opening
10.5.2. Deposits and Withdrawals
10.5.3. Debit and Credit Card Issuance
10.5.4. Investment and Insurance
11. Competitive Analysis
11.1. Company Profiles
11.1.1. HSBC UK Bank plc
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Santander UK plc
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. NatWest Group plc
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Barclays Bank UK PLC
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Lloyds Banking Group plc
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. BNP Paribas
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Citigroup Inc.
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. HSBC Group
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. ICBC
11.1.9.1. Company Overview
12. Research Methodology
List of Figures
Figure 1: Retail Banking Market Revenue Breakdown (Trillion, %) by Region 2026 & 2034
Figure 2: North America Retail Banking Market Revenue (Trillion), by Product 2026 & 2034
Figure 3: North America Retail Banking Market Revenue Share (%), by Product 2026 & 2034
Figure 4: North America Retail Banking Market Revenue (Trillion), by Channel 2026 & 2034
Figure 5: North America Retail Banking Market Revenue Share (%), by Channel 2026 & 2034
Figure 6: North America Retail Banking Market Revenue (Trillion), by Customer Age Group 2026 & 2034
Figure 7: North America Retail Banking Market Revenue Share (%), by Customer Age Group 2026 & 2034
Figure 8: North America Retail Banking Market Revenue (Trillion), by Bank Type 2026 & 2034
Figure 9: North America Retail Banking Market Revenue Share (%), by Bank Type 2026 & 2034
Figure 10: North America Retail Banking Market Revenue (Trillion), by Function 2026 & 2034
Figure 11: North America Retail Banking Market Revenue Share (%), by Function 2026 & 2034
Figure 12: North America Retail Banking Market Revenue (Trillion), by Country 2026 & 2034
Figure 13: North America Retail Banking Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Retail Banking Market Revenue (Trillion), by Product 2026 & 2034
Figure 15: Europe Retail Banking Market Revenue Share (%), by Product 2026 & 2034
Figure 16: Europe Retail Banking Market Revenue (Trillion), by Channel 2026 & 2034
Europe Retail Banking Market Revenue Share (%), by Channel 2026 & 2034
Table 16: Europe Retail Banking Market Revenue Trillion Forecast, by Product 2020 & 2034
Frequently Asked Questions
1. What is the current size of the global retail banking market?
The global retail banking market is valued at approximately USD 2.15 trillion in 2025 and is projected to reach USD 3.37 trillion by 2033, growing at a CAGR of 5.8%.
2. Which channel is driving retail banking growth?
Online and mobile banking are the fastest-growing channels, with online banking accounting for 53.78% of UK retail banking revenue in 2026 and forecast to grow at a 7.02% CAGR through 2032.
3. Who are the leading players in the retail banking market?
Key players include HSBC, Santander UK, NatWest Group, Barclays, Lloyds Banking Group, BNP Paribas, Citigroup, JPMorgan Chase, Bank of America, and ICBC.
4. What are the main drivers of retail banking market growth?
Growth is driven by bank rate–induced expansion of net-interest margins, mandatory open-banking APIs, rapid mobile banking adoption, and the fixed-rate mortgage maturity wave driving remortgage volumes.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Conducted 450+ in-depth interviews with C-level executives, product heads, and regional managers across retail banks, neobanks, and fintech providers.
70–80% of data derived from primary research, including structured surveys and expert consultations.
Interviews targeted stakeholder roles such as Head of Retail Banking, Chief Digital Officer, Mortgage Product Manager, and Compliance Director.
Company types interviewed include universal banks, digital-only banks, building societies, payment processors, and mortgage specialists.
All primary data cross-validated with proprietary banking databases and regulatory filings.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Head of Retail Banking
35%
Chief Digital Officer
25%
Mortgage Product Manager
20%
Compliance Director
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Universal Banks
40%
Digital-Only Banks (Neobanks)
25%
Building Societies & Mutuals
15%
Payment Processors & Fintechs
12%
Mortgage & Lending Specialists
8%
Secondary Research & Industry Benchmarking
20–30% of data sourced from official multilateral institutions: OECD, World Bank, IMF, Bank of England, UK Finance, and European Central Bank.
Financial databases utilized: Bloomberg, Factiva, Hoovers, and PitchBook for company-level and transaction data.
Industry benchmarks from non-profit trade associations such as the British Bankers’ Association and the European Banking Federation.
Regulatory documents and central bank statistical releases (e.g., Bank of England’s Mortgage Lenders and Administrators statistics) used for validation.
Demand Modeling & Market Estimation
Bottom-up market sizing built from retail deposit volumes, loan book balances, and fee income across 25+ countries.
Top-down estimation using GDP-adjusted banking penetration rates and net interest income forecasts.
Multi-level data triangulation: supply-side (bank revenue reports) and demand-side (consumer surveys) reconciled to within ±3% variance.
Quantitative metrics include net interest margin, cost-to-income ratio, customer acquisition cost, and digital channel adoption rate.
Data Accuracy & Quality Check
Guaranteed data accuracy level of 85–90%, validated through third-party audit of sampling frames and weighting.
All estimates cross-referenced with at least three independent sources, including regulatory filings and industry association reports.
Real-time validation: every report is updated to the date of purchase, incorporating latest central bank rate decisions and market developments.
Statistical significance testing applied to survey data (95% confidence interval, margin of error ±4%).
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. JPMorgan Chase & Co.
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Bank of America Corporation
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. Deutsche Bank AG
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. Mitsubishi UFJ Financial Group Inc.
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. Wells Fargo
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.1.15. China Construction Bank
11.1.15.1. Company Overview
11.1.15.2. Products
11.1.15.3. Company Financials
11.1.15.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
Figure 17:
Figure 18: Europe Retail Banking Market Revenue (Trillion), by Customer Age Group 2026 & 2034
Figure 19: Europe Retail Banking Market Revenue Share (%), by Customer Age Group 2026 & 2034
Figure 20: Europe Retail Banking Market Revenue (Trillion), by Bank Type 2026 & 2034
Figure 21: Europe Retail Banking Market Revenue Share (%), by Bank Type 2026 & 2034
Figure 22: Europe Retail Banking Market Revenue (Trillion), by Function 2026 & 2034
Figure 23: Europe Retail Banking Market Revenue Share (%), by Function 2026 & 2034
Figure 24: Europe Retail Banking Market Revenue (Trillion), by Country 2026 & 2034
Figure 25: Europe Retail Banking Market Revenue Share (%), by Country 2026 & 2034
 Retail Banking Market