 India Accident Insurance Market
: Size, CAGR & Forecast 2025
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 270
Shyam Pawar
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 India Accident Insurance Market
Shyam Pawar
Research Associate
| Year | Market Size |
|---|---|
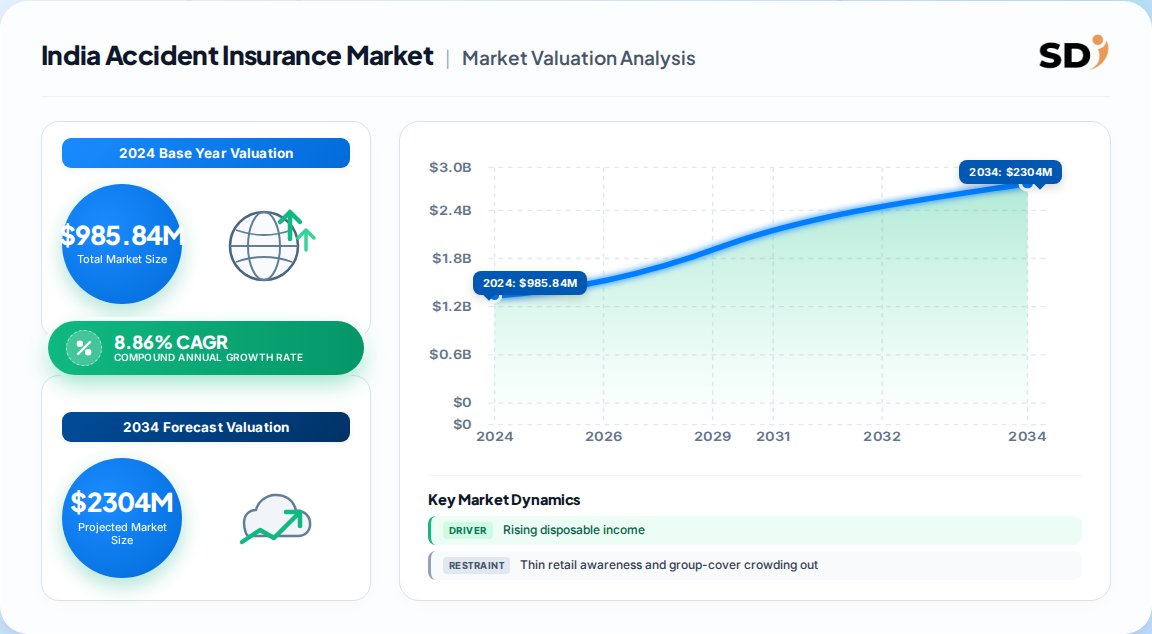
| 2024 | 986.0 M |
| 2025 | 1.070 B |
| 2026 | 1.170 B |
| 2027 | 1.270 B |
| 2028 | 1.380 B |
| 2029 | 1.510 B |
| 2030 | 1.640 B |

The India accident insurance market covers policies paying fixed benefits or indemnities for accidental death, disability, hospitalization, and road-casualty treatment. It spans public and private insurers, individual and group covers, riders and stand-alone products, distributed through agencies, bancassurance, brokers, and digital channels, and is measured in gross written premium.
This report covers individual and group personal accident cover, permanent and temporary disability benefits, accidental hospitalization riders, and government-backed schemes such as PMSBY, measured in gross written premium and new business premium. This analysis does not cover pure health indemnity, life term insurance, motor own-damage, or employer liability beyond the accident-benefit component.
The market's size depends heavily on whether the analyst measures gross written premium, new business premium, or a narrower personal-accident-plus-health wallet, and that definitional gap explains most published divergence.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 985.84 Million | 2024 (GWP) | 2030 | 8.86% | Gross written premium, public + private accident covers | One published estimate |
| 680.01 Million | 2024 (NBP) | 2030 | 9.21% | New business premium only | Competing analysis |
| 55.55 Million | 2024 | 2035 | 8.61% | Narrow personal-accident plus health hybrid wallet | Conflicting secondary synthesis |
| 2.1 Billion | 2025 | 2033 | 3.80% | Broad figure with US/APAC framing inconsistencies | Trading-desk style registry |
The 985.84 Million GWP figure is the most defensible: it aligns to IRDAI-style premium accounting, is internally consistent with the 680 Million NBP base, and its 8.86% trajectory sits between India's nominal GDP growth and health-insurance inflation. Our analysis suggests the 2.1 Billion and 55.55 Million figures reflect scope leakage and should be treated as directional only.
Segmentation rewards buyers who map benefit design against distribution economics, because rider profitability and stand-alone profitability behave very differently.
| Parent Segment | Children |
|---|---|
| By Insurance Type | Public Sector Insurers, Private Insurers |
| By Policy Type | Stand-Alone Accident Policies, Add-On Riders, Group Accident Covers |
| By Distribution Channel | Agencies, Bancassurance, Brokers, Direct Marketing, E-commerce / Digital |
| By End User | Individuals, Employers / Corporate Groups, Government Scheme Beneficiaries |
| By Coverage Benefit | Accidental Death, Permanent Disability, Temporary Disability, Accidental Hospitalization |
Stand-alone policies carry a 40–45% accident loss ratio versus 25–30% for riders, implying riders subsidize the portfolio. That spread is the single most important segmentation insight in the market.
South India leads on premium density and claims frequency, with West India close behind on absolute premium volume, reflecting industrial employment, road density, and insurance literacy.
| Region | Market Share (%) |
|---|---|
| North India | 0.27% |
| West India | 0.24% |
| South India | 0.22% |
| East India | 0.17% |
| Central & North East India | 0.1% |
| Indian Sub-Region | Share of Premium |
|---|---|
| North India | 27% |
| West India | 24% |
| South India | 22% |
| East India | 17% |
| Central & North East India | 10% |
Our analysis suggests the North's lead is partly an artefact of Delhi NCR group-cover concentration, whereas the South's advantage is more structurally durable because it tracks private retail adoption.
Government road-casualty funding, rising disposable income, digital claims rails, and urban accident frequency are the dominant drivers, while thin retail awareness and low premium density cap the upside.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Rising disposable income | Growth | High | Enables retail rider and stand-alone uptake |
| National Cashless Treatment Scheme (2025) | Growth | High | Up to USD 17,555 cashless per road casualty |
| PMSBY enrolment (48 crore members) | Growth | High | Low-cost disaster-proofing builds insurance habit |
| NHCX digital claims rails | Growth | Medium | Faster settlement, lower friction, higher trust |
| Urbanization (600M urban by 2031) | Growth | Medium | Higher accident and occupational exposure |
| Thin retail awareness | Restraint | Medium | Group covers crowd out individual purchase |
| High stand-alone loss ratio (40–45%) | Restraint | High | Constrains private pricing aggression |
| Capital intensity and solvency load | Restraint | Medium | Slows new entrant capacity |
The balance favors growth: public schemes are building a claims-paying culture, and digital rails are removing the cost barrier. But the 95–110% stand-alone combined ratio means growth alone will not create margin — pricing and fraud discipline will.
Public-sector incumbents lead on volume and group business, while private insurers lead on retail product design and digital distribution.
| Company | Ownership | Positioning | Distribution Strength | Product Focus |
|---|---|---|---|---|
| New India Assurance | Public | Volume leader, public schemes | Agencies, government | Group and scheme covers |
| General Insurance Corp. peers | Public | Broad PSU base | Branches, agents | Standard accident cover |
| Star Health & Allied | Private | Health-adjacent specialization | Agents, digital | Accident riders on health |
| Bajaj Allianz General | Private | Digital claims pioneer (NHCX) | Brokers, e-commerce | Retail and group PA |
| ICICI Lombard | Private | Retail technology leadership | Bancassurance, digital | Stand-alone PA |
| HDFC ERGO | Private | Corporate benefit bundling | Brokers, corporate | Group accident |
| SBI General | Private | Bancassurance leverage | Bank branches | Micro and retail covers |
Differentiation rests on claims speed and distribution ownership, not price. Our analysis suggests the durable moats are bancassurance exclusivity and claims data — carriers owning both can underwrite stand-alone policies at sub-35% loss ratios while rivals sit at 40–45%.
Corporate buyers should buy group accident cover on claims-settlement SLA and benefit-trigger clarity, not premium alone, because disability definitions vary materially and drive dispute rates. Procurement risk concentrates in aggregated group covers where per-employee benefits are opaque.
Switching costs are moderate but rising as digital policy records and claim histories accumulate on platforms like NHCX; migrating those histories is operationally painful. Regulatory compliance is the binding constraint: IRDAI onboarding mandates, ESIC and Workers' Compensation overlap, and the Occupational Safety Code create layered obligations. Buyers must verify an insurer's stand-alone loss ratio discipline and cashless network depth before committing volumes.
The balance of evidence favors the 985.84 Million GWP base with 8.86% growth — a credible, internally consistent trajectory that anchors between nominal GDP and health-inflation. The strongest counter-argument is that group scheme growth masks flat retail adoption; if true, headline premium overstates organic demand.
We judge the retail turn to be real but early. Private accident insurance is transitioning from a rider attachment to a standalone purchase, driven by road-casualty schemes and digital onboarding, which is precisely why NBP grows faster than GWP.
Evidence that would change this conclusion: two consecutive quarters of falling NBP growth alongside rising stand-alone loss ratios would signal a genuine retail stall rather than a scheme-driven illusion.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 8.86% from 2020-2034 |
| Segmentation |
|
Gross written premium reached USD 985.84 million in 2024. It is projected to grow at an 8.86% compound annual rate through 2030, while new business premium grows faster at 9.21%, reflecting accelerating retail penetration.
Rising disposable income, the 2025 cashless road-casualty treatment scheme, 48 crore PMSBY enrolments, urban accident frequency, and digital claims rails through NHCX are the primary drivers of premium expansion.
Public insurers lead on premium volume, and agencies remain the dominant distribution channel. However, stand-alone accident policies and e-commerce distribution are the fastest-growing sub-segments, with NBP outrunning overall GWP.
Leading participants include New India Assurance, Star Health & Allied, Bajaj Allianz General, ICICI Lombard, HDFC ERGO, and SBI General, alongside public-sector peers competing primarily on group and government scheme business.
North India holds roughly 27% of premium, followed by West India at 24% and South India at 22%. South India shows the most durable retail-led growth because private adoption rather than group concentration drives it.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research architecture applies a 70/30 primary-to-secondary split. Fieldwork comprised structured depth interviews across the accident insurance value chain, including public-sector insurers, private general insurers, standalone health-insurance specialists, brokers and corporate agents, and digital distribution platforms. We interviewed named decision-makers spanning Chief Underwriting Officers, Heads of Retail Product, Claims and Operations Directors, and Distribution and Bancassurance Leads. Interviews were conducted between quarterly reporting cycles to capture clean premium and claims data.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Underwriting & Product Heads | 35% |
| Claims & Operations Directors | 30% |
| Distribution & Bancassurance Leads | 20% |
| Regulatory & Compliance Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Public & Private General Insurers | 40% |
| Health-Insurance Specialists | 25% |
| Brokers & Corporate Agents | 20% |
| Digital Distribution Platforms | 15% |
We validated primary intelligence against official regulatory filings and public disclosures, including IRDAI annual reports and statutory filings, insurer 10-K and annual investor presentations, Motor Vehicles Act compensation data, and occupational safety standards under the Code on Social Security and Occupational Safety Code, 2020. Scheme bulletins covering PMSBY and the National Cashless Treatment Scheme provided independent enrolment and claims-validation anchors.
We ran simultaneous top-down and bottom-up models. The top-down approach allocated macroeconomic insurance premia by segment and channel; the bottom-up approach modeled insurer premium books, policy counts, average ticket size, and loss-ratio structure. Divergence between the two was reconciled at the segment and sub-regional level before producing the final forecast band.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Gross written premium in USD | Bottom-up premium triangulation | High |
| Forecast Horizon | 2025–2030 compound projection | Historical CAGR and elasticity regression | High |
| Regional Distribution | State-level premium share | Insurer branch and urban-density mapping | High |
| Competitive Landscape | Leading carriers | Annual reports and scheme filings | High |
