 Asset Tokenization Market
 Outlook 2026: Size, CAGR & Trends
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 213
Shyam Pawar
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Asset Tokenization Market
Shyam Pawar
Research Associate
| Year | Market Size |
|---|---|
| 2025 | 2.080 M |
| 2026 | 3.010 M |
| 2027 | 4.340 M |
| 2028 | 6.260 M |
| 2029 | 9.030 M |
| 2030 | 13.02 M |
| 2031 | 18.74 M |

Asset tokenization is the conversion of ownership rights in real-world or financial assets — real estate, treasuries, funds, private equity, commodities — into blockchain-based digital tokens that can be fractionalized, transferred and settled programmatically. The market measures the value of assets issued, platform and middleware revenue, and associated compliance and legal-technology services.
This analysis covers tokenized real-world and financial assets across real estate, financial instruments, investment funds, private equity, commodities and intellectual property. It spans institutional and accredited retail investors, permissioned and permissionless platforms, and platform, service and compliance offerings worldwide. This analysis does not cover native cryptocurrencies, stablecoin issuance economics, NFTs as a collectibles category, or pure blockchain infrastructure hardware.
Published estimates diverge by more than an order of magnitude, largely because analysts measure different things: some size the value of assets tokenized on-chain, others the addressable technology and services revenue pool. The table below reconciles the leading published views.
| Estimate | Base Year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 2.08 Trillion (2025); USD 18.74 Trillion (2031) | 2025 | 2026–2031 | 44.25% | Tokenized asset value plus platform and service revenue, global | One published industry estimate |
| USD 1.8 Trillion (2025); USD 24.5 Trillion (2033) | 2025 | 2026–2033 | 42.1% | Tokenized asset value, broader asset-class inclusion | A competing analysis |
| USD 6.10 Billion (2025); USD 35.2 Billion (2034) | 2025 | 2026–2034 | 21.5% | Vendor revenue only (software, middleware, services) | A third published estimate |
Our read: the trillion-scale figures are defensible only as asset-value measures, not revenue. The USD 6.10 billion figure is the most credible proxy for the actual vendor revenue pool, and the ~21.5% CAGR attached to it is the one buyers should underwrite when building a business case. The divergence implies the technology layer is monetizing far more slowly than headline tokenized-asset values suggest — a critical distinction for procurement and investment committees.
Buyers should segment on four axes simultaneously, because growth rates differ sharply within each. Real estate dominates today, but the fastest compounding sits in commodities, private equity, retail access and compliance services.
| Parent Segment | Children | 2025 Position | Fastest-growing child |
|---|---|---|---|
| By Asset Class | Real estate, financial instruments, investment funds, private equity, commodities, intellectual property | Real estate (30.12%) | Commodities (48.35% CAGR) |
| By Investor Type | Institutional investors, accredited retail investors | Institutional (69.10%) | Accredited retail (50.20% CAGR) |
| By Tokenization Platform | Permissioned (private) blockchains, permissionless (public) blockchains | Permissioned (50.60%) | Permissionless (51.60% CAGR) |
| By Offering | Tokenization platforms/middleware, tokenization services, compliance and legal technology | Platforms/middleware (59.05%) | Compliance and legal tech (47.95% CAGR) |
The North America region leads, generating 39.10% of 2025 revenue on the back of US regulatory clarity, established custodian infrastructure and early institutional product launches. Asia-Pacific is the fastest-growing region at 53.75% CAGR, driven by Singapore and Hong Kong sandboxes.
| Region | Market Share (%) |
|---|---|
| North America | 0.39% |
| Europe | 0.24% |
| Asia-Pacific | 0.26% |
| South America | 0.06% |
| Middle East & Africa | 0.06% |
The pattern is clear: North America monetizes compliance today, while Asia-Pacific is buying infrastructure for tomorrow. Our analysis suggests the APAC growth rate is inflated by a low revenue base and sandbox-driven pilots; converting pilots into production licensing is the single largest execution risk in the forecast.
Institutional adoption of tokenized funds and settlement efficiency is the strongest single driver, adding an estimated +12.5% to CAGR in the near term. Regulatory clarity (+8.2%) and interoperability (+7.1%) are structural, while cybersecurity and regulatory fragmentation subtract roughly 5.7% and 4.2% respectively.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Institutional tokenized funds and treasury products | Driver | Strong | Programmable settlement cuts capital lock-up; network effects pull in custodians |
| Regulatory clarity in North America and EU | Driver | Strong | MiCA-style frameworks legalize issuance and secondary trading |
| Fractional real-estate demand | Driver | Moderate | Lower ticket sizes widen investor base and secondary liquidity |
| Blockchain interoperability (cross-chain, DvP) | Driver | Moderate | Unified liquidity pools reduce settlement risk |
| Regulatory fragmentation and compliance cost | Restraint | Strong | Jurisdiction-by-jurisdiction licensing slows cross-border scaling |
| Smart-contract and oracle vulnerabilities | Restraint | Moderate | Exploits raise insurance costs and deter conservative institutions |
| Custodial liability in insolvency | Restraint | Moderate | Unclear bankruptcy treatment blocks regulated balance-sheet use |
The net balance favors growth decisively, but the composition of growth matters: adoption is being pulled by regulated incumbents rather than pushed by decentralized innovation. That favors vendors with legal and compliance depth over pure-protocol players.
The competitive field is medium-concentration and splits into three camps: incumbent market infrastructure, regulated digital-asset platforms, and blockchain/middleware providers. Differentiation increasingly rests on legal wrappers, ISO-20022 messaging and cross-chain settlement rather than raw tokenization capability.
| Vendor Type | Representative Players | Strategic Moat |
|---|---|---|
| Incumbent market infrastructure | Depository Trust & Clearing Corporation (ComposerX), JPMorgan Kinexys | Regulatory trust, custody relationships, settlement rails |
| Regulated tokenization platforms | Securitize, Republic, Franklin Templeton (Benji) | Licenses, fund distribution, retail access |
| Asset managers operating tokenized funds | BlackRock (BUIDL), Goldman Sachs, Fidelity International | AUM scale, brand, institutional distribution |
| Middleware and interoperability | Chainlink (CCIP), Coreum (ISO-20022 native) | Cross-chain rails, messaging standards |
Our analysis suggests the strongest moats belong to firms combining legal enforceability with settlement connectivity — a combination most pure-technology vendors cannot replicate. JPMorgan's Kinexys having processed roughly USD 1.5 trillion in tokenized transactions by end-2024 illustrates how incumbent distribution compounds quickly once rails exist.
Selection decisions should hinge on five mission-critical criteria: legal enforceability of the token wrapper, regulatory licensing coverage across target jurisdictions, interoperability with existing custody and core banking, audit and oracle resilience, and the depth of secondary-market liquidity. Procurement teams routinely underweight the third and fifth.
Switching costs are deceptively high. Once a fund administrator, custodian and transfer agent are integrated via ISO-20022 messaging, migration requires re-papering legal agreements and re-certifying settlement flows — typically a 9–18 month programme. Buyers should negotiate exit and data-portability clauses before signing, and insist on contractual clarity around insolvency treatment of tokens held in custody.
Compliance risk is the dominant procurement hazard: a platform that is licensed in one jurisdiction may be unusable for cross-border distribution. Operators should verify MiCA alignment for EU issuance and confirm that smart-contract audits include oracle manipulation testing, not just code review.
The balance of evidence favors regulated-incumbent infrastructure over decentralized-native platforms through 2028. Every high-conviction data point — DTCC's ComposerX consortium, JPMorgan's MONY fund, BlackRock's BUIDL distribution on UniswapX — points to institutions extending existing rails rather than replacing them. The trillion-dollar forecasts are real as asset-value measures, but the monetizable vendor pool is closer to single-digit billions, and growth there is roughly half the headline rate.
The strongest counter-argument: permissionless networks are compounding at 51.60% CAGR and commodities at 48.35%, faster than the institutional core. If cross-chain interoperability matures faster than expected, open networks could capture issuance share sooner than the base case allows, compressing margins for permissioned-only vendors. We weight this as a genuine but secondary risk — compliance tooling, not technology, remains the binding constraint.
Actionable strategy:
What would change our conclusion: evidence that permissionless networks are clearing regulated settlement at scale with institutional-grade custody, or a US federal framework that removes jurisdiction-by-jurisdiction licensing friction. Either would shift the advantage decisively toward open infrastructure.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 44.25% from 2020-2034 |
| Segmentation |
|
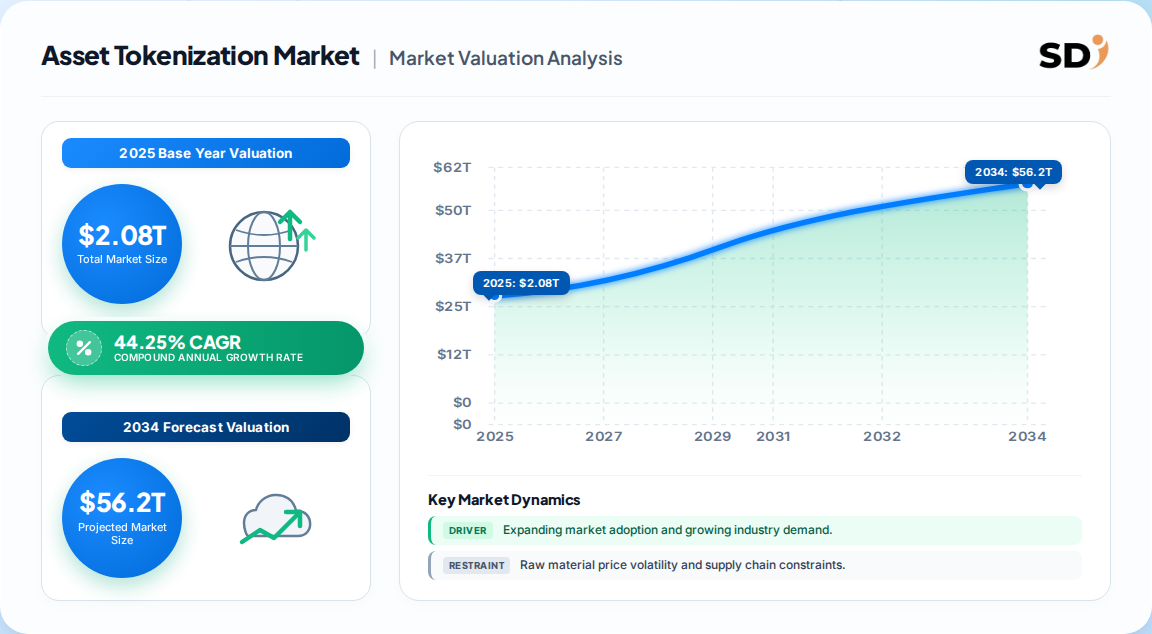
The market was valued at USD 2.08 trillion in 2025, measured on tokenized asset value. Vendor revenue alone is far smaller — one published estimate puts technology and services revenue near USD 6.10 billion in 2025, a critical distinction for business-case planning.
Consensus forecasts a 44.25% CAGR from 2026 to 2031, reaching USD 18.74 trillion. Revenue-focused estimates are more conservative, at roughly 21.5% CAGR, reflecting slower monetization of the technology and services layer.
Real estate led with 30.12% of 2025 share, supported by large tangible asset values and fractional-ownership demand. Commodities are the fastest-growing class at a projected 48.35% CAGR, driven by carbon-credit and precious-metal instruments.
Asia-Pacific is forecast to grow at 53.75% CAGR through 2031, led by Singapore and Hong Kong regulatory sandboxes. North America remains the largest market at 39.10% of 2025 revenue, anchored by institutional product launches.
The field spans incumbent infrastructure such as DTCC and JPMorgan Kinexys, regulated platforms such as Securitize and Republic, asset managers including BlackRock and Franklin Templeton, and middleware providers like Chainlink and Coreum.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study follows a 70/30 primary-to-secondary research split. Primary fieldwork comprised structured depth interviews with decision-makers across the tokenization value chain, including tokenization platform and middleware providers, regulated digital-asset exchanges, custodians and fund administrators, asset managers issuing tokenized vehicles, and legal/compliance technology vendors. Interviews were conducted with Heads of Digital Assets, Chief Compliance Officers, Heads of Product, and Institutional Sales Directors, ensuring coverage of both build-side and buy-side perspectives.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Heads of Digital Assets | 35% |
| Chief Compliance Officers | 28% |
| Heads of Product & Technology | 22% |
| Institutional Sales Directors | 15% |
| Company Type | Representation (%) |
|---|---|
| Tokenization Platforms & Middleware | 35% |
| Asset Managers & Fund Issuers | 25% |
| Custodians & Market Infrastructure | 22% |
| Legal, Compliance & Advisory | 18% |
Secondary validation drew on official multilateral and regulatory sources, corporate annual filings and investor presentations (10-K, SEC filings), patent and standards databases, and recognised industry associations. Cross-border capital-flow and settlement data were benchmarked against Eurostat, UN Comtrade and WTO statistics where applicable, alongside central-bank pilot disclosures and securities-regulator publications.
We ran simultaneous top-down and bottom-up models. The top-down model allocates macroeconomic capital-markets activity across asset classes and investor types; the bottom-up model builds from platform issuance volumes, average ticket sizes and end-investor consumption. The two are triangulated to produce a single reconciled base-year value and compound projection.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up issuance and revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
