 Real Time Monitoring Solutions Cold Chain Market
 2025
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 271
Sakshi Chavan

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Real Time Monitoring Solutions Cold Chain Market
Sakshi Chavan
Research Associate
| Year | Market Size |
|---|---|
| 2024 | 15.35 B |
| 2025 | 18.80 B |
| 2026 | 23.03 B |
| 2027 | 28.21 B |
| 2028 | 34.56 B |
| 2029 | 42.34 B |
| 2030 | 51.87 B |

The Real Time Monitoring Solutions Cold Chain Market covers integrated IoT sensor, GPS, data-logger, and cloud-platform systems that continuously track temperature, humidity, and location of temperature-sensitive goods across storage and transport — delivering live alerts, compliance records, and predictive analytics to pharmaceutical, food, and chemical supply chains.
This report covers hardware (sensors, GPS trackers, RFID tags, data loggers), software (cloud and on-premise), and associated services (installation, maintenance, consulting) deployed across food & beverage, pharmaceuticals, chemicals, healthcare, retail/e-commerce, and logistics end users, globally.
This analysis does not cover passive cold-chain packaging (insulated shippers, phase-change materials), refrigerated vehicle manufacturing, cold-storage warehousing capacity markets, or blockchain-only traceability platforms sold independently of monitoring hardware.
Estimates cluster around a mid-teens-billion-dollar base in 2024–2025, but terminal values diverge by more than 2x because analysts disagree on whether services and software attach rates are counted inside the monitoring envelope.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 15.35 Billion | 2024 | 2034 | 22.5% | Hardware + software + services, broad end-user set | One published estimate |
| USD 12.4 Billion | 2023 | 2030 | 23.1% | Hardware + software, narrower service inclusion | A competing analysis |
| USD 7.96 Billion | 2025 | 2030 | 14.9% | Tracking & monitoring only, excludes broader services | A third benchmark (adjacent definition) |
Our analysis suggests the USD 15.35 billion / 22.5% framing is the most defensible for buyers evaluating total spend, because it explicitly bundles installation and maintenance services — the cost line that most often surprises procurement teams. The lower USD 7.96 billion figure reflects a narrower "tracking and monitoring" definition that excludes managed services, and should be treated as a hardware-plus-software floor rather than a full market view.
Segmentation is best understood along three axes — component, end-user industry, and deployment model — with component mix being the single most consequential variable for vendor strategy.
| Parent segment | Children |
|---|---|
| By Component | Hardware (Sensors, GPS Trackers, RFID Tags & Labels, Data Loggers, Wireless Communication Devices, Portable Monitoring Units); Software (Cloud, On-Premise); Services (Installation, Maintenance & Support, Consulting) |
| By End-User Industry | Food & Beverage, Pharmaceuticals, Chemicals, Healthcare, Retail & E-commerce, Logistics & Transportation, Others |
| By Solution Type | Storage Monitoring, Transportation Monitoring |
Hardware's 64–76% revenue share is a legacy of sensor unit economics, but software's 24.7% CAGR implies the revenue mix will rebalance materially by 2030 — a shift that favors vendors with strong analytics and compliance-reporting layers.
North America leads with roughly 34% revenue share, anchored by FDA and USDA enforcement, mature logistics infrastructure, and early IoT adoption; Asia-Pacific is the fastest-growing region as cold-chain capacity expands.
| Region | Market Share (%) |
|---|---|
| North America | 0.34% |
| Europe | 0.25% |
| Asia-Pacific | 0.27% |
| Latin America | 0.08% |
| Middle East & Africa | 0.06% |
| Region | 2024 share |
|---|---|
| North America | 34% |
| Europe | 25% |
| Asia-Pacific | 27% |
| Latin America | 8% |
| Middle East & Africa | 6% |
The U.S. alone was valued at roughly USD 5.03 billion in 2024 per one estimate — a figure that exceeds the entire global total in competing analyses, underscoring how definitional scope (services, healthcare IT overlap) inflates country-level valuations. Buyers should benchmark country figures against a single consistent scope before comparing.
Regulatory mandates and spoilage economics are the dominant demand drivers, while upfront capital cost and emerging-market infrastructure gaps are the principal brakes on adoption.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| FDA DSCSA / EU GDP compliance | Driver | High | Mandated traceability forces real-time record-keeping |
| Biologics & vaccine growth | Driver | High | Strict temperature windows raise monitoring intensity |
| Online grocery & pharma e-commerce | Driver | Medium-High | Last-mile cold delivery expands monitoring endpoints |
| IoT sensor cost decline | Driver | Medium | Lowers per-unit deployment barrier |
| High upfront hardware/software cost | Restraint | High | Deters SME adoption, especially in fragmented food chains |
| Emerging-market infrastructure gaps | Restraint | Medium | Power and connectivity reliability constrain uptime |
| Data integration complexity | Restraint | Medium | Legacy WMS/ERP integration slows deployment |
The balance favors growth: regulatory drivers are non-discretionary and recur annually, whereas cost restraints are one-time and declining. Our analysis suggests the binding constraint by 2027 will not be sensor cost but integration capability — the ability to fuse monitoring data into ERP and quality systems.
Competition splits into hardware-led incumbents with installed sensor bases and software-native challengers selling analytics and compliance layers, with consolidation increasingly favoring bundled hardware-plus-platform offers.
| Vendor | Primary strength | Strategic position |
|---|---|---|
| Carrier Global Corporation | Refrigeration + monitoring integration | Hardware-led incumbent |
| Emerson Electric Co. | Industrial monitoring & controls | Hardware-led incumbent |
| Sensitech (Carrier) | Data loggers, pharma cold chain | Specialist incumbent |
| Controlant | Cloud-native pharma monitoring | Software challenger |
| ORBCOMM | Telematics & asset tracking | Connectivity-led |
| ELPRO-BUCHS | Pharma-grade loggers | Specialist incumbent |
| Testo SE & Co. KGaA | Measurement instruments | Hardware specialist |
| Monnit Corporation | IoT sensor platforms | Low-cost challenger |
Differentiation is shifting from sensor accuracy (increasingly commoditized) toward compliance-grade audit trails, integration breadth, and predictive analytics. Moats built on installed hardware are durable but eroding; moats built on regulatory validation and data interoperability are compounding.
Procurement decisions should weight total cost of ownership and compliance defensibility over unit sensor price. The cheapest logger fleet frequently becomes the most expensive when audit trails, calibration records, and ERP integration are retrofitted later.
Mission-critical selection criteria include: validated temperature accuracy and calibration traceability; audit-ready reporting aligned to FDA DSCSA and EU GDP; API and ERP/WMS interoperability; connectivity resilience (cellular fallback, offline buffering); and vendor service-level commitments for alert escalation. Switching costs are high once sensors and dashboards are embedded in quality workflows, so buyers should negotiate data-portability and export rights upfront. Regulatory risk concentrates in documentation — a monitoring system that cannot produce an inspector-ready excursion report is a compliance liability, not an asset.
The balance of evidence favors a mid-teens-billion-dollar market growing at roughly 22% annually through the early 2030s, with the higher USD 116.8 billion terminal estimate being credible only if services and software attach rates expand as we expect. The strongest counter-argument is that hardware price deflation could compress revenue even as unit volumes rise — a real risk in food-logistics segments where sensor commoditization is fastest. We weight this risk as moderate, not decisive, because software and compliance services carry materially higher margins and are growing faster.
Our judgment: the strategic prize is the data and compliance layer, not the sensor. Vendors that bundle validated hardware with cloud analytics and audit-ready reporting will capture disproportionate value as pharma and e-commerce cold chains scale; pure hardware players face margin compression.
Actionable strategy:
What would change our conclusion: a sustained 30%+ annual decline in sensor pricing without offsetting software attach would compress market value toward the lower USD 52 billion trajectory, and would shift our recommendation toward services-only business models.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 22.5% from 2020-2034 |
| Segmentation |
|
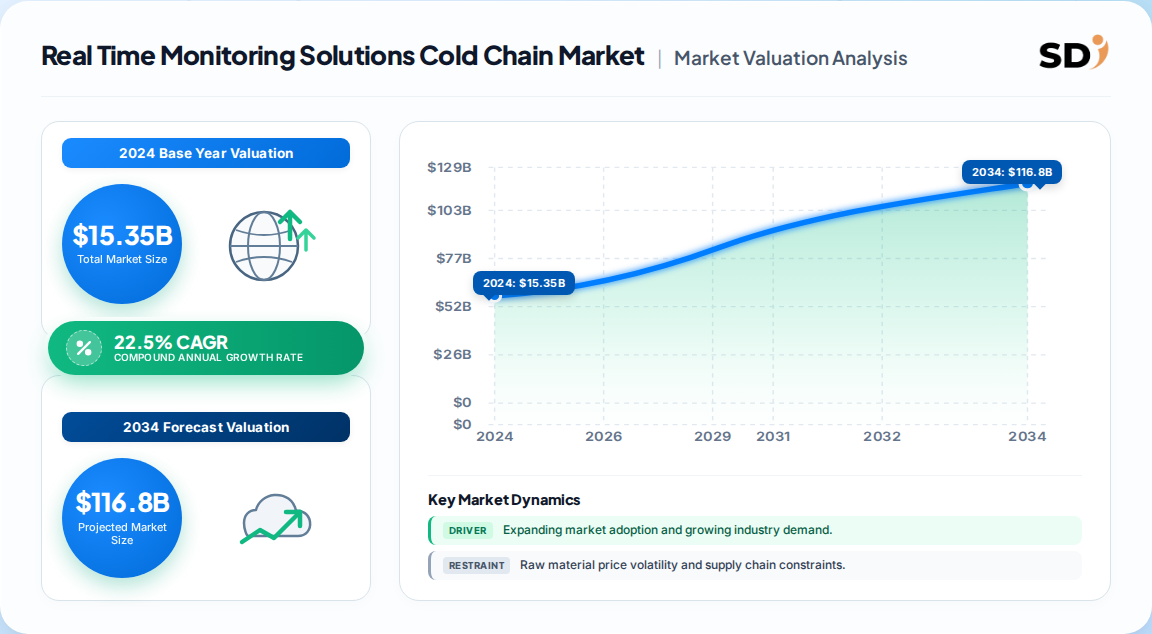
One published estimate values the market at USD 15.35 billion in 2024, growing to USD 116.8 billion by 2034. A competing analysis cites USD 12.4 billion in 2023, with the gap driven mainly by whether services and software are included.
Most estimates cluster around 22–23% CAGR. One forecast projects 22.5% through 2034, while a narrower tracking-and-monitoring definition projects 14.9% — the difference reflecting scope rather than demand fundamentals.
North America leads with roughly 34% revenue share, supported by FDA and USDA enforcement and mature logistics infrastructure. Asia-Pacific is the fastest-growing region as cold-chain capacity expands across China, India, and Southeast Asia.
Hardware holds the largest share at 64–76% depending on scope, driven by sensors, loggers, and GPS trackers. Software is the fastest-growing component at approximately 24.7% CAGR as cloud analytics and compliance reporting scale.
Key players include Carrier Global, Emerson Electric, Sensitech, Controlant, ORBCOMM, ELPRO-BUCHS, Testo, and Monnit. Hardware incumbents compete with software-native challengers offering cloud analytics and audit-ready compliance platforms.
Biologics and vaccines require strict temperature windows, and regulations such as FDA DSCSA and EU GDP mandate traceable records. Real-time monitoring prevents excursion losses and provides inspector-ready documentation, making it non-discretionary for pharma cold chains.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research program applies a 70/30 primary-to-secondary split. In-depth interviews were conducted with stakeholders across the cold-chain monitoring value chain: sensor and hardware manufacturers, cloud platform and software providers, contract calibration and validation specialists, and global logistics and distribution operators. Decision-maker designations interviewed included VP-level Sourcing and Procurement leads, Heads of Supply Chain Technology, Quality and Regulatory Affairs Directors, and Commercial Operations Leads responsible for cold-chain service contracts.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Supply Chain & Procurement Directors | 35% |
| Quality & Regulatory Affairs Leads | 30% |
| Technology & IT Operations Heads | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Sensor & Hardware Manufacturers | 40% |
| Cloud Platform & Software Providers | 30% |
| Logistics & Distribution Operators | 20% |
| Calibration & Validation Specialists | 10% |
Secondary validation draws on official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings and investor presentations (10-K, SEC filings), patent databases tracking sensor and IoT innovation, and recognized technical standards bodies including ISO and USP. Regulatory frameworks such as FDA DSCSA and EU GDP guidelines were reviewed directly to validate compliance-driven demand assumptions.
We apply simultaneous top-down and bottom-up triangulation. Top-down modeling allocates macroeconomic and vertical-industry spend across food, pharma, and chemical segments; bottom-up modeling builds from manufacturer unit shipments, pricing, and end-use consumption. Divergences between the two are reconciled against trade-flow and installed-base checks before a consensus estimate is finalized.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
