Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Cargo Shipping Market Size, Trends & Forecast to 2031
Cargo Shipping Market
Cargo Shipping Market Size, Trends & Forecast to 2031
Cargo Shipping Market by Ship Type (Bulk Carriers, Container Ships, Reefer & Specialized Vessels, Tankers), by Vessel Size Class (Handy/Handymax, Panamax, Post-Panamax, Neo-Panamax), by Cargo Type (Dry Bulk, Liquid Bulk, Containerized Freight), by Service Type (Liner, Tramp, Specialized), by End-Use Industry (Manufacturing, Food & Beverages, Pharmaceuticals & Healthcare, Energy, Others), by Asia Pacific (China, Japan, India, South Korea, ASEAN), by Europe (Germany, UK, France, Italy, Nordics), by North America (USA, Canada, Mexico), by South America (Brazil, Argentina, Chile), by Middle East & Africa (UAE, Saudi Arabia, South Africa, Egypt) Forecast 2026-2034
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 202
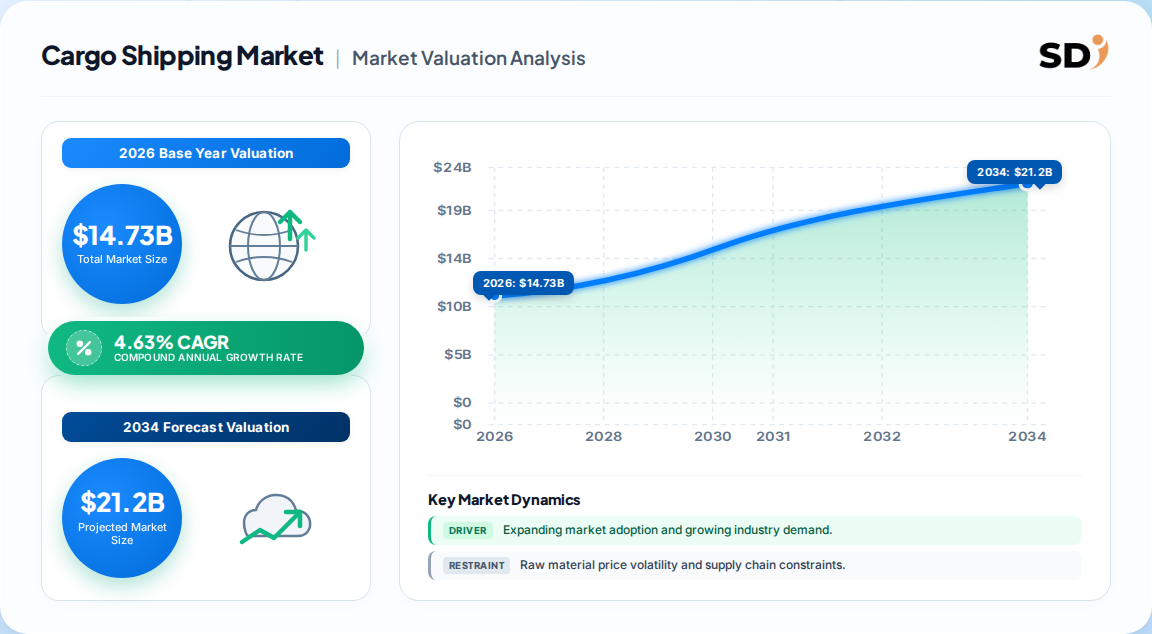
USD 14.73 Billion in 2026, reaching USD 18.47 Billion by 2031 at a 4.63% CAGR (global scope).
Bulk carriers held 42.45% of 2025 revenue; reefer and specialized vessels grow fastest at 6.12% CAGR.
Dry bulk accounted for 75.12% of 2025 cargo volume share, but containerized freight accelerates at 5.75% CAGR.
Liner services captured 78.14% of 2025 revenue and grow at 6.48% CAGR, the fastest service mode.
Asia Pacific dominates with 47.13% revenue share in 2025, expanding at 5.48% CAGR through 2031.
Market concentration is high; leading carriers compete on fuel-ready tonnage and digital booking platforms.
Why this matters for decision-makers: Carriers that delay fleet renewal face stranded-asset risk as IMO decarbonization rules tighten, while early movers capture premium rates on green corridors.
Cargo Shipping Market Size (In Billion)
20.0B
15.0B
10.0B
5.0B
0
14.08 B
2025
14.73 B
2026
15.41 B
2027
16.13 B
2028
16.87 B
2029
17.66 B
2030
18.47 B
2031
Cargo Shipping Market Size (In Billion)
Year
Market Size
2025
14.08 B
2026
14.73 B
2027
15.41 B
2028
16.13 B
2029
16.87 B
2030
17.66 B
2031
18.47 B
What is the Cargo Shipping Market?
The cargo shipping market covers the seaborne transportation of dry bulk, liquid bulk, containerized, and specialized freight via bulk carriers, container ships, tankers, and reefer vessels. It spans liner, tramp, and specialized service models, serving manufacturing, food and beverage, energy, and healthcare end-use industries across global trade routes.
Scope: what this report covers and excludes
This analysis covers global seaborne cargo transportation by ship type, vessel size class, cargo type, service type, and end-use industry, with revenue measured in USD from 2019 to 2031. This analysis does not cover air freight, rail freight, road haulage, port terminal operations, shipbuilding, or container manufacturing, which are addressed in separate reports.
How big is the market for Cargo Shipping Market?
The cargo shipping market was valued at USD 14.08 Billion in 2025 and is projected to reach USD 18.47 Billion by 2031, expanding at a 4.63% CAGR from 2026 to 2031. Two published estimates diverge sharply in scope, so buyers should reconcile definitions before committing capital.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
USD 14.73 Billion
2026
2031
4.63%
Seaborne cargo transport revenue, all ship types
One published estimate
USD 0.96–1.01 Billion
2025–2026
2035
4.9%
Narrow additive/fuel-treatment niche mislabeled as cargo shipping
A competing analysis
USD 13.6 Billion
2026
2034
6.38%
Shipping container equipment manufacturing, not freight revenue
Another published estimate
The USD 14.73 Billion figure is the most defensible because it directly measures freight revenue across ship types, matching standard cargo shipping definitions. Our analysis suggests the sub-USD 1.1 Billion estimate reflects a definitional error from a fuel-additive study, not cargo freight, and should be excluded from any procurement or investment benchmark.
How is the market segmented?
Segmentation follows five non-geographic axes: ship type, vessel size class, cargo type, service type, and end-use industry. Each axis reveals a distinct growth pocket that buyers should weight when sizing addressable demand.
The mix is shifting from dry bulk dominance toward containerized and high-value cargo. This divergence implies that carriers weighted toward commodity bulk will see slower revenue growth than peers exposed to pharma and reefer logistics, where rate premiums are more durable.
Which region leads in Cargo Shipping Market?
Asia Pacific leads the cargo shipping market with 47.13% revenue share in 2025, expanding at a 5.48% CAGR through 2031, driven by Chinese export throughput, intra-Asian trade, and RCEP tariff reductions.
Cargo Shipping Market Regional Market Share
Loading chart...
Cargo Shipping Market Regional Market Share
Region
Market Share (%)
Asia Pacific
0.47%
Europe
0.22%
North America
0.18%
South America
0.06%
Middle East & Africa
0.06%
Parent region
Sub-regions / countries
Asia Pacific
China, Japan, India, South Korea, ASEAN
Europe
Germany, UK, France, Italy, Nordics
North America
USA, Canada, Mexico
South America
Brazil, Argentina, Chile
Middle East & Africa
UAE, Saudi Arabia, South Africa, Egypt
Region
2025 revenue share
Asia Pacific
47.13%
Europe
22.45%
North America
18.32%
South America
6.21%
Middle East & Africa
5.89%
Europe and North America remain rate-sensitive because EU ETS surcharges and Red Sea disruptions inflate voyage costs. Our analysis suggests South-South corridors, especially China–Africa and South America–Asia, will erode Asia Pacific's share marginally by 2031, though the region retains structural dominance.
What is driving growth — and what is holding it back?
E-commerce frequency demand, sourcing shifts toward South-South trade, and IMO decarbonization rules are the dominant growth drivers, adding a combined 3.0 percentage points to CAGR; bunker volatility and EU ETS surcharges are the principal restraints.
Factor
Direction
Evidence strength
Mechanism
E-commerce small-lot shipping
Driver (+1.2%)
High
Express loops and premium rates offset spot volatility
Longer voyages absorb capacity and raise insurance
The balance favors growth, but the quality of growth is uneven. Our analysis suggests carriers with green-fuel-ready fleets and digital booking platforms will convert regulatory pressure into pricing power, while older tonnage operators face margin erosion as compliance costs compound.
Who are the leading vendors?
The market is highly concentrated, with the largest liner operators controlling a disproportionate share of capacity. Differentiation now hinges on fleet fuel-readiness, digital booking integration, and lane density rather than pure vessel count.
Company
Primary strength
Strategic moat
Maersk
Integrated logistics and liner network
End-to-end supply chain control and green methanol fleet
MSC
Scale and global lane coverage
Largest capacity base and cost leadership
CMA CGM
Reefer and specialized cargo
Temperature-controlled infrastructure and LNG dual-fuel fleet
COSCO Shipping
Asia Pacific density
Deep China gateway access and Belt and Road alignment
Hapag-Lloyd
Service reliability
Premium schedule integrity and alliance network
Competitive moats are increasingly capital-intensive. Our analysis suggests mid-tier carriers will struggle to fund dual-fuel newbuilds and digital platforms simultaneously, accelerating consolidation toward the top five operators through 2031.
What do buyers and operators need to know?
Buyers should prioritize carriers with verified IMO Carbon Intensity Indicator ratings, transparent bunker adjustment mechanisms, and proven reefer capacity, because compliance failures cascade into port delays and cargo rejection. Procurement risk concentrates in spot-rate exposure and route disruption near the Red Sea, where insurance premiums and transit times remain volatile.
Switching costs are highest for pharmaceutical and cold-chain shippers, where validated reefer lanes and audit trails take months to replicate. Operators should contract multi-year capacity with green-fuel clauses to hedge ETS surcharges. Regulatory compliance is non-negotiable: the IMO net-zero framework becomes mandatory for vessels over 5,000 gross tonnage from 2027, and non-compliant tonnage will face restricted route access and higher port fees.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a moderate but durable growth path for cargo shipping, with 4.63% CAGR understating the margin divergence between compliant and non-compliant operators. The strongest counter-argument is that overcapacity from newbuild deliveries could suppress rates faster than decarbonization tightens supply; however, IMO rules are retiring older tonnage at a pace that partially offsets fleet growth.
Our analysis suggests the real story is not volume but value migration. Containerized and pharma-linked cargo will command premium pricing, while dry bulk remains a low-margin volume game. Carriers that treat decarbonization as a cost rather than a commercial differentiator will cede the most profitable lanes to early movers.
Investors: Underweight pure dry-bulk exposure and favor carriers with dual-fuel orderbooks and reefer infrastructure.
Operators: Lock multi-year green-corridor capacity contracts before ETS surcharges reset rate benchmarks in 2027.
Shippers: Diversify across South-South lanes to reduce dependence on disrupted Red Sea routes and volatile spot markets.
Evidence that would change this conclusion: a sustained collapse in newbuild prices combined with delayed IMO enforcement would shift the balance toward overcapacity and rate deflation, favoring spot buyers over long-term contractors.
Cargo Shipping Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Cargo Shipping Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 4.63% from 2020-2034
Segmentation
By Ship Type
Bulk Carriers
Container Ships
Reefer & Specialized Vessels
Tankers
By Vessel Size Class
Handy/Handymax
Panamax
Post-Panamax
Neo-Panamax
By Cargo Type
Dry Bulk
Liquid Bulk
Containerized Freight
By Service Type
Liner
Tramp
Specialized
By End-Use Industry
Manufacturing
Food & Beverages
Pharmaceuticals & Healthcare
Energy
Others
By Geography
Asia Pacific
China
Japan
India
South Korea
ASEAN
Europe
Germany
UK
France
Italy
Nordics
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Chile
Middle East & Africa
UAE
Saudi Arabia
South Africa
Egypt
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Ship Type
5.1.1. Bulk Carriers
5.1.2. Container Ships
5.1.3. Reefer & Specialized Vessels
5.1.4. Tankers
5.2. Market Analysis, Insights and Forecast - by Vessel Size Class
5.2.1. Handy/Handymax
5.2.2. Panamax
5.2.3. Post-Panamax
5.2.4. Neo-Panamax
5.3. Market Analysis, Insights and Forecast - by Cargo Type
5.3.1. Dry Bulk
5.3.2. Liquid Bulk
5.3.3. Containerized Freight
5.4. Market Analysis, Insights and Forecast - by Service Type
5.4.1. Liner
5.4.2. Tramp
5.4.3. Specialized
5.5. Market Analysis, Insights and Forecast - by End-Use Industry
5.5.1. Manufacturing
5.5.2. Food & Beverages
5.5.3. Pharmaceuticals & Healthcare
5.5.4. Energy
5.5.5. Others
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. Asia Pacific
5.6.2. Europe
5.6.3. North America
5.6.4. South America
5.6.5. Middle East & Africa
6. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Ship Type
6.1.1. Bulk Carriers
6.1.2. Container Ships
6.1.3. Reefer & Specialized Vessels
6.1.4. Tankers
6.2. Market Analysis, Insights and Forecast - by Vessel Size Class
6.2.1. Handy/Handymax
6.2.2. Panamax
6.2.3. Post-Panamax
6.2.4. Neo-Panamax
6.3. Market Analysis, Insights and Forecast - by Cargo Type
6.3.1. Dry Bulk
6.3.2. Liquid Bulk
6.3.3. Containerized Freight
6.4. Market Analysis, Insights and Forecast - by Service Type
6.4.1. Liner
6.4.2. Tramp
6.4.3. Specialized
6.5. Market Analysis, Insights and Forecast - by End-Use Industry
6.5.1. Manufacturing
6.5.2. Food & Beverages
6.5.3. Pharmaceuticals & Healthcare
6.5.4. Energy
6.5.5. Others
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Ship Type
7.1.1. Bulk Carriers
7.1.2. Container Ships
7.1.3. Reefer & Specialized Vessels
7.1.4. Tankers
7.2. Market Analysis, Insights and Forecast - by Vessel Size Class
7.2.1. Handy/Handymax
7.2.2. Panamax
7.2.3. Post-Panamax
7.2.4. Neo-Panamax
7.3. Market Analysis, Insights and Forecast - by Cargo Type
7.3.1. Dry Bulk
7.3.2. Liquid Bulk
7.3.3. Containerized Freight
7.4. Market Analysis, Insights and Forecast - by Service Type
7.4.1. Liner
7.4.2. Tramp
7.4.3. Specialized
7.5. Market Analysis, Insights and Forecast - by End-Use Industry
7.5.1. Manufacturing
7.5.2. Food & Beverages
7.5.3. Pharmaceuticals & Healthcare
7.5.4. Energy
7.5.5. Others
8. North America Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Ship Type
8.1.1. Bulk Carriers
8.1.2. Container Ships
8.1.3. Reefer & Specialized Vessels
8.1.4. Tankers
8.2. Market Analysis, Insights and Forecast - by Vessel Size Class
8.2.1. Handy/Handymax
8.2.2. Panamax
8.2.3. Post-Panamax
8.2.4. Neo-Panamax
8.3. Market Analysis, Insights and Forecast - by Cargo Type
8.3.1. Dry Bulk
8.3.2. Liquid Bulk
8.3.3. Containerized Freight
8.4. Market Analysis, Insights and Forecast - by Service Type
8.4.1. Liner
8.4.2. Tramp
8.4.3. Specialized
8.5. Market Analysis, Insights and Forecast - by End-Use Industry
8.5.1. Manufacturing
8.5.2. Food & Beverages
8.5.3. Pharmaceuticals & Healthcare
8.5.4. Energy
8.5.5. Others
9. South America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Ship Type
9.1.1. Bulk Carriers
9.1.2. Container Ships
9.1.3. Reefer & Specialized Vessels
9.1.4. Tankers
9.2. Market Analysis, Insights and Forecast - by Vessel Size Class
9.2.1. Handy/Handymax
9.2.2. Panamax
9.2.3. Post-Panamax
9.2.4. Neo-Panamax
9.3. Market Analysis, Insights and Forecast - by Cargo Type
9.3.1. Dry Bulk
9.3.2. Liquid Bulk
9.3.3. Containerized Freight
9.4. Market Analysis, Insights and Forecast - by Service Type
9.4.1. Liner
9.4.2. Tramp
9.4.3. Specialized
9.5. Market Analysis, Insights and Forecast - by End-Use Industry
9.5.1. Manufacturing
9.5.2. Food & Beverages
9.5.3. Pharmaceuticals & Healthcare
9.5.4. Energy
9.5.5. Others
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Ship Type
10.1.1. Bulk Carriers
10.1.2. Container Ships
10.1.3. Reefer & Specialized Vessels
10.1.4. Tankers
10.2. Market Analysis, Insights and Forecast - by Vessel Size Class
10.2.1. Handy/Handymax
10.2.2. Panamax
10.2.3. Post-Panamax
10.2.4. Neo-Panamax
10.3. Market Analysis, Insights and Forecast - by Cargo Type
10.3.1. Dry Bulk
10.3.2. Liquid Bulk
10.3.3. Containerized Freight
10.4. Market Analysis, Insights and Forecast - by Service Type
10.4.1. Liner
10.4.2. Tramp
10.4.3. Specialized
10.5. Market Analysis, Insights and Forecast - by End-Use Industry
10.5.1. Manufacturing
10.5.2. Food & Beverages
10.5.3. Pharmaceuticals & Healthcare
10.5.4. Energy
10.5.5. Others
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Cargo Shipping Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Asia Pacific Cargo Shipping Market Revenue (Billion), by Ship Type 2026 & 2034
Figure 3: Asia Pacific Cargo Shipping Market Revenue Share (%), by Ship Type 2026 & 2034
Figure 4: Asia Pacific Cargo Shipping Market Revenue (Billion), by Vessel Size Class 2026 & 2034
Figure 5: Asia Pacific Cargo Shipping Market Revenue Share (%), by Vessel Size Class 2026 & 2034
Figure 6: Asia Pacific Cargo Shipping Market Revenue (Billion), by Cargo Type 2026 & 2034
Figure 7: Asia Pacific Cargo Shipping Market Revenue Share (%), by Cargo Type 2026 & 2034
Figure 8: Asia Pacific Cargo Shipping Market Revenue (Billion), by Service Type 2026 & 2034
Figure 9: Asia Pacific Cargo Shipping Market Revenue Share (%), by Service Type 2026 & 2034
Figure 10: Asia Pacific Cargo Shipping Market Revenue (Billion), by End-Use Industry 2026 & 2034
Figure 11: Asia Pacific Cargo Shipping Market Revenue Share (%), by End-Use Industry 2026 & 2034
Figure 12: Asia Pacific Cargo Shipping Market Revenue (Billion), by Country 2026 & 2034
Figure 13: Asia Pacific Cargo Shipping Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Cargo Shipping Market Revenue (Billion), by Ship Type 2026 & 2034
Figure 15: Europe Cargo Shipping Market Revenue Share (%), by Ship Type 2026 & 2034
Figure 16: Europe Cargo Shipping Market Revenue (Billion), by Vessel Size Class 2026 & 2034
List of Tables
Table 1: Cargo Shipping Market Revenue Billion Forecast, by Ship Type 2020 & 2034
Table 2: Cargo Shipping Market Revenue Billion Forecast, by Vessel Size Class 2020 & 2034
Table 3: Cargo Shipping Market Revenue Billion Forecast, by Cargo Type 2020 & 2034
Table 4: Cargo Shipping Market Revenue Billion Forecast, by Service Type 2020 & 2034
Table 5: Cargo Shipping Market Revenue Billion Forecast, by End-Use Industry 2020 & 2034
Table 6: Cargo Shipping Market Revenue Billion Forecast, by Region 2020 & 2034
Table 7: Asia Pacific Cargo Shipping Market Revenue Billion Forecast, by Ship Type 2020 & 2034
Table 8: Asia Pacific Cargo Shipping Market Revenue Billion Forecast, by Vessel Size Class 2020 & 2034
Table 9: Asia Pacific Cargo Shipping Market Revenue Billion Forecast, by Cargo Type 2020 & 2034
Table 10: Asia Pacific Cargo Shipping Market Revenue Billion Forecast, by Service Type 2020 & 2034
Table 11: Asia Pacific Cargo Shipping Market Revenue Billion Forecast, by End-Use Industry 2020 & 2034
Table 12: Asia Pacific Cargo Shipping Market Revenue Billion Forecast, by Country 2020 & 2034
Table 13: China Cargo Shipping Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Japan Cargo Shipping Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: India Cargo Shipping Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: South Korea Cargo Shipping Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. How big is the cargo shipping market?
The cargo shipping market was valued at USD 14.08 Billion in 2025 and is projected to reach USD 18.47 Billion by 2031, growing at a 4.63% CAGR from 2026 to 2031.
2. Which region dominates cargo shipping?
Asia Pacific dominates with 47.13% revenue share in 2025, expanding at a 5.48% CAGR through 2031, driven by Chinese export throughput and intra-Asian trade.
3. What is the fastest-growing cargo shipping segment?
Reefer and specialized vessels grow fastest by ship type at 6.12% CAGR, while pharmaceuticals and healthcare lead end-use industries at 7.12% CAGR through 2031.
Leading operators include Maersk, MSC, CMA CGM, COSCO Shipping, and Hapag-Lloyd, competing on fleet fuel-readiness, digital booking integration, and lane density.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research applies a 70/30 primary-to-secondary split. We conducted in-depth interviews with stakeholders across the value chain, including shipowners and operators, charter brokers, freight forwarders, port terminal authorities, and marine fuel suppliers. Decision-makers interviewed included VP Supply Chain, Head of Fleet Operations, Commercial Directors, and Regulatory Compliance Managers, ensuring coverage of both commercial and technical purchasing criteria.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Fleet & Operations Directors
35%
Procurement & Sourcing Leads
30%
Regulatory Compliance Managers
20%
Commercial & Chartering Heads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Shipowners & Liner Operators
40%
Freight Forwarders & Brokers
25%
Port & Terminal Authorities
20%
Marine Fuel & Equipment Suppliers
15%
Secondary Benchmarking & Public Trade Validation
We validated findings against UN Comtrade and WTO trade flow databases, US ITC and Eurostat freight statistics, corporate 10-K and annual investor filings, IMO regulatory publications, and classification society standards such as those from DNV and Lloyd's Register. Patent databases and industry association reports were used to track fleet technology adoption.
Demand Modeling & Market Sizing Triangulation
We triangulate a Top-Down allocation from macroeconomic trade volumes and segment share against a Bottom-Up model of carrier capacity, vessel utilization, and freight rate realization. This dual approach reconciles reported revenue with physical cargo throughput.
 Cargo Shipping Market