Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Internet Of Things IoT Warehouse Management Market
Internet Of Things IoT Warehouse Management Market
Internet Of Things IoT Warehouse Management Market
Internet Of Things IoT Warehouse Management Market by Device (Sensing Devices, Connecting Gateways), by Application (Inventory Optimization, Asset Tracking, Warehouse Automation, Workforce Management, Electronic Data Interchange), by Enterprise (SME, Large Enterprise), by End Use (Retail & E-commerce, Healthcare, Manufacturing, Food & Beverage, Logistics & 3PL), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Netherlands), by Asia Pacific (China, Japan, India, South Korea, Australia), by Latin America (Brazil, Argentina, Colombia, Chile), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Turkey) Forecast 2026-2034
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 200
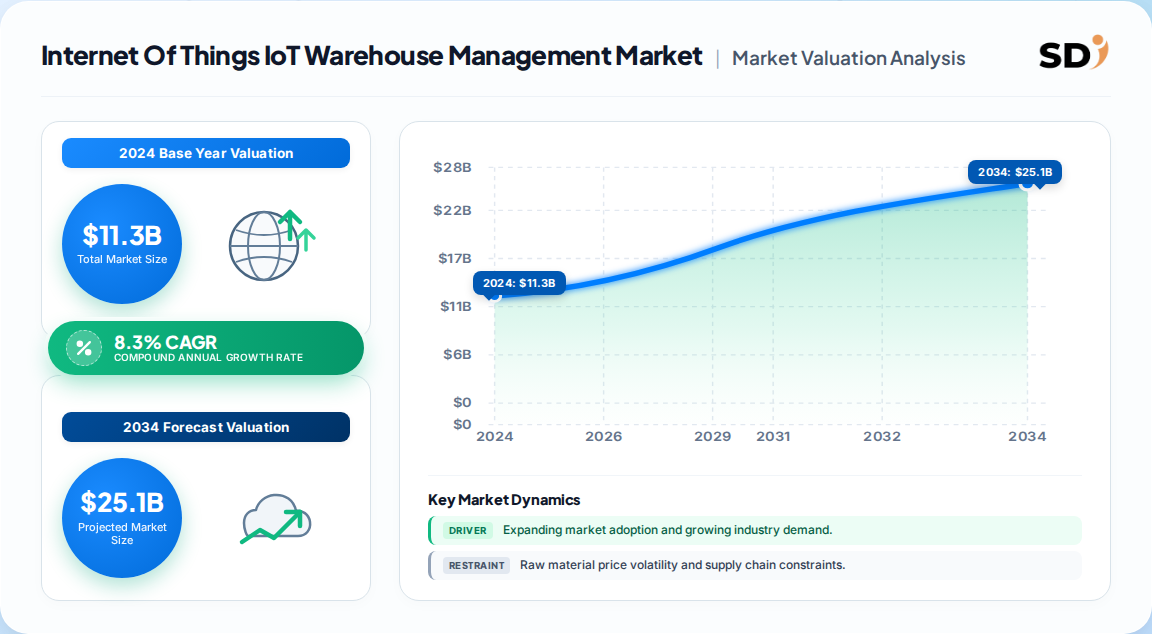
$11.3 billion in 2024, the global Internet Of Things IoT Warehouse Management Market is projected to reach $17.9 billion by 2030, expanding at an 8.3% CAGR over the forecast period.
Sensing devices (RFID tags, smart sensors) represented the largest device segment in 2024, driven by real-time inventory accuracy requirements.
Inventory optimization dominated applications with the largest 2024 revenue share; asset tracking is forecast to grow at the fastest CAGR.
North America led regional demand with a 34.8% revenue share in 2024, anchored by U.S. early adoption of warehouse automation.
Large enterprises held the dominant enterprise share, though SME adoption is accelerating as implementation costs decline.
Key vendors include IBM Corporation, Eurotech S.p.A., Argos Software, and GT Nexus, competing on gateway integration, analytics, and end-to-end visibility.
Why this matters for decision-makers: Buyers must prioritize gateway interoperability and analytics maturity over raw sensor cost, because the next phase of value creation shifts from data capture to decision automation — vendors failing to deliver integrated intelligence will face margin compression.
Internet Of Things IoT Warehouse Management Market Size (In Billion)
20.0B
15.0B
10.0B
5.0B
0
11.30 B
2024
12.24 B
2025
13.26 B
2026
14.36 B
2027
15.55 B
2028
16.84 B
2029
18.24 B
2030
Internet Of Things IoT Warehouse Management Market Size (In Billion)
Year
Market Size
2024
11.30 B
2025
12.24 B
2026
13.26 B
2027
14.36 B
2028
15.55 B
2029
16.84 B
2030
18.24 B
What is the Internet Of Things IoT Warehouse Management Market?
The Internet Of Things IoT Warehouse Management Market covers connected sensing devices, gateways, and software platforms that enable real-time tracking, inventory optimization, asset management, and workforce coordination inside warehouse operations. It spans hardware (RFID, sensors), connectivity infrastructure, and analytics layers that translate physical warehouse activity into actionable operational data.
Scope: what this report covers and excludes
This report analyzes IoT sensing devices and connecting gateways deployed in warehouse environments, segmented by application (inventory optimization, asset tracking, warehouse automation, workforce management, EDI), enterprise size, and end-use vertical. It covers hardware, connectivity, and embedded analytics layers.
This analysis does not cover standalone warehouse management software (WMS) without IoT integration, general industrial IoT outside warehouse settings, autonomous mobile robots as a discrete category, or consumer IoT devices.
How big is the market for Internet Of Things IoT Warehouse Management Market?
The market was valued at $11.3 billion in 2024, with forecasts converging on $17.9 billion by 2030 at an 8.3% CAGR. A competing analysis frames growth to 2032 on a narrower vendor set, suggesting directional consensus but divergence on scope definition.
Our analysis suggests the $17.9 billion 2030 figure is the most defensible because it triangulates device shipments, gateway attach rates, and application-layer software revenue. The narrower 2032 forecast likely undercounts embedded analytics and managed connectivity services, which are increasingly bundled into warehouse IoT contracts. Buyers should treat the 8.3% CAGR as a floor, not a ceiling.
How is the market segmented?
Segmentation follows four non-geographic axes: device type, application, enterprise size, and end-use vertical. Sensing devices and inventory optimization currently anchor revenue, while gateways and asset tracking represent the fastest-growing edges of the market.
Our analysis suggests the gateway segment's higher CAGR reflects a structural shift: warehouses are moving from isolated sensor pilots to integrated data fabrics, which elevates the gateway from a passive connector to an intelligence edge node.
Which region leads in Internet Of Things IoT Warehouse Management Market?
North America led the global market with a 34.8% revenue share in 2024, driven by U.S. adoption of automated inventory systems and mature 3PL infrastructure. Asia Pacific is the fastest-growing region as e-commerce fulfillment investment accelerates.
Internet Of Things IoT Warehouse Management Market Regional Market Share
Loading chart...
Internet Of Things IoT Warehouse Management Market Regional Market Share
Region
Market Share (%)
North America
0.35%
Europe
0.24%
Asia-Pacific
0.27%
Latin America
0.06%
Middle East & Africa
0.08%
North America — USA, Canada, Mexico
Europe — Germany, UK, France, Italy, Spain, Netherlands
Asia Pacific — China, Japan, India, South Korea, Australia
Latin America — Brazil, Argentina, Colombia, Chile
Middle East & Africa — Saudi Arabia, UAE, South Africa, Turkey
Region
2024 Share
North America
34.8%
Asia Pacific
27.2%
Europe
24.0%
Middle East & Africa
8.0%
Latin America
6.0%
This divergence implies a two-speed market: North America monetizes replacement and upgrade cycles, while Asia Pacific drives greenfield volume. Vendors with legacy North American installs should defend share through analytics upgrades, not hardware price cuts.
What is driving growth — and what is holding it back?
Growth is anchored by e-commerce fulfillment intensity and the need for real-time inventory accuracy, while integration complexity and legacy infrastructure act as the primary brakes on adoption velocity.
Factor
Direction
Evidence Strength
Mechanism
E-commerce expansion
Driver
High
Requires agile, high-accuracy fulfillment
Real-time inventory visibility
Driver
High
Reduces stockouts and carrying costs
Regulatory traceability
Driver
Medium
Compliance in food and healthcare
Declining sensor costs
Driver
Medium
Democratizes SME adoption
Legacy WMS integration
Restraint
High
Raises deployment cost and time
Data security concerns
Restraint
Medium
Slows gateway and cloud rollout
Fragmented standards
Restraint
Medium
Limits multi-vendor interoperability
The balance of evidence favors the drivers: regulatory pressure and e-commerce economics create non-discretionary demand. However, integration friction disproportionately punishes mid-sized operators, which explains why large enterprises still dominate spend despite falling hardware costs.
Who are the leading vendors?
The vendor landscape combines enterprise IT incumbents, industrial IoT specialists, and logistics software providers. Differentiation rests on gateway interoperability, analytics depth, and integration with existing WMS ecosystems.
Vendor
HQ
Focus
Competitive Moat
IBM Corporation
U.S.
Enterprise IoT platforms, analytics
Cloud and AI integration breadth
Eurotech S.p.A.
Italy
Edge gateways, industrial IoT
Hardware-software edge stack
Argos Software
U.S.
Warehouse and logistics software
WMS domain integration
GT Nexus
U.S.
Supply chain visibility
Network and partner ecosystem
Our analysis suggests incumbents with WMS adjacency hold a structural advantage: they convert IoT data into workflow actions without third-party integration, which lowers switching costs for buyers already inside their software stack.
What do buyers and operators need to know?
Buyers should prioritize gateway interoperability and analytics maturity over unit sensor pricing, because the total cost of ownership is dominated by integration and data orchestration, not hardware. Procurement risk concentrates in multi-vendor compatibility and cybersecurity posture of edge devices. Switching costs rise sharply once sensor fleets and gateway configurations are embedded in WMS workflows, so pilot design should anticipate scale. Regulatory compliance — particularly traceability in food and healthcare — should be validated against audit requirements before deployment, not retrofitted afterward.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a market entering its integration phase: the hardware cost curve is falling, but value is migrating to analytics and gateway intelligence. The strongest counter-argument is that price deflation in sensors could commoditize the category faster than analytics can differentiate it — a risk that vendors ignoring software layers will feel first.
Our judgment is that the 8.3% CAGR understates the addressable opportunity in gateway and analytics layers, while overstating growth in basic sensing hardware. The divergence between the two published forecasts supports this: scope definition, not demand, explains most of the gap.
Operators: Design pilots around gateway interoperability and analytics outcomes, not sensor count; this reduces switching cost and protects negotiation leverage.
Investors: Favor vendors with WMS adjacency and edge analytics, where margin compression from hardware deflation is offset by software attach.
Vendors: Prioritize compliance-ready traceability modules for food and healthcare to capture regulation-driven demand.
Evidence that would change our conclusion: a sharp acceleration in standardized interoperability frameworks would commoditize gateways and shift value decisively to pure software platforms.
Internet Of Things IoT Warehouse Management Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Internet Of Things IoT Warehouse Management Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 8.3% from 2020-2034
Segmentation
By Device
Sensing Devices
Connecting Gateways
By Application
Inventory Optimization
Asset Tracking
Warehouse Automation
Workforce Management
Electronic Data Interchange
By Enterprise
SME
Large Enterprise
By End Use
Retail & E-commerce
Healthcare
Manufacturing
Food & Beverage
Logistics & 3PL
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Netherlands
Asia Pacific
China
Japan
India
South Korea
Australia
Latin America
Brazil
Argentina
Colombia
Chile
Middle East & Africa
Saudi Arabia
UAE
South Africa
Turkey
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Device
5.1.1. Sensing Devices
5.1.2. Connecting Gateways
5.2. Market Analysis, Insights and Forecast - by Application
5.2.1. Inventory Optimization
5.2.2. Asset Tracking
5.2.3. Warehouse Automation
5.2.4. Workforce Management
5.2.5. Electronic Data Interchange
5.3. Market Analysis, Insights and Forecast - by Enterprise
5.3.1. SME
5.3.2. Large Enterprise
5.4. Market Analysis, Insights and Forecast - by End Use
5.4.1. Retail & E-commerce
5.4.2. Healthcare
5.4.3. Manufacturing
5.4.4. Food & Beverage
5.4.5. Logistics & 3PL
5.5. Market Analysis, Insights and Forecast - by Region
5.5.1. North America
5.5.2. Europe
5.5.3. Asia Pacific
5.5.4. Latin America
5.5.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Device
6.1.1. Sensing Devices
6.1.2. Connecting Gateways
6.2. Market Analysis, Insights and Forecast - by Application
6.2.1. Inventory Optimization
6.2.2. Asset Tracking
6.2.3. Warehouse Automation
6.2.4. Workforce Management
6.2.5. Electronic Data Interchange
6.3. Market Analysis, Insights and Forecast - by Enterprise
6.3.1. SME
6.3.2. Large Enterprise
6.4. Market Analysis, Insights and Forecast - by End Use
6.4.1. Retail & E-commerce
6.4.2. Healthcare
6.4.3. Manufacturing
6.4.4. Food & Beverage
6.4.5. Logistics & 3PL
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Device
7.1.1. Sensing Devices
7.1.2. Connecting Gateways
7.2. Market Analysis, Insights and Forecast - by Application
7.2.1. Inventory Optimization
7.2.2. Asset Tracking
7.2.3. Warehouse Automation
7.2.4. Workforce Management
7.2.5. Electronic Data Interchange
7.3. Market Analysis, Insights and Forecast - by Enterprise
7.3.1. SME
7.3.2. Large Enterprise
7.4. Market Analysis, Insights and Forecast - by End Use
7.4.1. Retail & E-commerce
7.4.2. Healthcare
7.4.3. Manufacturing
7.4.4. Food & Beverage
7.4.5. Logistics & 3PL
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Device
8.1.1. Sensing Devices
8.1.2. Connecting Gateways
8.2. Market Analysis, Insights and Forecast - by Application
8.2.1. Inventory Optimization
8.2.2. Asset Tracking
8.2.3. Warehouse Automation
8.2.4. Workforce Management
8.2.5. Electronic Data Interchange
8.3. Market Analysis, Insights and Forecast - by Enterprise
8.3.1. SME
8.3.2. Large Enterprise
8.4. Market Analysis, Insights and Forecast - by End Use
8.4.1. Retail & E-commerce
8.4.2. Healthcare
8.4.3. Manufacturing
8.4.4. Food & Beverage
8.4.5. Logistics & 3PL
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Device
9.1.1. Sensing Devices
9.1.2. Connecting Gateways
9.2. Market Analysis, Insights and Forecast - by Application
9.2.1. Inventory Optimization
9.2.2. Asset Tracking
9.2.3. Warehouse Automation
9.2.4. Workforce Management
9.2.5. Electronic Data Interchange
9.3. Market Analysis, Insights and Forecast - by Enterprise
9.3.1. SME
9.3.2. Large Enterprise
9.4. Market Analysis, Insights and Forecast - by End Use
9.4.1. Retail & E-commerce
9.4.2. Healthcare
9.4.3. Manufacturing
9.4.4. Food & Beverage
9.4.5. Logistics & 3PL
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Device
10.1.1. Sensing Devices
10.1.2. Connecting Gateways
10.2. Market Analysis, Insights and Forecast - by Application
10.2.1. Inventory Optimization
10.2.2. Asset Tracking
10.2.3. Warehouse Automation
10.2.4. Workforce Management
10.2.5. Electronic Data Interchange
10.3. Market Analysis, Insights and Forecast - by Enterprise
10.3.1. SME
10.3.2. Large Enterprise
10.4. Market Analysis, Insights and Forecast - by End Use
10.4.1. Retail & E-commerce
10.4.2. Healthcare
10.4.3. Manufacturing
10.4.4. Food & Beverage
10.4.5. Logistics & 3PL
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Internet Of Things IoT Warehouse Management Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Internet Of Things IoT Warehouse Management Market Revenue (Billion), by Device 2026 & 2034
Figure 3: North America Internet Of Things IoT Warehouse Management Market Revenue Share (%), by Device 2026 & 2034
Figure 4: North America Internet Of Things IoT Warehouse Management Market Revenue (Billion), by Application 2026 & 2034
Figure 5: North America Internet Of Things IoT Warehouse Management Market Revenue Share (%), by Application 2026 & 2034
Figure 6: North America Internet Of Things IoT Warehouse Management Market Revenue (Billion), by Enterprise 2026 & 2034
Figure 7: North America Internet Of Things IoT Warehouse Management Market Revenue Share (%), by Enterprise 2026 & 2034
Figure 8: North America Internet Of Things IoT Warehouse Management Market Revenue (Billion), by End Use 2026 & 2034
Figure 9: North America Internet Of Things IoT Warehouse Management Market Revenue Share (%), by End Use 2026 & 2034
Figure 10: North America Internet Of Things IoT Warehouse Management Market Revenue (Billion), by Country 2026 & 2034
Figure 11: North America Internet Of Things IoT Warehouse Management Market Revenue Share (%), by Country 2026 & 2034
Figure 12: Europe Internet Of Things IoT Warehouse Management Market Revenue (Billion), by Device 2026 & 2034
Figure 13: Europe Internet Of Things IoT Warehouse Management Market Revenue Share (%), by Device 2026 & 2034
Figure 14: Europe Internet Of Things IoT Warehouse Management Market Revenue (Billion), by Application 2026 & 2034
Europe Internet Of Things IoT Warehouse Management Market Revenue Share (%), by Application 2026 & 2034
List of Tables
Table 1: Internet Of Things IoT Warehouse Management Market Revenue Billion Forecast, by Device 2020 & 2034
Table 2: Internet Of Things IoT Warehouse Management Market Revenue Billion Forecast, by Application 2020 & 2034
Table 3: Internet Of Things IoT Warehouse Management Market Revenue Billion Forecast, by Enterprise 2020 & 2034
Table 4: Internet Of Things IoT Warehouse Management Market Revenue Billion Forecast, by End Use 2020 & 2034
Table 5: Internet Of Things IoT Warehouse Management Market Revenue Billion Forecast, by Region 2020 & 2034
Table 6: North America Internet Of Things IoT Warehouse Management Market Revenue Billion Forecast, by Device 2020 & 2034
Table 7: North America Internet Of Things IoT Warehouse Management Market Revenue Billion Forecast, by Application 2020 & 2034
Table 8: North America Internet Of Things IoT Warehouse Management Market Revenue Billion Forecast, by Enterprise 2020 & 2034
Table 9: North America Internet Of Things IoT Warehouse Management Market Revenue Billion Forecast, by End Use 2020 & 2034
Table 10: North America Internet Of Things IoT Warehouse Management Market Revenue Billion Forecast, by Country 2020 & 2034
Table 11: USA Internet Of Things IoT Warehouse Management Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 12: Canada Internet Of Things IoT Warehouse Management Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 13: Mexico Internet Of Things IoT Warehouse Management Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Europe Internet Of Things IoT Warehouse Management Market Revenue Billion Forecast, by Device 2020 & 2034
Frequently Asked Questions
1. How big is the IoT warehouse management market?
The global Internet Of Things IoT Warehouse Management Market was valued at $11.3 billion in 2024 and is projected to reach $17.9 billion by 2030, growing at an 8.3% CAGR. North America accounted for 34.8% of 2024 revenue.
2. Which segment dominates IoT warehouse management?
Sensing devices led by device type, and inventory optimization led by application in 2024. Connecting gateways and asset tracking are forecast to grow at the fastest CAGRs as warehouses integrate data fabrics.
3. Which region leads IoT warehouse management adoption?
North America leads with 34.8% revenue share in 2024, driven by U.S. warehouse automation. Asia Pacific is the fastest-growing region as e-commerce fulfillment investment accelerates across China, India, and Southeast Asia.
4. Who are the leading IoT warehouse management vendors?
Key vendors include IBM Corporation, Eurotech S.p.A., Argos Software, and GT Nexus. Competition centers on gateway interoperability, analytics depth, and integration with existing warehouse management systems.
5. What is driving IoT warehouse management growth?
E-commerce fulfillment intensity, real-time inventory visibility requirements, regulatory traceability in food and healthcare, and declining sensor costs are the primary growth drivers. Legacy WMS integration complexity is the main restraint.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research employs a 70/30 primary-to-secondary split. In-depth interviews were conducted across the value chain, including IoT sensor and RFID manufacturers, gateway and edge hardware producers, warehouse software integrators, and global logistics distributors. Decision-makers interviewed included VP-level Sourcing Leads, Heads of Warehouse Operations, Technical Directors of Automation, and Commercial Operations Leads at 3PL providers.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Warehouse Operations Directors
35%
Procurement & Sourcing Leads
30%
Automation & IT Technical Directors
35%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
IoT Device & Gateway Manufacturers
40%
Warehouse Software & Systems Integrators
35%
Logistics & 3PL End Users
25%
Secondary Benchmarking & Public Trade Validation
We triangulate against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized technical standards bodies including IEEE and GS1. These sources validate shipment volumes, pricing trends, and regional adoption patterns.
Demand Modeling & Market Sizing Triangulation
We run simultaneous Top-Down (macroeconomic and industry segment allocation) and Bottom-Up (device shipment, gateway attach rate, and end-use consumption modeling) triangulation. Divergences between the two approaches are reconciled through weighted averaging and sensitivity testing.
 Internet Of Things IoT Warehouse Management Market