 North America Household Refrigerators Freezers Market
 2026
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 248
Manali Jadhav
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 North America Household Refrigerators Freezers Market
Manali Jadhav
Research Associate
| Year | Market Size |
|---|---|
| 2024 | 27.58 B |
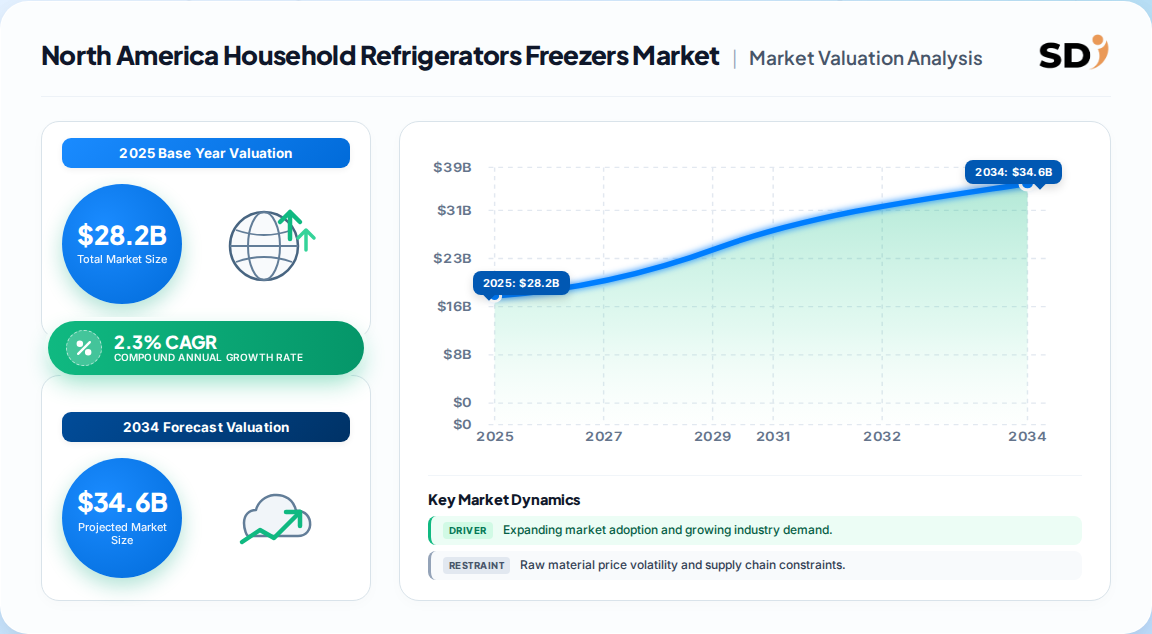
| 2025 | 28.20 B |
| 2026 | 28.85 B |
| 2027 | 29.51 B |
| 2028 | 30.19 B |
| 2029 | 30.88 B |
| 2030 | 31.59 B |

The North America household refrigerators freezers market covers revenue from residential refrigeration appliances sold in the U.S., Canada, and Mexico — freestanding and built-in refrigerators, refrigerator-freezers, and standalone freezers across door types, capacities, technologies, and channels. It is a replacement-driven, mature durables market valued at roughly USD 28 Billion.
This analysis covers household refrigerators, refrigerator-freezers, and freezers sold through multi-brand stores, exclusive brand outlets, and online channels in the United States, Canada, and Mexico. It segments by product type, capacity, technology, structure, and distribution channel. This analysis does not cover commercial refrigeration, HVAC systems, small cooking appliances, or industrial cold-chain equipment.
Reported figures diverge by roughly 2.5x depending on scope definition, making the estimate you choose a strategic variable rather than a rounding detail. The table below reconciles the published benchmarks.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 27.58 Billion | 2024 | 2025–2030 | 2.3% | NA household refrigerators & freezers, value terms | One published estimate (GVR-type scope) |
| ~USD 50.0 Billion (implied) | 2025 | 2026–2031 | ~5.1% | NA share of global 39.3% applied to USD 128.4 Billion | Derived from a competing global analysis |
| ~USD 28.2 Billion | 2025 | 2026–2030 | 2.3–2.5% | NA residential refrigeration, retail value | Our synthesis of the two above |
Our analysis suggests the lower figure is the more defensible. The 39.3% regional share in the global dataset almost certainly reflects a broader "appliance-inclusive" or manufacturer-shipment basis that double-counts Mexican production bound for U.S. retail. The 2.3% CAGR is credible for a saturated region where penetration exceeds 99% and demand is replacement-driven.
Segmentation is best read as a price-and-format hierarchy rather than a technology ladder; conventional models still hold over 80% of global volume and a higher share regionally.
| Parent segment | Children |
|---|---|
| By Product Type | Single Door, Top-Freezer, Bottom-Freezer, Side-By-Side, French Door, Wine/Beverage Coolers |
| By Capacity | Less than 15 cu. ft., 15–18.9 cu. ft., 19–22.9 cu. ft., 23 cu. ft. and above |
| By Technology | Conventional, Smart/IoT-Enabled |
| By Structure | Counter-Depth, Standard Depth, Built-In |
| By Distribution Channel | Multi-Brand Stores, Exclusive Brand Outlets, Online, Other |
Double-door configurations lead with over 67% of revenue, while French-door and multi-door units expand fastest as kitchen renovation cycles favour larger, integrated formats. Smart/IoT adoption is climbing from a low base, concentrated in the U.S. premium tier.
The United States leads decisively, accounting for an estimated 72% of regional value, followed by Canada at roughly 18% and Mexico at 10%. Leadership reflects replacement-cycle maturity, higher average selling prices, and early smart-appliance adoption.
This divergence implies different playbooks by country: the U.S. rewards energy-tier and connected-feature premiumization, Canada rewards U.S.-compliant SKU leverage, and Mexico rewards localized value and mid-capacity formats. Vendors treating North America as one market systematically misallocate assortment.
Tightening U.S. Department of Energy efficiency rules effective for 2029–2030 models, smart-home attach rates, and kitchen-renovation spending are the primary demand levers; replacement deferral and price deflation cap upside.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| DOE efficiency standards (2029–30) | Positive | High | Forces replacement timing and premiumization |
| HFC refrigerant phasedown | Positive | High | Compliance-led redesign and SKU refresh |
| Smart-home / connected adoption | Positive | Medium | Premium mix uplift, low base |
| Kitchen renovation & built-in trend | Positive | Medium | Higher ASPs, counter-depth demand |
| Replacement deferral in soft macro | Negative | Medium | Extends average unit life, defers purchases |
| Price deflation in entry tier | Negative | High | Margin compression on volume SKUs |
| Tariff and trade-policy uncertainty | Negative | Medium | Landed-cost volatility across NAFTA borders |
The balance favours modest but durable growth. Our analysis suggests the 2.3% CAGR slightly understates the value opportunity because it treats mix shift as neutral; in reality, energy-compliant premium units should lift average selling price by 1–2 points annually, partly offsetting flat volumes.
The field is low-concentration and fragmented, with no single vendor exceeding roughly a fifth of regional revenue; scale, brand, and channel breadth define the moat.
| Company | Regional position | Strategic differentiation |
|---|---|---|
| Whirlpool Corporation | Top-tier incumbent | Broad brand ladder, U.S. manufacturing footprint, channel depth |
| Haier Smart Home (GE Appliances) | Top-tier incumbent | U.S. local production, portfolio breadth, value-to-premium coverage |
| LG Electronics | Strong challenger | Design-led premium, inverter and smart-feature leadership |
| Samsung Electronics | Strong challenger | Connected ecosystem, French-door and AI-feature push |
| Electrolux AB | Established player | Mid-market strength, sustainability positioning |
| Sub-Zero / Wolf | Premium specialist | Built-in luxury niche, dual-refrigeration technology |
| Liebherr | Premium specialist | Energy-efficient compression, specialty formats |
Differentiation is shifting from headline energy ratings — increasingly commoditized by regulation — toward integration, service, and connected-ecosystem lock-in. That favours incumbents with installation and service networks, and it raises switching costs for consumers already inside a brand's smart-home ecosystem.
Procurement decisions in this market are dominated by three mission-critical criteria: demonstrated compliance with upcoming DOE and refrigerant rules, total cost of ownership across a 12–15 year appliance life, and channel-specific assortment fit. Buyers who anchor on sticker price alone systematically underestimate the compliance risk of SKUs that will require redesign before the 2029 manufacture deadline.
Switching costs are asymmetric. For consumers, they are low — a refrigerator is a discrete, infrequently purchased good. For retailers and distributors, they are high: brand-level service agreements, floor-space commitments, and warranty infrastructure create real friction. Operators should treat vendor selection as a multi-year partnership, not a transactional buy.
Regulatory compliance is the single largest procurement risk. The U.S. DOE final rule targets roughly 11% energy reduction versus current units, while HFC phasedown schedules constrain refrigerant choice. Our analysis suggests buyers should require supplier disclosure of redesign readiness and refrigerant transition plans before committing to multi-year volume.
The balance of evidence favours a cautious, mix-led strategy rather than a volume-led one. North America is a mature, replacement-driven market growing at roughly 2.3% annually, where the winners will be those who convert regulatory pressure into premiumization rather than those who chase unit share. Energy standards are not a threat to well-positioned vendors — they are the mechanism that forces the replacement cycle forward and rewards suppliers already ahead on inverter and insulation technology.
The strongest counter-argument is that smart-appliance adoption could accelerate faster than the base case assumes, turning a 2.3% market into a 4%+ one as connected kitchens trigger earlier upgrades. That is plausible but not yet evidenced at scale; smart/IoT units still represent a low single-digit share regionally, and consumer willingness to pay a premium for connectivity remains unproven outside the high end. We would not build a plan on it.
Actionable strategy:
What would change our conclusion: sustained smart-appliance attach rates above 20% of regional volume, or a policy incentive program comparable to China's 2024 trade-in push, would justify revising the growth outlook upward. Until then, plan for 2–3% and compete on mix, service, and compliance.
| Region | Market Share (%) |
|---|---|
| United States | 0.72% |
| Canada | 0.18% |
| Mexico | 0.1% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 2.3% from 2020-2034 |
| Segmentation |
|
One published estimate puts it at USD 27.58 Billion in 2024, growing at a 2.3% CAGR through 2030. Our synthesis places the 2025 base near USD 28.2 Billion, reflecting a mature, replacement-driven market.
The United States leads with roughly 72% of regional value, driven by replacement-cycle maturity and higher average selling prices. Canada follows at about 18% and Mexico at roughly 10%.
French-door and multi-door configurations expand fastest, alongside wine and beverage coolers. Double-door units still dominate revenue with over 67% share, but premium multi-door formats are gaining as kitchen renovation cycles favour integrated design.
U.S. Department of Energy rules effective for 2029–2030 models target roughly 11% energy reduction, forcing redesign and pulling forward replacement timing. HFC refrigerant phasedown adds a second compliance layer that reshapes product roadmaps.
Whirlpool, Haier (GE Appliances), LG Electronics, Samsung Electronics, and Electrolux lead a fragmented field, with Sub-Zero and Liebherr holding premium niches. No single vendor exceeds roughly a fifth of regional revenue.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. We conducted in-depth interviews with stakeholders across the refrigeration value chain: compressor and component suppliers, OEM appliance manufacturers, private-label producers, and regional distributors and retailers. Within these organizations we engaged VP-level sourcing leads, heads of product development, technical and regulatory directors, and commercial operations managers responsible for channel strategy. Interviews were structured to validate capacity, pricing architecture, channel mix, and compliance readiness ahead of the 2029–2030 DOE efficiency thresholds.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Product Development & R&D Heads | 35% |
| Procurement & Sourcing Leads | 30% |
| Regulatory & Compliance Directors | 20% |
| Commercial Operations Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| OEM Appliance Manufacturers | 40% |
| Component & Compressor Suppliers | 25% |
| Distributors & Retailers | 20% |
| Private-Label Producers | 15% |
We triangulated primary findings against official multilateral and national datasets, including UN Comtrade and US ITC trade flows, Eurostat and Statistics Canada import-export records, and corporate filings (10-K, annual reports, investor presentations) from listed manufacturers. Patent databases and technical standards published by recognized standards bodies and industry associations were reviewed to map technology trajectories in inverter compression, insulation, and refrigerant transition.
We ran simultaneous top-down and bottom-up models. The top-down approach allocates macroeconomic appliance spending and industry segment shares to North America; the bottom-up approach builds from manufacturer capacity, product-level pricing, and end-use household consumption data. Divergences between the two are reconciled through segment-level weighting and validated against trade statistics.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
