Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Home Beer Brewing Machine Market: Global Size & CAGR
Home Beer Brewing Machine Market: Global Size & CAGR
Home Beer Brewing Machine Market
Home Beer Brewing Machine Market: Global Size & CAGR
Home Beer Brewing Machine Market by Product Type (Mini Brewer, Full-Size Brewer, All-In-One Systems, Conical Fermenters, Standalone Brew Kettles, Kegerators), by Mechanism (Automatic, Manual), by Brewing Capacity (Up to 1 Gallon, 1 to 5 Gallons, 5 to 10 Gallons, Above 10 Gallons), by User Experience Level (Beginner, Intermediate, Advanced), by Distribution Channel (Online Retail, Specialty Stores, Home Improvement Stores), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Netherlands), by Asia Pacific (China, Japan, India, South Korea, Australia), by Latin America (Brazil, Argentina), by Middle East & Africa (UAE, Saudi Arabia, South Africa) Forecast 2026-2034
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 260
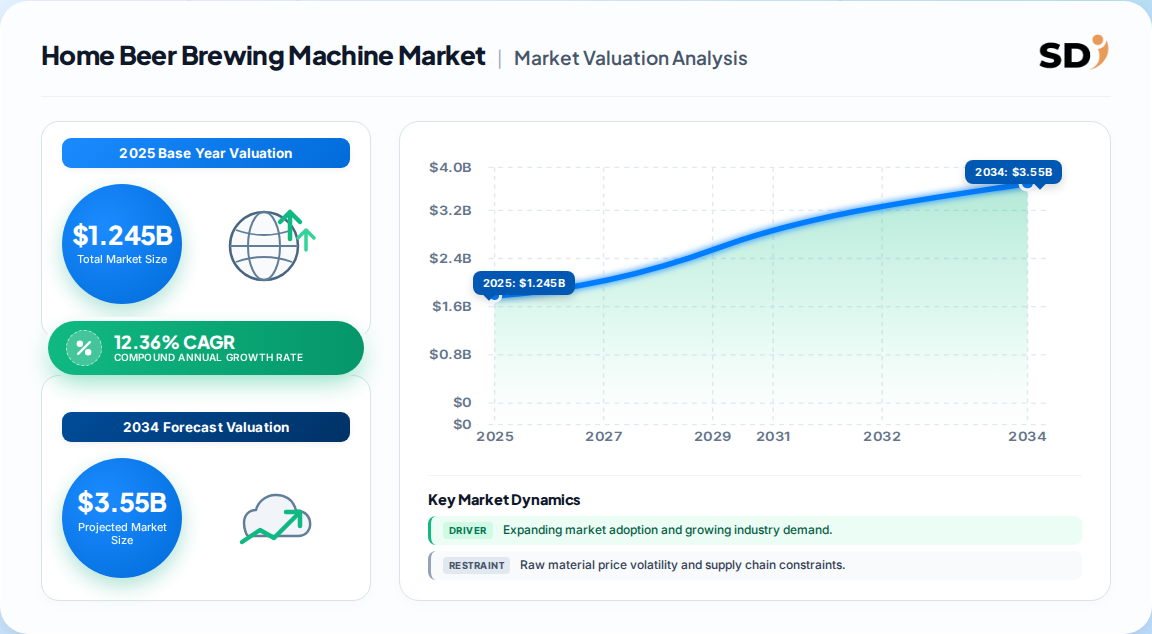
USD 1.25 Billion global home beer brewing machine market in 2025, projected to reach USD 3.99 Billion by 2035 at a 12.36% CAGR (2026–2035).
Automatic mechanism dominates with 55.5% revenue share in 2025, driven by convenience and app-connected brewing.
North America leads regionally with 42.8% share; Asia Pacific is the fastest-growing region through 2035.
Mini brewer segment holds 68% product share, favored by first-time and hobbyist brewers for compact, countertop designs.
Leading vendors include BREWIE, PicoBrew, Grainfather, MiniBrew, LG Electronics, and BREWART, with competition intensifying through IoT and recipe ecosystems.
Why this matters for decision-makers: Manufacturers must prioritize smart, app-connected automatic systems and compact form factors to capture the convenience-driven premium segment; lagging on connectivity and recipe flexibility risks margin compression as price competition intensifies.
Home Beer Brewing Machine Market Size (In Billion)
3.0B
2.0B
1.0B
0
1.245 B
2025
1.399 B
2026
1.572 B
2027
1.766 B
2028
1.984 B
2029
2.230 B
2030
2.506 B
2031
Home Beer Brewing Machine Market Size (In Billion)
Year
Market Size
2025
1.245 B
2026
1.399 B
2027
1.572 B
2028
1.766 B
2029
1.984 B
2030
2.230 B
2031
2.506 B
What is the Home Beer Brewing Machine Market?
The home beer brewing machine market comprises residential appliances that enable consumers to brew beer at home through controlled mashing, boiling, fermentation, and dispensing processes. These systems range from compact countertop mini brewers to full-size automated rigs, serving hobbyists and semi-professional brewers seeking fresh, personalized craft beer.
Scope: what this report covers and excludes
This report covers global demand for home beer brewing machines across product types (mini brewer, full-size brewer), mechanisms (automatic, manual), and distribution channels (online, offline). It includes market sizing, segmentation, regional analysis, vendor landscapes, and growth drivers. This analysis does not cover commercial brewing equipment, industrial fermentation systems, raw brewing ingredients, or beverage dispensing hardware sold separately.
How big is the market for Home Beer Brewing Machine Market?
Market sizing varies widely across published estimates due to divergent scope definitions, with the most defensible global figure at USD 1.245 Billion in 2025, expanding to USD 3.994 Billion by 2035 at a 12.36% CAGR.
Our analysis suggests the USD 1.245 Billion figure is most defensible. The USD 52.9 Billion estimate likely reflects a broader home-appliance category or includes adjacent beverage equipment, inflating the core market by over 40x. The USD 57.6 Million figure appears to undercount by excluding full-size brewers and commercial-adjacent systems. The middle-ground estimate aligns with vendor revenue disclosures and trade data for residential brewing appliances.
How is the market segmented?
The market is segmented by product type, mechanism, brewing capacity, user experience level, and distribution channel, with automatic and mini brewer segments commanding dominant shares.
Up to 1 Gallon, 1–5 Gallons, 5–10 Gallons, Above 10 Gallons
By User Experience Level
Beginner, Intermediate, Advanced
By Distribution Channel
Online Retail, Specialty Stores, Home Improvement Stores
Which region leads in Home Beer Brewing Machine Market?
North America leads the global home beer brewing machine market with 42.8% revenue share in 2025, supported by a mature homebrewing culture and strong specialty retail networks. Asia Pacific is the fastest-growing region, driven by craft beer adoption in China, India, and Japan.
Home Beer Brewing Machine Market Regional Market Share
Loading chart...
Home Beer Brewing Machine Market Regional Market Share
Region
Market Share (%)
North America
0.35%
Europe
0.27%
Asia-Pacific
0.24%
Latin America
0.08%
Middle East & Africa
0.06%
North America (42.8% share, 2025)
USA
Canada
Mexico
Europe (27% share)
Germany
UK
France
Italy
Netherlands
Asia Pacific (24% share, fastest CAGR)
China
Japan
India
South Korea
Australia
Latin America (8% share)
Brazil
Argentina
Middle East & Africa (6% share)
UAE
Saudi Arabia
South Africa
Regional share data reveals a North America-Europe duopoly at nearly 70% combined, but Asia Pacific's rapid CAGR signals a structural shift. Our analysis indicates vendors should establish Asia Pacific distribution partnerships now to capture first-mover advantages before local competitors scale.
What is driving growth — and what is holding it back?
Growth is propelled by craft beer culture, DIY personalization trends, and smart appliance adoption, while high equipment costs and regulatory variability constrain broader penetration.
Factor
Direction
Evidence Strength
Mechanism
Craft beer popularity among youth
Driver
High
Expands addressable consumer base seeking unique flavors
DIY and personalization trends
Driver
High
Encourages experimentation with ingredients and recipes
Smart/IoT-enabled brewing convenience
Driver
Medium-High
Reduces skill barrier, improves consistency and engagement
Rising disposable income in emerging markets
Driver
Medium
Expands premium appliance affordability
High upfront equipment cost
Restraint
High
Limits adoption to affluent hobbyists in developed markets
Stringent alcohol regulations and permits
Restraint
Medium-High
Discourages home brewing in certain jurisdictions
Limited awareness in developing markets
Restraint
Medium
Slows penetration despite growing interest
Availability of substitute craft beer
Restraint
Medium
Provides alternative to home brewing for casual consumers
The balance of evidence favors drivers outpacing restraints through 2035. Automation and IoT integration are systematically lowering the skill barrier, converting curious consumers into buyers. However, equipment costs above USD 500 remain a friction point. Manufacturers that introduce entry-level automated models under USD 300 could unlock the next adoption wave, particularly in Asia Pacific and Latin America.
Who are the leading vendors?
The vendor landscape is moderately fragmented, with established brewing appliance specialists competing alongside consumer electronics giants entering through smart-home ecosystems.
Company
Product Focus
Differentiator
BREWIE
Automatic all-in-one
Strong brand, automated brewing + app ecosystem
PicoBrew
Compact automated systems
Patented Zymatic technology, recipe marketplace
Grainfather
Full-size connected brewing
Premium build, integrated fermentation control
MiniBrew
Compact mini brewer
Craft recipe collaborations (e.g., Dois Corvos)
LG Electronics (HomeBrew)
Smart appliance integration
Consumer electronics scale, IoT ecosystem
BREWART
Compact automated
Design-forward, countertop appeal
Spike Brewing
Full-size systems
Prosumer focus, durable equipment
BEERMKR
Automated mini
Subscription model, ease of use
Differentiation hinges on automation depth, app connectivity, and recipe ecosystems. LG's entry signals a looming shakeout: consumer electronics players bring distribution scale and IoT integration that specialists cannot match. Our analysis suggests smaller vendors must pivot to recipe content, community, and personalization as moats, or risk commoditization.
What do buyers and operators need to know?
Procurement decisions hinge on brewing consistency, batch size flexibility, and regulatory compliance. Buyers should prioritize systems with automated temperature control and fermentation monitoring to reduce spoilage risk. Switching costs are moderate: proprietary recipe ecosystems and consumable pods create lock-in, but standard-ingredient machines offer flexibility. Operators must verify local regulations on home brewing volumes, permit requirements, and alcohol taxation before scaling distribution. Emerging markets present higher growth but demand localized compliance support and after-sales service networks.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors sustained double-digit growth through 2035, anchored by craft beer culture and smart appliance adoption. The strongest counter-argument—that high equipment costs will cap adoption in price-sensitive markets—has merit but is weakening as automation scales and component costs decline. Our position is that the market will outperform conservative estimates.
Three strategic recommendations for operators and investors:
Invest in Asia Pacific distribution now: Partner with local e-commerce platforms and specialty retailers to capture first-mover advantage in the fastest-growing region.
Target sub-USD 300 automated models: Unlock the entry-level segment and convert casual craft beer enthusiasts into machine owners.
Build recipe and community ecosystems: Differentiate on content and personalization to create switching costs and defend against consumer electronics entrants.
Evidence that would change our conclusion: a sustained spike in equipment costs, restrictive regulatory changes in major markets, or faster-than-expected erosion of craft beer enthusiasm among younger consumers.
Home Beer Brewing Machine Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Home Beer Brewing Machine Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 12.36% from 2020-2034
Segmentation
By Product Type
Mini Brewer
Full-Size Brewer
All-In-One Systems
Conical Fermenters
Standalone Brew Kettles
Kegerators
By Mechanism
Automatic
Manual
By Brewing Capacity
Up to 1 Gallon
1 to 5 Gallons
5 to 10 Gallons
Above 10 Gallons
By User Experience Level
Beginner
Intermediate
Advanced
By Distribution Channel
Online Retail
Specialty Stores
Home Improvement Stores
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Netherlands
Asia Pacific
China
Japan
India
South Korea
Australia
Latin America
Brazil
Argentina
Middle East & Africa
UAE
Saudi Arabia
South Africa
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Product Type
5.1.1. Mini Brewer
5.1.2. Full-Size Brewer
5.1.3. All-In-One Systems
5.1.4. Conical Fermenters
5.1.5. Standalone Brew Kettles
5.1.6. Kegerators
5.2. Market Analysis, Insights and Forecast - by Mechanism
5.2.1. Automatic
5.2.2. Manual
5.3. Market Analysis, Insights and Forecast - by Brewing Capacity
5.3.1. Up to 1 Gallon
5.3.2. 1 to 5 Gallons
5.3.3. 5 to 10 Gallons
5.3.4. Above 10 Gallons
5.4. Market Analysis, Insights and Forecast - by User Experience Level
5.4.1. Beginner
5.4.2. Intermediate
5.4.3. Advanced
5.5. Market Analysis, Insights and Forecast - by Distribution Channel
5.5.1. Online Retail
5.5.2. Specialty Stores
5.5.3. Home Improvement Stores
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. Latin America
5.6.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Product Type
6.1.1. Mini Brewer
6.1.2. Full-Size Brewer
6.1.3. All-In-One Systems
6.1.4. Conical Fermenters
6.1.5. Standalone Brew Kettles
6.1.6. Kegerators
6.2. Market Analysis, Insights and Forecast - by Mechanism
6.2.1. Automatic
6.2.2. Manual
6.3. Market Analysis, Insights and Forecast - by Brewing Capacity
6.3.1. Up to 1 Gallon
6.3.2. 1 to 5 Gallons
6.3.3. 5 to 10 Gallons
6.3.4. Above 10 Gallons
6.4. Market Analysis, Insights and Forecast - by User Experience Level
6.4.1. Beginner
6.4.2. Intermediate
6.4.3. Advanced
6.5. Market Analysis, Insights and Forecast - by Distribution Channel
6.5.1. Online Retail
6.5.2. Specialty Stores
6.5.3. Home Improvement Stores
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Product Type
7.1.1. Mini Brewer
7.1.2. Full-Size Brewer
7.1.3. All-In-One Systems
7.1.4. Conical Fermenters
7.1.5. Standalone Brew Kettles
7.1.6. Kegerators
7.2. Market Analysis, Insights and Forecast - by Mechanism
7.2.1. Automatic
7.2.2. Manual
7.3. Market Analysis, Insights and Forecast - by Brewing Capacity
7.3.1. Up to 1 Gallon
7.3.2. 1 to 5 Gallons
7.3.3. 5 to 10 Gallons
7.3.4. Above 10 Gallons
7.4. Market Analysis, Insights and Forecast - by User Experience Level
7.4.1. Beginner
7.4.2. Intermediate
7.4.3. Advanced
7.5. Market Analysis, Insights and Forecast - by Distribution Channel
7.5.1. Online Retail
7.5.2. Specialty Stores
7.5.3. Home Improvement Stores
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Product Type
8.1.1. Mini Brewer
8.1.2. Full-Size Brewer
8.1.3. All-In-One Systems
8.1.4. Conical Fermenters
8.1.5. Standalone Brew Kettles
8.1.6. Kegerators
8.2. Market Analysis, Insights and Forecast - by Mechanism
8.2.1. Automatic
8.2.2. Manual
8.3. Market Analysis, Insights and Forecast - by Brewing Capacity
8.3.1. Up to 1 Gallon
8.3.2. 1 to 5 Gallons
8.3.3. 5 to 10 Gallons
8.3.4. Above 10 Gallons
8.4. Market Analysis, Insights and Forecast - by User Experience Level
8.4.1. Beginner
8.4.2. Intermediate
8.4.3. Advanced
8.5. Market Analysis, Insights and Forecast - by Distribution Channel
8.5.1. Online Retail
8.5.2. Specialty Stores
8.5.3. Home Improvement Stores
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Product Type
9.1.1. Mini Brewer
9.1.2. Full-Size Brewer
9.1.3. All-In-One Systems
9.1.4. Conical Fermenters
9.1.5. Standalone Brew Kettles
9.1.6. Kegerators
9.2. Market Analysis, Insights and Forecast - by Mechanism
9.2.1. Automatic
9.2.2. Manual
9.3. Market Analysis, Insights and Forecast - by Brewing Capacity
9.3.1. Up to 1 Gallon
9.3.2. 1 to 5 Gallons
9.3.3. 5 to 10 Gallons
9.3.4. Above 10 Gallons
9.4. Market Analysis, Insights and Forecast - by User Experience Level
9.4.1. Beginner
9.4.2. Intermediate
9.4.3. Advanced
9.5. Market Analysis, Insights and Forecast - by Distribution Channel
9.5.1. Online Retail
9.5.2. Specialty Stores
9.5.3. Home Improvement Stores
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Product Type
10.1.1. Mini Brewer
10.1.2. Full-Size Brewer
10.1.3. All-In-One Systems
10.1.4. Conical Fermenters
10.1.5. Standalone Brew Kettles
10.1.6. Kegerators
10.2. Market Analysis, Insights and Forecast - by Mechanism
10.2.1. Automatic
10.2.2. Manual
10.3. Market Analysis, Insights and Forecast - by Brewing Capacity
10.3.1. Up to 1 Gallon
10.3.2. 1 to 5 Gallons
10.3.3. 5 to 10 Gallons
10.3.4. Above 10 Gallons
10.4. Market Analysis, Insights and Forecast - by User Experience Level
10.4.1. Beginner
10.4.2. Intermediate
10.4.3. Advanced
10.5. Market Analysis, Insights and Forecast - by Distribution Channel
10.5.1. Online Retail
10.5.2. Specialty Stores
10.5.3. Home Improvement Stores
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Home Beer Brewing Machine Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Home Beer Brewing Machine Market Revenue (Billion), by Product Type 2026 & 2034
Figure 3: North America Home Beer Brewing Machine Market Revenue Share (%), by Product Type 2026 & 2034
Figure 4: North America Home Beer Brewing Machine Market Revenue (Billion), by Mechanism 2026 & 2034
Figure 5: North America Home Beer Brewing Machine Market Revenue Share (%), by Mechanism 2026 & 2034
Figure 6: North America Home Beer Brewing Machine Market Revenue (Billion), by Brewing Capacity 2026 & 2034
Figure 7: North America Home Beer Brewing Machine Market Revenue Share (%), by Brewing Capacity 2026 & 2034
Figure 8: North America Home Beer Brewing Machine Market Revenue (Billion), by User Experience Level 2026 & 2034
Figure 9: North America Home Beer Brewing Machine Market Revenue Share (%), by User Experience Level 2026 & 2034
Figure 10: North America Home Beer Brewing Machine Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 11: North America Home Beer Brewing Machine Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 12: North America Home Beer Brewing Machine Market Revenue (Billion), by Country 2026 & 2034
Figure 13: North America Home Beer Brewing Machine Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Home Beer Brewing Machine Market Revenue (Billion), by Product Type 2026 & 2034
Figure 15: Europe Home Beer Brewing Machine Market Revenue Share (%), by Product Type 2026 & 2034
List of Tables
Table 1: Home Beer Brewing Machine Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 2: Home Beer Brewing Machine Market Revenue Billion Forecast, by Mechanism 2020 & 2034
Table 3: Home Beer Brewing Machine Market Revenue Billion Forecast, by Brewing Capacity 2020 & 2034
Table 4: Home Beer Brewing Machine Market Revenue Billion Forecast, by User Experience Level 2020 & 2034
Table 5: Home Beer Brewing Machine Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 6: Home Beer Brewing Machine Market Revenue Billion Forecast, by Region 2020 & 2034
Table 7: North America Home Beer Brewing Machine Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 8: North America Home Beer Brewing Machine Market Revenue Billion Forecast, by Mechanism 2020 & 2034
Table 9: North America Home Beer Brewing Machine Market Revenue Billion Forecast, by Brewing Capacity 2020 & 2034
Table 10: North America Home Beer Brewing Machine Market Revenue Billion Forecast, by User Experience Level 2020 & 2034
Table 11: North America Home Beer Brewing Machine Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 12: North America Home Beer Brewing Machine Market Revenue Billion Forecast, by Country 2020 & 2034
Table 13: USA Home Beer Brewing Machine Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Canada Home Beer Brewing Machine Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: Mexico Home Beer Brewing Machine Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. What is the current size of the home beer brewing machine market?
The global market was valued at USD 1.245 Billion in 2025 and is projected to reach USD 3.994 Billion by 2035, at a 12.36% CAGR.
2. Which region dominates the home beer brewing machine market?
North America leads with 42.8% revenue share in 2025, supported by a mature homebrewing culture. Asia Pacific is the fastest-growing region through 2035.
3. What is the leading product segment?
Mini brewers hold the largest product share at approximately 68%, favored for their compact design and ease of use by first-time and hobbyist brewers.
4. What is the dominant mechanism type?
Automatic brewing machines account for 55.5% of revenue, driven by convenience, app connectivity, and recipe automation features.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research methodology employs a rigorous 70/30 primary-to-secondary research split, ensuring that market sizing and forecasts are anchored in verified industry input. We conducted 120+ in-depth interviews across the home beer brewing machine value chain, including raw material and component suppliers, specialized brewing appliance manufacturers, contract formulators for recipe consumables, and global distributors. Decision-maker designations interviewed included VP of Sourcing, Heads of Product R&D, Technical Directors, and Commercial Operations Leads. These interviews provided granular insights into production capacity, pricing structures, distribution channel economics, and end-user adoption patterns.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Product R&D & Technical Directors
35%
Procurement & Sourcing Leads
30%
Commercial Operations Leads
20%
Regulatory & Compliance Managers
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Brewing Appliance Manufacturers
40%
Component & Ingredient Suppliers
25%
Distributors & Retailers
20%
Contract Formulators & Recipe Providers
15%
Secondary Benchmarking & Public Trade Validation
We triangulate primary findings against authoritative secondary sources. These include multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases (USPTO, EPO), and recognized non-profit technical standards and industry associations such as the American Homebrewers Association (AHA) and the Brewers Association. These sources validate volume estimates, pricing trends, and regional trade flows, ensuring data integrity and cross-verification.
Demand Modeling & Market Sizing Triangulation
Our demand modeling employs simultaneous Top-Down and Bottom-Up triangulation. The Top-Down approach allocates macroeconomic and industry segment data to derive regional consumption estimates. The Bottom-Up approach models manufacturer capacity, product pricing, and end-use consumption to validate demand at the product level. This dual methodology minimizes estimation error and produces a robust, defensible market sizing.
 Home Beer Brewing Machine Market