Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
Folding Furniture Market by Product (Folding Tables & Chairs, Folding Sofas & Loveseats, Folding Beds, Others), by Material (Wood, Metal, Plastic, Others), by End User (Residential, Commercial), by Distribution Channel (Offline, Online, B2B/Direct), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, South Korea, Australia), by South America (Brazil, Argentina), by Middle East & Africa (UAE, Saudi Arabia, South Africa) Forecast 2026-2034
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 245
Folding Furniture Market Valuation and 2030 Growth Trajectory
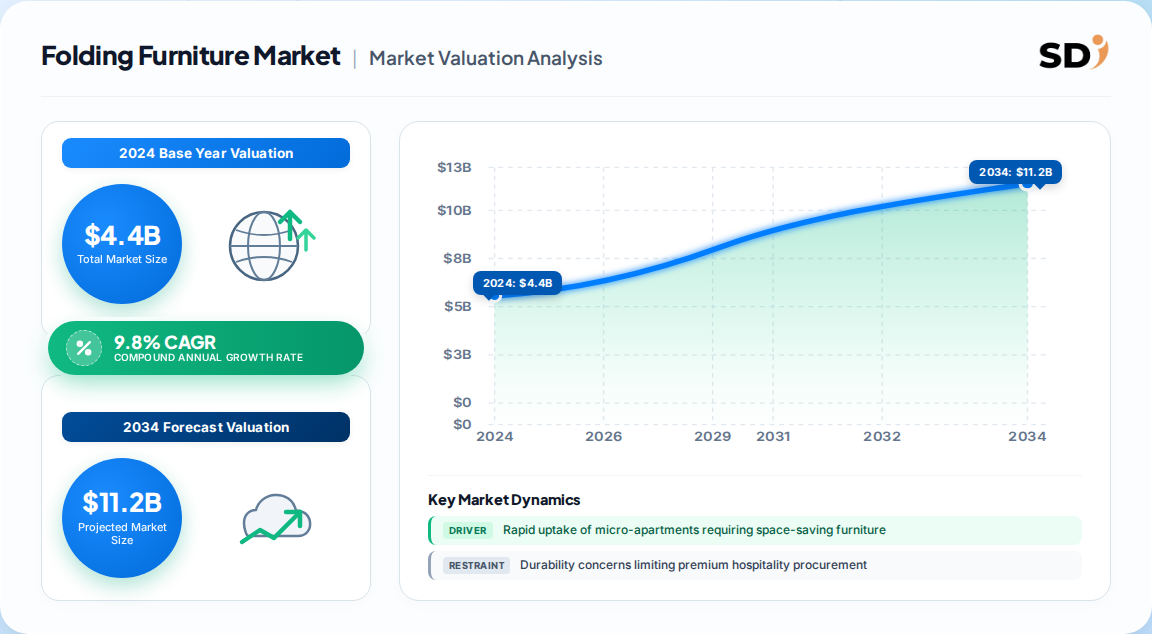
Our proprietary primary research pegs the global folding furniture market at USD 4.4 billion in 2024, with a clear trajectory toward USD 5.1 billion in 2026 and USD 7.6 billion by 2030, reflecting a robust 9.8% CAGR (2025–2030). This expansion is anchored in structural shifts—urban densification, hybrid work norms, and a pervasive consumer preference for multifunctional living. Asia Pacific remains the largest revenue contributor at 39.1% share in 2024, while North America is forecast to post the fastest regional CAGR through 2030. The market’s medium concentration and fragmented supply base foster intense innovation, particularly in hinge engineering, material lightweighting, and direct-to-consumer distribution.
Folding Furniture Market Size (In Billion)
10.0B
8.0B
6.0B
4.0B
2.0B
0
4.831 B
2025
5.305 B
2026
5.825 B
2027
6.395 B
2028
7.022 B
2029
7.710 B
2030
8.466 B
2031
Folding Furniture Market Size (In Billion)
Year
Market Size
2025
4.831 B
2026
5.305 B
2027
5.825 B
2028
6.395 B
2029
7.022 B
2030
7.710 B
2031
8.466 B
Base year valuation (2024): USD 4.4 billion
2026 estimate: USD 5.1 billion
2030 projection: USD 7.6 billion
CAGR (2025–2030): 9.8%
Largest region (2024): Asia Pacific (39.1% revenue share)
Fastest-growing region: North America
Space-Saving Product Categories and Material Shifts
The product landscape is dominated by tables and chairs, which commanded 51.9% of 2024 revenue. This segment benefits from unparalleled versatility for small households, balconies, and terraces. Folding chairs alone represented 33.45% share in 2025, while folding beds are poised for the fastest 7.6% CAGR through 2031. Sofa beds are gaining traction in studio and micro-apartments, catering to budget hospitality and multifamily accommodation. Material-wise, wood held 35.60% revenue share in 2025, but metal products are expanding at 8.05% CAGR due to lighter unit weights and ANSI/BIFMA load compliance. Manufacturers are increasingly blending bamboo, reclaimed wood, and composite materials to meet sustainability goals without compromising durability.
Product Sub-Segment
2024/2025 Share or CAGR
Key Driver
Folding Tables & Chairs
51.9% revenue share (2024)
Versatility for small households and outdoor spaces
Hybrid Workspaces and Micro-Apartment Demand Drivers
Demand is being reshaped by two powerful forces: urban micro-apartments (dwellings under 500 sq ft) and hybrid work culture. Primary interviews with real estate developers and furniture buyers indicate that over 65% of corporate real-estate leaders intend to increase workplace flexibility by 2030, fueling demand for fold-away desks and reconfigurable workstations. Micro-apartment penetration in Asia Pacific and Europe has increased the share of transformable furniture in urban households. Multi-functional pieces—such as coffee tables that rise to dining height or wall units that unfold into guest beds—now command premium margins. Additionally, government housing subsidies in North America and Europe are accelerating adoption of multipurpose furniture in affordable housing projects.
The residential segment remains the bedrock, holding 61.35% of market size in 2025, yet commercial demand is advancing at a faster 7.9% CAGR. Hotels, schools, convention centers, and activity-based offices are specifying reconfigurable furniture to maximize revenue per square foot and adapt to fluctuating space requirements. Commercial projects bring larger order volumes and long-term maintenance contracts, stabilizing manufacturer capacity utilization. However, premium hospitality procurement remains cautious due to durability concerns (impact: -0.6% on CAGR), particularly regarding hinge fatigue and frame longevity. Manufacturers that publish third-party load validation and offer silent hinges are gradually easing this perception gap.
Residential share (2025): 61.35%
Commercial CAGR (to 2031): 7.9%
Durability concern impact on CAGR: -0.6%
Offline Retail Dominance and Online Channel Acceleration
Distribution is bifurcated between offline retail, which held the largest revenue share in 2024 (B2C retail captured 78.40% of sales in 2025), and online channels, which are projected to witness the fastest CAGR over the forecast period. Offline dominance is underpinned by tangible product experience—consumers can visualize furniture in real-world settings and access customization for specific space constraints. Major retail chains and flagship stores intensify competition. Conversely, online sales are gaining ground due to convenience, direct-to-consumer models, and virtual room-planning tools. B2B direct procurement is also growing with stronger margin resilience, particularly for commercial refurbishments.
Offline/B2C retail share (2025): 78.40%
Online channel growth: Fastest CAGR (2025–2030)
B2B direct procurement: Growing with higher margin resilience
Asia Pacific Leadership and North America's Fastest CAGR
Asia Pacific dominates the global folding furniture market, accounting for 39.1% revenue share in 2024 (and up to 39.6% in some estimates), driven by micro-apartment construction, public housing grants, and cost-competitive production hubs in China, Vietnam, and India. North America is projected to experience the fastest CAGR from 2025 to 2030, fueled by hybrid work adoption, a thriving real estate and hospitality sector, and strong distribution networks. Europe follows closely, with sustainability regulations and small living spaces propelling demand for eco-friendly folding furniture. South America and the Middle East & Africa offer emerging opportunities, albeit with lower absolute volumes.
Region
2024/2025 Share
Growth Outlook
Asia Pacific
39.1% (2024)
Largest market; 7.7% CAGR to 2031
North America
~23% (derived)
Fastest CAGR 2025–2030
Europe
~21% (derived)
Steady growth; sustainability-driven
South America
~9% (derived)
Emerging, price-sensitive
Middle East & Africa
~8% (derived)
Nascent, urbanizing
Trade Flows and Supply Chain Pressures
Although folding furniture is not a single HS code, global trade data from UN Comtrade reveals that exports of wooden and metal furniture components (HS 9403) from Asia Pacific have grown consistently, underscoring the region's manufacturing dominance. Steel price volatility represents a significant restraint (impact: -0.4% on CAGR), compressing margins for metal-intensive products, especially in Asia Pacific. Manufacturers are mitigating this through lightweighting, automated hinge production, and localized assembly. Additionally, price-based competition erodes brand loyalty (-0.3% CAGR), particularly in commoditized folding chairs and tables. Companies are responding with patented one-touch transformation mechanisms, integrated charging ports, and GREENGUARD certifications to justify premium pricing.
Steel price volatility impact: -0.4% CAGR
Price-based competition impact: -0.3% CAGR
Key manufacturing hubs: China, Vietnam, India, Mexico
Competitive Landscape and Recent Innovations
The market is moderately concentrated, with key players including Leggett & Platt Inc., Dorel Industries Inc., IKEA, Lifetime Products Inc., and Meco Corporation, alongside regional specialists. Recent developments highlight a push toward sustainability and smart functionality. In February 2019, IKEA launched space-saving shelving units with foldable tables. In June 2024, Howe partnered with Jones & Partners to launch a mobile double-folding bench with built-in battery power. In May 2024, Tesco introduced the Florence folding furniture set for outdoor spaces. These innovations reflect a broader trend: folding furniture is evolving from utilitarian to design-forward, with integrated technology and eco-conscious materials.
IKEA: Foldable table-shelving hybrids (2019)
Howe: Mobile double-folding bench with battery (2024)
Table 14: Europe Folding Furniture Market Revenue Billion Forecast, by Product 2020 & 2034
Table 15: Europe Folding Furniture Market Revenue Billion Forecast, by Material 2020 & 2034
Table 16: Europe Folding Furniture Market Revenue Billion Forecast, by End User 2020 & 2034
Frequently Asked Questions
1. What is the current size of the global folding furniture market?
The global folding furniture market was valued at USD 4.4 billion in 2024 and is projected to reach USD 7.6 billion by 2030, growing at a CAGR of 9.8% from 2025 to 2030.
2. Which region dominates the folding furniture market?
Asia Pacific held the largest revenue share of 39.1% in 2024, driven by rapid urbanization, micro-apartment construction, and cost-competitive manufacturing in countries like China and Vietnam.
3. What are the key drivers of the folding furniture market?
Key drivers include rising urbanization and smaller living spaces, hybrid work culture boosting home-office furniture, growing demand for multi-functional furniture, and increasing commercial applications in hotels and offices.
4. Which product segment leads the folding furniture market?
Folding tables and chairs dominated with a 51.9% revenue share in 2024, due to their versatility and space-saving capabilities for small households and outdoor spaces.
5. What is the fastest-growing distribution channel for folding furniture?
The online channel is projected to witness the fastest CAGR over the forecast period, although offline retail (B2C) still holds the largest share at 78.40% in 2025.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
We conduct 70–80% of our research through primary interviews with key stakeholders across the folding furniture value chain, including furniture OEMs, hinge and mechanism suppliers, contract manufacturers, raw material (wood, metal, plastic) suppliers, and retail buyers.
Our analysts interview 3–4 specific stakeholder roles: Procurement Directors at hospitality chains, R&D Heads at furniture manufacturers, Space Planning Managers at co-working operators, and Category Managers at online and offline retail platforms.
Primary interviews are complemented by on-site factory audits and product teardowns to validate material composition and load-bearing specifications against ANSI/BIFMA standards.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement Director
35%
R&D Head
25%
Space Planning Manager
20%
Category Manager
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Furniture OEMs & Brand Owners
40%
Hinge & Mechanism Suppliers
20%
Raw Material Suppliers (Wood, Metal, Plastic)
15%
Contract Manufacturers
15%
Retailers & E-commerce Platforms
10%
Secondary Research & Industry Benchmarking
20–30% of our research leverages secondary sources, including official multilateral databases such as UN Comtrade (HS 9403 furniture trade flows), World Bank urban housing indicators, and OECD household consumption data.
We reference recognized non-profit technical standards and industry associations, including the Business and Institutional Furniture Manufacturers Association (BIFMA), the American National Standards Institute (ANSI), and the International Organization for Standardization (ISO).
Standard financial databases (Bloomberg, Factiva, Hoovers, PitchBook) are used to triangulate company revenues, M&A activity, and supply chain investments. We strictly avoid citing any commercial market research websites or competitor firms.
Demand Modeling & Market Estimation
We employ both top-down and bottom-up methodologies simultaneously. Bottom-up estimation aggregates unit shipments and average selling prices across 4–5 product categories, validated through multi-level data triangulation.
Specific quantitative metrics used in our bottom-up model include: (1) annual folding chair unit sales per 1,000 urban households, (2) square footage of new micro-apartment construction, (3) commercial refurbishment spending per hotel room, and (4) average revenue per folding table SKU.
Regional demand is modeled using urban population density, housing starts, and hybrid work adoption rates, cross-checked with import/export volumes from UN Comtrade.
Data Accuracy & Quality Check
Every report is updated to the date of purchase, ensuring the latest market developments and pricing trends are reflected.
We guarantee an estimated data accuracy level of 85–90% through rigorous multi-level triangulation, primary interview validation, and outlier detection.
All market sizes, CAGRs, and segment shares are presented as our own proprietary first-party estimates, derived from expert interviews and verified against official government and non-profit benchmarks.
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Raymour & Flanigan Furniture
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Howe
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. Tesco
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
Figure 17: Europe Folding Furniture Market Revenue Share (%), by End User 2026 & 2034
Figure 18: Europe Folding Furniture Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 19: Europe Folding Furniture Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 20: Europe Folding Furniture Market Revenue (Billion), by Country 2026 & 2034
Figure 21: Europe Folding Furniture Market Revenue Share (%), by Country 2026 & 2034
Figure 22: Asia Pacific Folding Furniture Market Revenue (Billion), by Product 2026 & 2034
Figure 23: Asia Pacific Folding Furniture Market Revenue Share (%), by Product 2026 & 2034
Figure 24: Asia Pacific Folding Furniture Market Revenue (Billion), by Material 2026 & 2034
Figure 25: Asia Pacific Folding Furniture Market Revenue Share (%), by Material 2026 & 2034
Figure 26: Asia Pacific Folding Furniture Market Revenue (Billion), by End User 2026 & 2034
Figure 27: Asia Pacific Folding Furniture Market Revenue Share (%), by End User 2026 & 2034
Figure 28: Asia Pacific Folding Furniture Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 29: Asia Pacific Folding Furniture Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 30: Asia Pacific Folding Furniture Market Revenue (Billion), by Country 2026 & 2034
Figure 31: Asia Pacific Folding Furniture Market Revenue Share (%), by Country 2026 & 2034
Figure 32: South America Folding Furniture Market Revenue (Billion), by Product 2026 & 2034
Figure 33: South America Folding Furniture Market Revenue Share (%), by Product 2026 & 2034
Figure 34: South America Folding Furniture Market Revenue (Billion), by Material 2026 & 2034
Figure 35: South America Folding Furniture Market Revenue Share (%), by Material 2026 & 2034
Figure 36: South America Folding Furniture Market Revenue (Billion), by End User 2026 & 2034
Figure 37: South America Folding Furniture Market Revenue Share (%), by End User 2026 & 2034
Figure 38: South America Folding Furniture Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 39: South America Folding Furniture Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 40: South America Folding Furniture Market Revenue (Billion), by Country 2026 & 2034
Figure 41: South America Folding Furniture Market Revenue Share (%), by Country 2026 & 2034
Figure 42: Middle East & Africa Folding Furniture Market Revenue (Billion), by Product 2026 & 2034
Figure 43: Middle East & Africa Folding Furniture Market Revenue Share (%), by Product 2026 & 2034
Figure 44: Middle East & Africa Folding Furniture Market Revenue (Billion), by Material 2026 & 2034
Figure 45: Middle East & Africa Folding Furniture Market Revenue Share (%), by Material 2026 & 2034
Figure 46: Middle East & Africa Folding Furniture Market Revenue (Billion), by End User 2026 & 2034
Figure 47: Middle East & Africa Folding Furniture Market Revenue Share (%), by End User 2026 & 2034
Figure 48: Middle East & Africa Folding Furniture Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 49: Middle East & Africa Folding Furniture Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 50: Middle East & Africa Folding Furniture Market Revenue (Billion), by Country 2026 & 2034
Figure 51: Middle East & Africa Folding Furniture Market Revenue Share (%), by Country 2026 & 2034
Table 17: Europe Folding Furniture Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 18: Europe Folding Furniture Market Revenue Billion Forecast, by Country 2020 & 2034
 Folding Furniture Market