 Middle East AI Energy Market
: Size, Share & 2033 Forecast
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 271

Sandeep Singh
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Middle East AI Energy Market
Sandeep Singh
Research Analyst

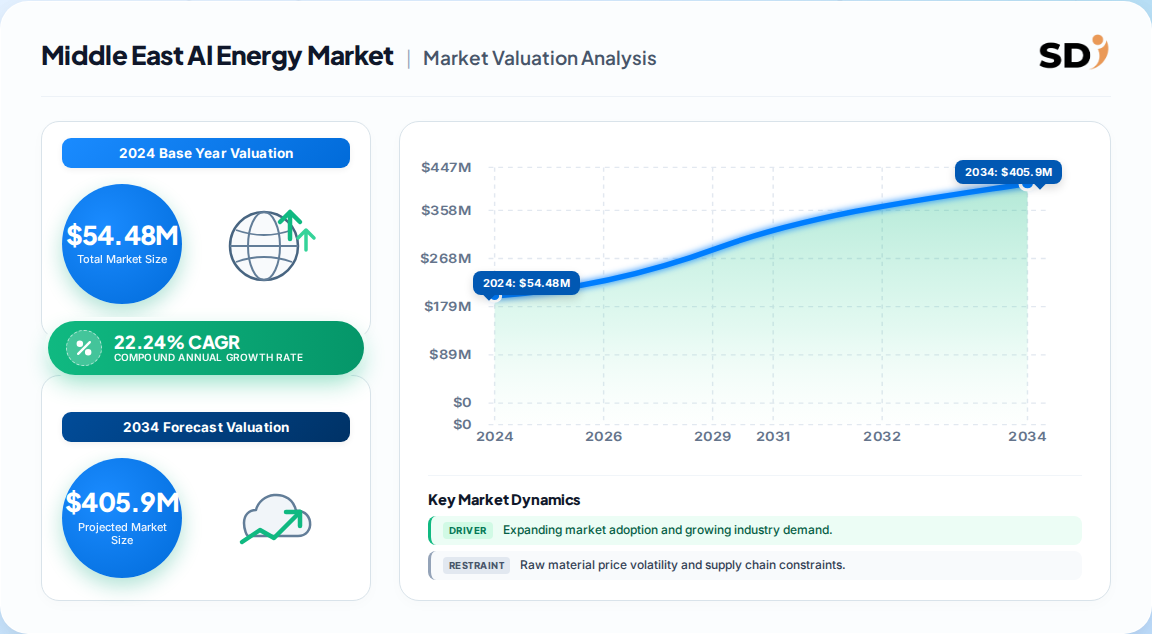
| Year | Market Size |
|---|---|
| 2024 | 54.00 M |
| 2025 | 67.00 M |
| 2026 | 81.00 M |
| 2027 | 100.0 M |
| 2028 | 122.0 M |
| 2029 | 149.0 M |
| 2030 | 182.0 M |

The Middle East AI energy market covers artificial intelligence solutions and services applied to electricity generation, grid operations, renewable integration and industrial energy management across Gulf and wider Middle East markets. It spans predictive maintenance, demand forecasting, load balancing and automated asset management deployed by utilities, industrial facilities and commercial portfolios.
This analysis covers AI solutions and services deployed in energy generation, transmission, distribution and consumption management across Middle East countries, segmented by type, application, deployment mode and end user. It addresses utility, industrial and commercial demand. This analysis does not cover general-purpose enterprise AI, defence or healthcare AI applications, nor conventional non-AI SCADA hardware replacement spending.
Published estimates diverge sharply: narrow definitions of AI software place the 2024 base near 54.48 Million, while broader energy-management software definitions start from a 220.12 Million 2025 base, implying materially different scope boundaries.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 54.48 Million | 2024 | 2033 (374.42 Million) | 22.24% | AI solutions & services in energy, Middle East | One published estimate |
| 220.12 Million | 2025 | 2031 (670.13 Million) | 20.84% | AI-powered energy management software, broader scope | A competing analysis |
| 274.4 Million | 2025 | 2033 (564.8 Million) | 9.0% | AI in energy, Middle East & Africa incl. Africa | A third published estimate |
Our analysis suggests the 22.24% figure is the most defensible growth rate for pure AI-in-energy spend, because it aligns with the region's grid-digitization procurement cycle. The 9% MEA figure is depressed by African market dilution and should not be used for Gulf-only business cases.
Segmentation is best read by type and application, because deployment mode and end user are purchase-behaviour variables layered on top of the same underlying capability stack.
| Parent segment | Children |
|---|---|
| By Type | Solutions, Services |
| By Application | Robotics, Renewable Energy Management, Demand Forecasting, Safety & Security & Infrastructure, Others |
| By Deployment Mode | Cloud-Based, On-Premises, Hybrid |
| By End User | Utilities, Commercial Buildings, Industrial Facilities, Others |
Solutions held 70.60% of 2024 revenue, but services are growing faster — a classic pattern where platform sales pull through integration and managed-service revenue.
Saudi Arabia leads with 44.35% of 2024 regional revenue, driven by Vision 2030 grid modernization, giga-project energy infrastructure and national AI commitments; the UAE follows with the fastest software growth, and Oman is the quickest-growing overall.
| Parent | Children |
|---|---|
| Middle East | Saudi Arabia, UAE, Qatar, Oman, Kuwait, Rest of Middle East |
| Country | 2024/2025 share |
|---|---|
| Saudi Arabia | 44.35% |
| UAE | 24% |
| Qatar | 11% |
| Oman | 9% |
| Kuwait | 6% |
| Rest of Middle East | 6% |
This concentration implies single-country regulatory shifts — particularly Saudi procurement rules — can move regional totals more than any technology trend.
Growth is driven by smart-grid digitization, renewable integration and mandatory efficiency targets; it is restrained by implementation cost, data-security concern and thin AI talent pools in smaller markets.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Smart grid & utility digitization | Driver | High | Predictive analytics procurement in Saudi and UAE utilities |
| AI load forecasting in commercial buildings | Driver | High | Cooling-load and peak-demand management in retail and hospitality |
| National decarbonization targets | Driver | Medium-High | Compliance reporting and energy-intensity control |
| Cloud-native platform expansion | Driver | Medium | Multi-site enterprise rollouts |
| High implementation cost | Restraint | High | Slows mid-market and public-sector adoption |
| Data security and sovereignty | Restraint | Medium-High | Constrains cross-border cloud deployment |
| Limited AI talent | Restraint | Medium | Extends deployment timelines |
The balance favours growth: drivers are structural and policy-backed, while restraints are largely commercial and erode as platform pricing falls.
Siemens, Schneider Electric, ABB, GE and Masdar lead delivery, with Honeywell and Johnson Controls strong in building energy software; differentiation rests on hybrid deployment capability, regulatory fit and enterprise service layers rather than core algorithms.
| Vendor | Core strength | Regional positioning |
|---|---|---|
| Siemens | Grid automation and digital twin platforms | Broad GCC utility footprint |
| Schneider Electric | Building and industrial energy management software | Strong UAE multi-site deployments |
| ABB | Automation and grid optimization | Industrial and utility assets |
| GE | Power generation analytics | Large plant-scale installations |
| Honeywell | Industrial and building controls | Petrochemical and refining demand |
| Johnson Controls | Building management systems | Commercial real estate |
| Masdar | Renewable project delivery | UAE flagship programs |
Competitive moats are increasingly integration-based: vendors that already hold the operational layer are harder to displace than pure-analytics challengers. Our analysis suggests service attach rates, not licence pricing, will decide margin outcomes.
Selection should hinge on hybrid deployment capability, local data-residency compliance and proven integration with existing SCADA and metering estates. Switching costs are high once forecasting models are trained on operator-specific load data; migration typically requires retraining and revalidation cycles.
Procurement risk concentrates in scope ambiguity between software and services. Buyers should contract service levels against measurable outcomes — forecast error, downtime reduction, energy intensity — rather than licences delivered. Regulatory fragmentation across GCC states means a platform approved in one market may require re-certification elsewhere, adding timeline risk to multi-country rollouts.
The balance of evidence favours a high-growth, software-led trajectory for this market, with the 22.24% CAGR more credible than the 9% MEA-wide figure for Gulf-focused planning. The strongest counter-argument is that talent scarcity and legacy grid integration could cap realized growth below forecast — a risk we weight as material but not decisive.
Our judgment is that value is migrating from licence sales toward integration and managed-service layers, where local presence and regulatory fluency matter more than algorithm quality. Vendors treating AI as a product will lose share to those treating it as an operating relationship.
Evidence that would change this conclusion: sustained procurement delays beyond 2026, or a sharp fall in cloud data-residency restrictions that commoditizes platform differentiation.
| Region | Market Share (%) |
|---|---|
| Saudi Arabia | 0.44% |
| UAE | 0.24% |
| Qatar | 0.11% |
| Oman | 0.09% |
| Kuwait | 0.06% |
| Rest of Middle East | 0.06% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 22.24% from 2020-2034 |
| Segmentation |
|
The market was valued at approximately 54.48 Million in 2024 and is projected to reach 374.42 Million by 2033, growing at a 22.24% CAGR from 2025 to 2033.
Saudi Arabia held 44.35% of regional revenue in 2024, driven by Vision 2030 grid modernization and giga-project energy infrastructure. The UAE is the fastest-growing software market, while Oman grows fastest overall.
Renewable energy management led applications with 26.47% revenue share in 2024, as utilities integrate utility-scale solar and require AI-driven forecasting and grid balancing across hybrid generation assets.
Siemens, Schneider Electric, ABB, GE and Masdar lead delivery, with Honeywell and Johnson Controls strong in building energy software. Competition increasingly hinges on hybrid deployment capability and service attach rates.
High implementation costs, data security and sovereignty concerns, limited AI talent in smaller markets, fragmented regulatory frameworks and integration challenges with legacy grid infrastructure all slow deployment.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the energy-AI value chain: grid automation and equipment suppliers, energy management software vendors, systems integrators and deployment partners, utility and industrial asset operators, and regional renewable project developers. Within these organizations we engaged decision-makers including Chief Digital Officers, Heads of Grid Operations, VP-level Procurement and Sourcing Leads, and Technical Directors responsible for SCADA and metering estates.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Digital & Technology Officers | 35% |
| Grid Operations & Technical Directors | 30% |
| Procurement & Sourcing Leads | 22% |
| Regulatory & Compliance Managers | 13% |
| Company Type | Representation (%) |
|---|---|
| Energy Software & Automation Vendors | 40% |
| Systems Integrators & Deployment Partners | 30% |
| Utilities & Industrial Asset Operators | 20% |
| Renewable Project Developers | 10% |
We validated findings against official multilateral and standards sources, including UN Comtrade energy equipment flows, International Energy Agency electricity statistics, national utility annual reports and investor presentations, patent filings in grid analytics and forecasting, and technical standards published by IEC and IEEE for grid automation and energy management systems. Corporate 10-K and annual filings were used to cross-check vendor revenue disclosure and regional exposure.
Sizing was triangulated simultaneously through top-down allocation from national electricity consumption, digitalization budgets and grid investment programs, and bottom-up modeling of vendor capacity, software licence and service pricing, and end-use consumption across utility, industrial and commercial segments.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |