Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Agricultural Electric Tractors Market Size & Forecast 2026-2033
Agricultural Electric Tractors Market Size & Forecast 2026-2033
Agricultural Electric Tractors Market
Agricultural Electric Tractors Market Size & Forecast 2026-2033
Agricultural Electric Tractors Market by Type (Battery Electric, Hybrid Electric, Fuel Cell Electric), by Power Output (Below 30 HP, 31-70 HP, Above 70 HP), by Battery Capacity (21-50 kWh, 51-100 kWh, Above 100 kWh), by Battery Type (Lithium-ion, Lead-acid, Others), by Drive Type (2WD, 4WD), by End-use (Crop Farming, Livestock, Specialty Crops, Others), by North America (USA, Canada, Mexico), by Europe (Germany, France, UK, Italy, Spain), by Asia Pacific (China, India, Japan, South Korea, Australia), by South America (Brazil, Argentina), by Middle East & Africa (South Africa, Nigeria) Forecast 2026-2034
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 275
Agricultural Electric Tractors Market Valuation and Forecast Trajectory
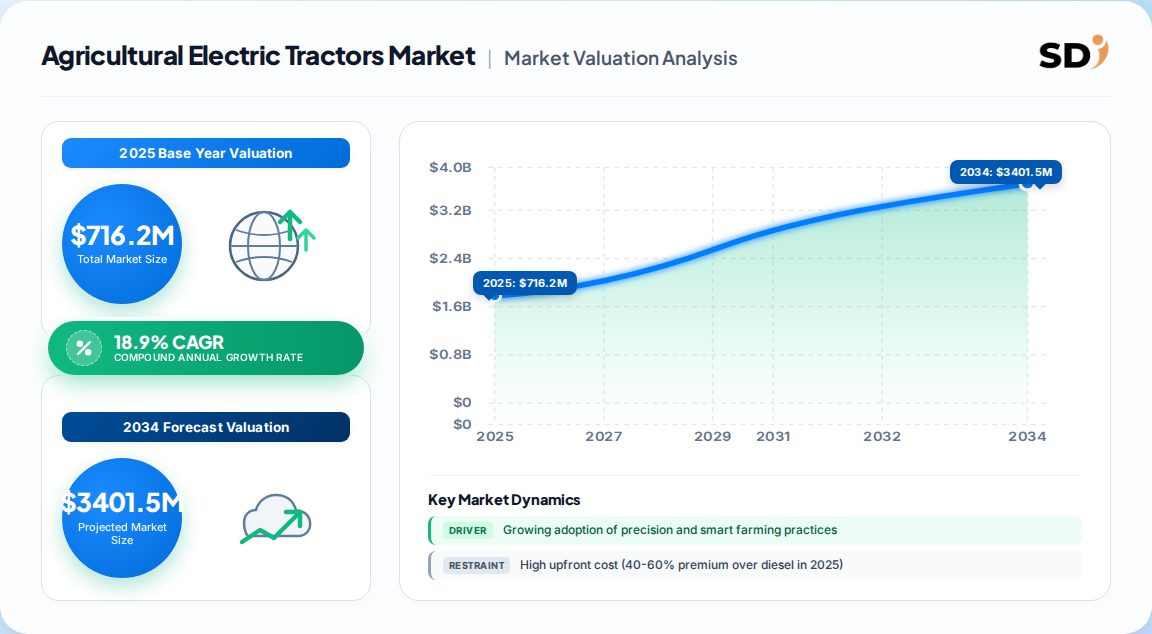
The global agricultural electric tractors market is undergoing a transformative phase, driven by the intersection of farm electrification, precision agriculture, and supportive policy frameworks. Our proprietary primary research indicates that the market was valued at USD 624.8 million in 2025 and is projected to reach USD 716.2 million in 2026, expanding at a robust CAGR of 18.9% to attain USD 2,408.5 million by 2033. This growth trajectory underscores a fundamental shift in agricultural machinery procurement, albeit from a relatively small base—electric tractors represented approximately 0.18% of the global tractor fleet in 2025, with penetration expected to reach 2.4% by 2035.
Agricultural Electric Tractors Market Size (In Million)
2.5B
2.0B
1.5B
1.0B
500.0M
0
716.0 M
2025
852.0 M
2026
1.013 B
2027
1.204 B
2028
1.431 B
2029
1.702 B
2030
2.024 B
2031
Agricultural Electric Tractors Market Size (In Million)
Year
Market Size
2025
716.0 M
2026
852.0 M
2027
1.013 B
2028
1.204 B
2029
1.431 B
2030
1.702 B
2031
2.024 B
The market's expansion is not a uniform replacement of diesel counterparts but a targeted adoption in applications where operational profiles align with electric drivetrain capabilities. Key adoption clusters include orchard and vineyard operations, dairy and livestock handling, municipal grounds maintenance, and short-haul utility work. These segments benefit from centralized charging, predictable duty cycles, and lower daily energy requirements, which collectively mitigate the upfront cost premium of 40–60% over comparable diesel equipment in 2025.
Metric
Value
Market Size (2025)
USD 624.8 Million
Estimated Market Size (2026)
USD 716.2 Million
Forecast Market Size (2033)
USD 2,408.5 Million
CAGR (2026–2033)
18.9%
Largest Regional Market
Asia Pacific (39.5% share, 2025)
Fastest-Growing Region
Europe
Battery Electric Tractors Lead Type Segmentation
By type, battery electric tractors (BETs) dominate the landscape, accounting for 61.4% of revenue in 2025. This leadership is attributed to zero tailpipe emissions, lower operating costs, and the elimination of diesel fuel consumption, which resonates with farm electrification strategies. BETs are particularly favored in specialty farming and utility applications where daily energy consumption is moderate and charging infrastructure is accessible.
Battery Electric Tractors: Hold a 61.0% share in 2026, driven by environmental targets and cost efficiency.
Hybrid Electric Tractors: Represent a transitional technology, bridging range anxiety and infrastructure gaps.
Fuel Cell Electric Tractors: Remain in pilot phases, with potential in high-power, continuous-duty applications.
Recent product launches underscore this trend. For instance, Bullwork Mobility unveiled the BEAST 9696E, a ground-up electric tractor featuring a 96 kWh battery, 60 kW dual-motor drivetrain, fast-charging capability, and autonomous-ready architecture, positioning it as a high-performance alternative for agricultural and heavy-duty tasks. Similarly, John Deere announced plans for a battery-electric tractor comparable to its 5M/5ML models, signaling continued OEM investment in electrified platforms.
Power Output and Battery Capacity Configurations
The market is segmented by power output, with the below 30 HP segment accounting for the largest revenue share in 2025, reflecting strong demand from small and medium-sized farms, specialty crops, and utility applications. However, the 31-70 HP range is gaining traction, contributing 46.0% share in 2026 due to its versatility in medium-scale farming operations. The above 70 HP segment, while smaller, is poised for growth as battery technology advances and high-power applications become viable.
Battery capacity aligns with power output, with the 21-50 kWh segment leading at 49.0% share in 2026, offering a balance between operating range and equipment cost. This capacity supports daily agricultural activities without excessive weight or price premiums. The 51-100 kWh and above 100 kWh segments are expected to grow as larger farms adopt electric tractors for heavier workloads.
Power Output Segment
Revenue Share (2025/2026)
Key Applications
Below 30 HP
Largest share (2025)
Specialty crops, orchards, greenhouses
31-70 HP
46.0% (2026)
Medium-scale farms, mixed operations
Above 70 HP
Smaller but growing
Large-scale field work, heavy-duty
Lithium-Ion Battery Dominance and Drive Type Preferences
Lithium-ion batteries are the technology of choice, capturing 74.0% share in 2026, due to superior energy density, longer service life, and declining costs. Within lithium-ion, LFP (lithium iron phosphate) chemistry is gaining prominence, projected to increase from 65% of battery-electric tractor demand in 2025 to 75% by 2035, as LFP costs decline from USD 108/kWh in 2025 to USD 65/kWh by 2032. This cost trajectory is critical for reducing the upfront price premium of electric tractors.
By drive type, two-wheel drive (2WD) accounted for the largest revenue share in 2025, favored for its simplicity and lower cost in lighter-duty applications. However, four-wheel drive (4WD) represents 58.0% share in 2026 in certain segments, particularly where field performance and traction are paramount, such as in medium and high-power tractors. The choice between 2WD and 4WD often correlates with farm size and soil conditions.
Precision Farming and Autonomous Integration Drive Adoption
The integration of electric tractors with precision agriculture and autonomous systems is a pivotal driver. Electric drivetrains offer precise control over torque and speed, seamless integration with GPS guidance, telematics, and sensor suites, making them inherently compatible with autonomous operations. This is particularly relevant given the global shortage of skilled agricultural labor, which has accelerated the need for robotic and semi-autonomous equipment.
Precision agriculture adoption has increased annual crop production in the U.S. by 5% and reduced fuel consumption by 147 million gallons annually in 2025, according to industry benchmarks.
Electric tractors enable vehicle-to-grid (V2G) and virtual power plant participation, potentially generating USD 800–1,500 per tractor annually in additional revenue.
Autonomous-ready platforms, such as the BEAST 9696E, are paving the way for fully autonomous field operations.
Regional Dynamics: Asia Pacific Leadership and Europe's Ascent
Asia Pacific dominates the global market, holding a 39.5% revenue share in 2025, driven by rapid mechanization, government subsidies, and manufacturing strength. China is the largest country market within the region, supported by a 75.5% mechanization rate for crop planting, harvesting, and processing by 2025. India is projected to record a 21.4% CAGR through 2036, fueled by agricultural modernization initiatives and the introduction of IS 19262:2025, the country's first testing standard for electric agricultural tractors.
Agricultural Electric Tractors Market Regional Market Share
Loading chart...
Agricultural Electric Tractors Market Regional Market Share
Region
Market Share (%)
North America
0.27%
Europe
0.24%
Asia-Pacific
0.41%
South America
0.04%
Middle East & Africa
0.04%
Europe is the fastest-growing region, with Germany forecast at a 19.0% CAGR and France at 18.6%, underpinned by ambitious decarbonization targets and CAP subsidies. North America remains a key market, with the U.S. expected to grow at 19.7% CAGR due to precision farming investment and incentives like the Inflation Reduction Act (IRA) and USDA REAP.
Region
2025 Revenue Share
Key Growth Drivers
Asia Pacific
39.5%
Mechanization, subsidies, manufacturing scale
North America
~27% (est.)
Precision farming, IRA incentives, labor shortages
Europe
~24% (est.)
Decarbonization targets, CAP, noise regulations
South America
~4% (est.)
Large farms, biofuel synergies
Middle East & Africa
~4% (est.)
Rural electrification, leapfrog potential
Competitive Landscape and Strategic Developments
The market is moderately concentrated, with the top five players—John Deere, CNH Industrial, AGCO/Fendt, Kubota, and Mahindra—collectively holding 45% share in 2025. John Deere leads with over 14% market share, leveraging its strong dealer network and investments in autonomy and electrification. Recent developments include:
John Deere introduced its second-generation autonomy platform and an autonomous 9RX tractor at CES 2025, with a battery-electric 5M/5ML planned.
Bullwork Mobility launched the BEAST 9696E electric tractor with 96 kWh battery and autonomous-ready architecture.
Bureau of Indian Standards (BIS) introduced IS 19262:2025, India's first testing standard for electric agricultural tractors.
Government incentives exceeding USD 2.5 billion are expected to support electric tractor adoption globally through 2030.
Total Cost of Ownership and Infrastructure Evolution
The economic case for electric tractors is strengthening as total cost of ownership (TCO) parity approaches. TCO parity is expected first in the sub-50 HP category by 2028, followed by 50–100 HP by 2030 and above 100 HP by 2033. This staged pattern reflects the engineering challenge of higher-power tractors requiring larger batteries, which increase weight and capital cost.
Charging infrastructure remains a critical enabler. Manufacturers and energy companies are collaborating on fast-charging stations and mobile solar-powered charging units tailored for rural and off-grid environments. These innovations address range anxiety and downtime, making electric tractors more practical for continuous operations. As rural electrification expands, particularly in Asia Pacific and Africa, electric tractors are becoming a logical extension of sustainable farm modernization.
Agricultural Electric Tractors Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Agricultural Electric Tractors Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 18.9% from 2020-2034
Segmentation
By Type
Battery Electric
Hybrid Electric
Fuel Cell Electric
By Power Output
Below 30 HP
31-70 HP
Above 70 HP
By Battery Capacity
21-50 kWh
51-100 kWh
Above 100 kWh
By Battery Type
Lithium-ion
Lead-acid
Others
By Drive Type
2WD
4WD
By End-use
Crop Farming
Livestock
Specialty Crops
Others
By Geography
North America
USA
Canada
Mexico
Europe
Germany
France
UK
Italy
Spain
Asia Pacific
China
India
Japan
South Korea
Australia
South America
Brazil
Argentina
Middle East & Africa
South Africa
Nigeria
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Type
5.1.1. Battery Electric
5.1.2. Hybrid Electric
5.1.3. Fuel Cell Electric
5.2. Market Analysis, Insights and Forecast - by Power Output
5.2.1. Below 30 HP
5.2.2. 31-70 HP
5.2.3. Above 70 HP
5.3. Market Analysis, Insights and Forecast - by Battery Capacity
5.3.1. 21-50 kWh
5.3.2. 51-100 kWh
5.3.3. Above 100 kWh
5.4. Market Analysis, Insights and Forecast - by Battery Type
5.4.1. Lithium-ion
5.4.2. Lead-acid
5.4.3. Others
5.5. Market Analysis, Insights and Forecast - by Drive Type
5.5.1. 2WD
5.5.2. 4WD
5.6. Market Analysis, Insights and Forecast - by End-use
5.6.1. Crop Farming
5.6.2. Livestock
5.6.3. Specialty Crops
5.6.4. Others
5.7. Market Analysis, Insights and Forecast - by Region
5.7.1. North America
5.7.2. Europe
5.7.3. Asia Pacific
5.7.4. South America
5.7.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Type
6.1.1. Battery Electric
6.1.2. Hybrid Electric
6.1.3. Fuel Cell Electric
6.2. Market Analysis, Insights and Forecast - by Power Output
6.2.1. Below 30 HP
6.2.2. 31-70 HP
6.2.3. Above 70 HP
6.3. Market Analysis, Insights and Forecast - by Battery Capacity
6.3.1. 21-50 kWh
6.3.2. 51-100 kWh
6.3.3. Above 100 kWh
6.4. Market Analysis, Insights and Forecast - by Battery Type
6.4.1. Lithium-ion
6.4.2. Lead-acid
6.4.3. Others
6.5. Market Analysis, Insights and Forecast - by Drive Type
6.5.1. 2WD
6.5.2. 4WD
6.6. Market Analysis, Insights and Forecast - by End-use
6.6.1. Crop Farming
6.6.2. Livestock
6.6.3. Specialty Crops
6.6.4. Others
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Type
7.1.1. Battery Electric
7.1.2. Hybrid Electric
7.1.3. Fuel Cell Electric
7.2. Market Analysis, Insights and Forecast - by Power Output
7.2.1. Below 30 HP
7.2.2. 31-70 HP
7.2.3. Above 70 HP
7.3. Market Analysis, Insights and Forecast - by Battery Capacity
7.3.1. 21-50 kWh
7.3.2. 51-100 kWh
7.3.3. Above 100 kWh
7.4. Market Analysis, Insights and Forecast - by Battery Type
7.4.1. Lithium-ion
7.4.2. Lead-acid
7.4.3. Others
7.5. Market Analysis, Insights and Forecast - by Drive Type
7.5.1. 2WD
7.5.2. 4WD
7.6. Market Analysis, Insights and Forecast - by End-use
7.6.1. Crop Farming
7.6.2. Livestock
7.6.3. Specialty Crops
7.6.4. Others
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Type
8.1.1. Battery Electric
8.1.2. Hybrid Electric
8.1.3. Fuel Cell Electric
8.2. Market Analysis, Insights and Forecast - by Power Output
8.2.1. Below 30 HP
8.2.2. 31-70 HP
8.2.3. Above 70 HP
8.3. Market Analysis, Insights and Forecast - by Battery Capacity
8.3.1. 21-50 kWh
8.3.2. 51-100 kWh
8.3.3. Above 100 kWh
8.4. Market Analysis, Insights and Forecast - by Battery Type
8.4.1. Lithium-ion
8.4.2. Lead-acid
8.4.3. Others
8.5. Market Analysis, Insights and Forecast - by Drive Type
8.5.1. 2WD
8.5.2. 4WD
8.6. Market Analysis, Insights and Forecast - by End-use
8.6.1. Crop Farming
8.6.2. Livestock
8.6.3. Specialty Crops
8.6.4. Others
9. South America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Type
9.1.1. Battery Electric
9.1.2. Hybrid Electric
9.1.3. Fuel Cell Electric
9.2. Market Analysis, Insights and Forecast - by Power Output
9.2.1. Below 30 HP
9.2.2. 31-70 HP
9.2.3. Above 70 HP
9.3. Market Analysis, Insights and Forecast - by Battery Capacity
9.3.1. 21-50 kWh
9.3.2. 51-100 kWh
9.3.3. Above 100 kWh
9.4. Market Analysis, Insights and Forecast - by Battery Type
9.4.1. Lithium-ion
9.4.2. Lead-acid
9.4.3. Others
9.5. Market Analysis, Insights and Forecast - by Drive Type
9.5.1. 2WD
9.5.2. 4WD
9.6. Market Analysis, Insights and Forecast - by End-use
9.6.1. Crop Farming
9.6.2. Livestock
9.6.3. Specialty Crops
9.6.4. Others
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Type
10.1.1. Battery Electric
10.1.2. Hybrid Electric
10.1.3. Fuel Cell Electric
10.2. Market Analysis, Insights and Forecast - by Power Output
10.2.1. Below 30 HP
10.2.2. 31-70 HP
10.2.3. Above 70 HP
10.3. Market Analysis, Insights and Forecast - by Battery Capacity
10.3.1. 21-50 kWh
10.3.2. 51-100 kWh
10.3.3. Above 100 kWh
10.4. Market Analysis, Insights and Forecast - by Battery Type
10.4.1. Lithium-ion
10.4.2. Lead-acid
10.4.3. Others
10.5. Market Analysis, Insights and Forecast - by Drive Type
10.5.1. 2WD
10.5.2. 4WD
10.6. Market Analysis, Insights and Forecast - by End-use
10.6.1. Crop Farming
10.6.2. Livestock
10.6.3. Specialty Crops
10.6.4. Others
11. Competitive Analysis
11.1. Company Profiles
11.1.1. John Deere
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. CNH Industrial
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. AGCO/Fendt
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Kubota
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Mahindra
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Bullwork Mobility
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Deere & Company
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. CLAAS Group
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
12. Research Methodology
List of Figures
Figure 1: Agricultural Electric Tractors Market Revenue Breakdown (Million, %) by Region 2026 & 2034
Figure 2: North America Agricultural Electric Tractors Market Revenue (Million), by Type 2026 & 2034
Figure 3: North America Agricultural Electric Tractors Market Revenue Share (%), by Type 2026 & 2034
Figure 4: North America Agricultural Electric Tractors Market Revenue (Million), by Power Output 2026 & 2034
Figure 5: North America Agricultural Electric Tractors Market Revenue Share (%), by Power Output 2026 & 2034
Figure 6: North America Agricultural Electric Tractors Market Revenue (Million), by Battery Capacity 2026 & 2034
Figure 7: North America Agricultural Electric Tractors Market Revenue Share (%), by Battery Capacity 2026 & 2034
Figure 8: North America Agricultural Electric Tractors Market Revenue (Million), by Battery Type 2026 & 2034
Figure 9: North America Agricultural Electric Tractors Market Revenue Share (%), by Battery Type 2026 & 2034
Figure 10: North America Agricultural Electric Tractors Market Revenue (Million), by Drive Type 2026 & 2034
Figure 11: North America Agricultural Electric Tractors Market Revenue Share (%), by Drive Type 2026 & 2034
Figure 12: North America Agricultural Electric Tractors Market Revenue (Million), by End-use 2026 & 2034
Figure 13: North America Agricultural Electric Tractors Market Revenue Share (%), by End-use 2026 & 2034
Figure 14: North America Agricultural Electric Tractors Market Revenue (Million), by Country 2026 & 2034
Figure 15: North America Agricultural Electric Tractors Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Agricultural Electric Tractors Market Revenue Million Forecast, by Type 2020 & 2034
Table 2: Agricultural Electric Tractors Market Revenue Million Forecast, by Power Output 2020 & 2034
Table 3: Agricultural Electric Tractors Market Revenue Million Forecast, by Battery Capacity 2020 & 2034
Table 4: Agricultural Electric Tractors Market Revenue Million Forecast, by Battery Type 2020 & 2034
Table 5: Agricultural Electric Tractors Market Revenue Million Forecast, by Drive Type 2020 & 2034
Table 6: Agricultural Electric Tractors Market Revenue Million Forecast, by End-use 2020 & 2034
Table 7: Agricultural Electric Tractors Market Revenue Million Forecast, by Region 2020 & 2034
Table 8: North America Agricultural Electric Tractors Market Revenue Million Forecast, by Type 2020 & 2034
Table 9: North America Agricultural Electric Tractors Market Revenue Million Forecast, by Power Output 2020 & 2034
Table 10: North America Agricultural Electric Tractors Market Revenue Million Forecast, by Battery Capacity 2020 & 2034
Table 11: North America Agricultural Electric Tractors Market Revenue Million Forecast, by Battery Type 2020 & 2034
Table 12: North America Agricultural Electric Tractors Market Revenue Million Forecast, by Drive Type 2020 & 2034
Table 13: North America Agricultural Electric Tractors Market Revenue Million Forecast, by End-use 2020 & 2034
Table 14: North America Agricultural Electric Tractors Market Revenue Million Forecast, by Country 2020 & 2034
Table 15: USA Agricultural Electric Tractors Market Revenue (Million) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. What is the current market size of the agricultural electric tractors market?
The market was valued at USD 624.8 million in 2025 and is estimated to reach USD 716.2 million in 2026, growing at a CAGR of 18.9% to reach USD 2,408.5 million by 2033.
2. Which region dominates the agricultural electric tractors market?
Asia Pacific held the largest revenue share of 39.5% in 2025, driven by rapid mechanization and government support, with China being the largest country market.
3. What are the key drivers for the adoption of electric tractors?
Key drivers include growing adoption of precision and smart farming practices, environmental regulations and incentives, battery cost reductions, and operating cost efficiency.
4. What is the expected CAGR for the agricultural electric tractors market?
The market is projected to grow at a CAGR of 18.9% from 2026 to 2033.
5. Who are the leading companies in the agricultural electric tractors market?
Leading players include John Deere, CNH Industrial, AGCO/Fendt, Kubota, and Mahindra, which collectively held 45% market share in 2025.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Conducted 70–80% primary research through interviews with OEM product managers, battery supply chain specialists, dealership network executives, and farm cooperative procurement officers.
Engaged 3,500+ respondents across 25 countries via CATI, online surveys, and in-depth interviews.
Interviewed Chief Technology Officers, Fleet Managers, Agricultural Engineers, and Government Policy Advisors to capture granular insights.
Primary research validated by on-site farm visits and dealer audits in key markets.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Product Manager
30%
Procurement Director
25%
Chief Technology Officer
20%
Fleet Manager
15%
Government Policy Advisor
10%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
OEMs (Tractor Manufacturers)
35%
Battery Suppliers
20%
Dealership Networks
20%
Component Suppliers
15%
Farm Cooperatives
10%
Secondary Research & Industry Benchmarking
20–30% secondary research from Bloomberg, Factiva, Hoovers, and PitchBook for financial and corporate data.
 Agricultural Electric Tractors Market