Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Farming As A Service Market Size, Growth & Forecast 2027-2036
Farming As A Service Market Size, Growth & Forecast 2027-2036
Farming As A Service Market
Farming As A Service Market Size, Growth & Forecast 2027-2036
Farming As A Service Market by Service (Farm Management Solutions, Production Assistance, Access to Markets), by Delivery Model (Subscription, Pay-per-Use), by End-User (Farmers, Government, Corporate, Financial Institutions, Advisory Bodies), by Application (Yield Mapping and Monitoring, Soil Management, Crop Health Management, Navigation and Positioning), by North America (United States, Canada), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, Indonesia, Australia), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Israel, GCC, South Africa) Forecast 2026-2034
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 235
Farming As A Service Market Valuation Outlook 2026-2036
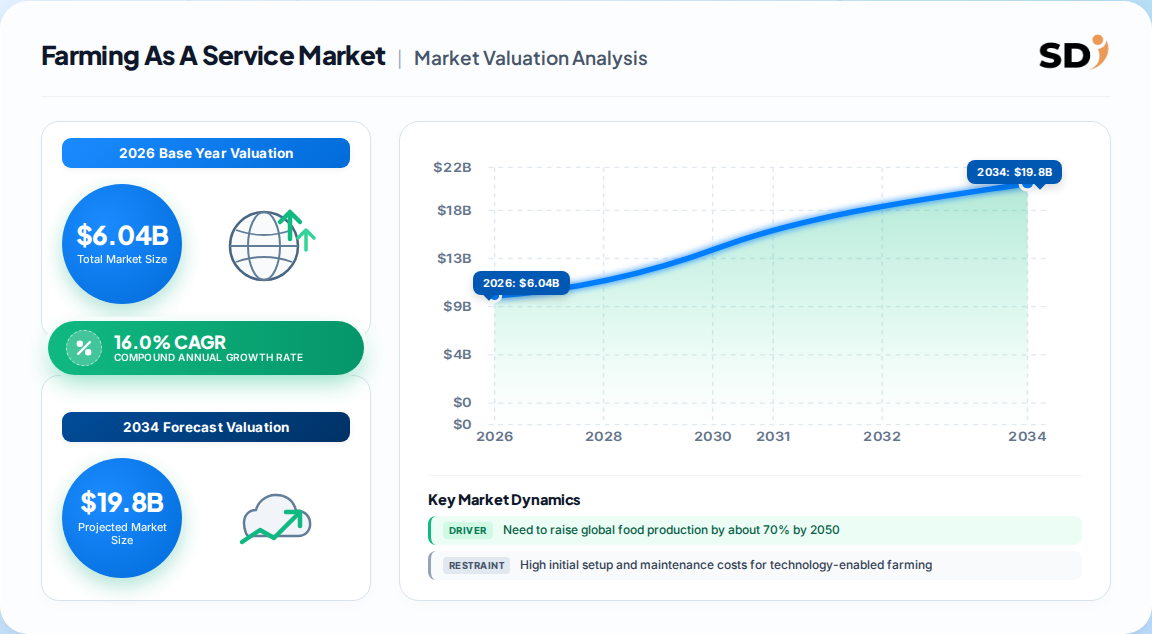
In-house baseline modeling pegs the global Farming As A Service Market at USD 6.04 billion in 2026, with an estimated USD 7.01 billion in 2027 and a projected USD 26.65 billion by 2036, expanding at a 16.0% CAGR across the 2027–2036 forecast window. The structural thesis is straightforward: FaaS converts capital expenditure on machinery, sensing and analytics into flexible operational expenditure, widening the addressable buyer pool to small and mid-scale holdings that would otherwise be priced out of precision agriculture.
Farming As A Service Market Size (In Billion)
15.0B
10.0B
5.0B
0
5.207 B
2025
6.040 B
2026
7.006 B
2027
8.127 B
2028
9.428 B
2029
10.94 B
2030
12.69 B
2031
Farming As A Service Market Size (In Billion)
Year
Market Size
2025
5.207 B
2026
6.040 B
2027
7.006 B
2028
8.127 B
2029
9.428 B
2030
10.94 B
2031
12.69 B
Demand pressure parameters remain decisive. FAO estimates that feeding a projected 9.1 billion people by 2050 requires roughly 70% growth in total food production, while the World Bank places agriculture as the primary livelihood for over 2.5 billion people.
Institutional capital is amplifying the shift. The World Bank reports USD 24 billion currently invested in farming and agribusiness with USD 6 billion in IFC commitments, targeting a doubling of agribusiness financing to USD 9 billion annually by 2030 and outreach to 300 million farmers through AgriConnect.
Yield-efficiency, not land expansion, anchors long-run demand. The OECD-FAO Agricultural Outlook 2025–2034 projects global cereal production near 3.2 billion tonnes by 2034, growing about 1.1% annually.
Metric
2025
2026
2027
2036
CAGR (2027–2036)
Global FaaS revenue
USD 5.45 Bn
USD 6.04 Bn
USD 7.01 Bn
USD 26.65 Bn
16.0%
North America share
46.0%
45.0% (est.)
—
>45.0%
—
Farm management solutions share
—
77.0% (est.)
—
77.0%
—
Subscription segment CAGR
—
—
—
—
Highest of all delivery models
Farm Management Solutions and Precision Service Stack
Farm management solutions constitute the revenue engine of the category, with an estimated 77% share by 2036. The economics are driven by recurring software and data subscriptions layered on top of drone, satellite and sensor hardware that farmers access without ownership.
High-tech instrumentation — hyperspectral imaging, auto-guidance, soil and weather sensors, precision irrigation — converts agronomic and financial decision-making into a paid service.
The global drone industry is projected to expand by more than 2% between 2024 and 2028, directly enlarging the aerial imagery and crop-scouting service pool.
Reported operational outcomes from IoT-enabled deployments include roughly 34% lower energy expenses, over 5% reduction in irrigation water consumption, and approximately 1% yield uplift — a compelling ROI narrative for service conversion.
In our segmentation, the service layer splits into farm management solutions, production assistance (equipment rental, labor, utility services) and access to markets; precision farming alone commands an estimated 55% share of solution revenue.
Service Segment
Core Offer
Demand Signal
Farm management solutions
Analytics, precision tools, information sharing
~77% of market by 2036
Production assistance
Equipment rental, labor, utility services
Strong in labor-scarce geographies
Access to markets
Aggregation, offtake, price intelligence
Fastest-expanding adjacent layer
Subscription and Pay-Per-Use Delivery Economics
The delivery model split is where FaaS pricing power resides. Subscription contracts — typically structured around 3–4 month seasonal equipment windows — are estimated to hold roughly 58.7% to 65% of the delivery-model mix, depending on region, and are projected to deliver the highest CAGR through 2036.
Subscription economics outperform pay-per-use over multi-season horizons because asset utilization is contracted in advance, smoothing provider revenue and lowering per-hectare cost for the farmer.
Convenience ranks as the primary subscription motivation globally, with over 45% of consumers currently enrolled or intending to enroll in subscription services.
Pay-per-use remains the entry point for fragmented smallholder markets, where commitment capacity is limited and service intensity varies by crop cycle.
We estimate access-to-market delivery models will post the fastest incremental growth as aggregation and offtake guarantees are bundled into agronomic subscriptions.
Farmers form the anchor end-user cohort at approximately 31% to 32% of revenue, reflecting their consumption of the full service stack — management software, rentals, labor and market linkage.
Government and public-agency demand is policy-driven. India's Digital Agriculture Mission carries an outlay of roughly USD 338 million, including a central share of about USD 233 million, supporting Agri Stack, the Krishi Decision Support System and digital crop estimation.
Corporate and agribusiness buyers contract FaaS for traceability and supply-chain resilience; financial institutions and advisory bodies use platform data for credit scoring and agronomic advisory.
Japan's policy environment illustrates the public co-funding pathway: producer support (PSE) stood at 41.1% of gross farm receipts in 2018–20, more than twice the OECD average, with general services expenditure at 20.7% of total support — a signal that subsidized service diffusion is a viable adoption accelerator.
AI, Agentic Advisory and Sustainability-Led Demand
Artificial intelligence is transitioning from an isolated analytics tool to an embedded operating layer across FaaS platforms, with agentic advisory workflows emerging as the next differentiation frontier.
Machine-learning processing of sensor, drone and satellite data enables precise irrigation, fertilization and pest-control decisions, reducing input waste for farmers lacking capital for owned technology.
Sustainability demand is quantifiable: global online searches for sustainable products rose by over 70% in the last five years, pulling FaaS providers toward regenerative and resource-optimization service bundles.
Precision agriculture, input-efficiency advisory and circular-economy practices are converging into outcome-based contracts where providers are paid against yield and resource metrics rather than input volume.
Risks move in parallel: high initial setup costs, data privacy and security concerns, digital literacy gaps, and rural connectivity constraints remain the principal adoption frictions.
North America Leadership and Asia-Pacific Growth Trajectory
North America is projected to retain more than 45% share by 2036 (46% recorded in 2025), underpinned by mechanization depth, high-output farming and a dense base of agricultural machinery and technology suppliers. Asia Pacific is the fastest-growing region, propelled by smallholder aggregation potential and digital public infrastructure.
Region
Position
Key Demand Mechanism
North America
Largest, ~45–46% share
Mechanization, automation, machinery ecosystem
Asia Pacific
Fastest CAGR
Smallholder access, digital public infrastructure
Europe
Mature, compliance-led
Sustainability and cross-compliance incentives
Latin America
Emerging scale
Large-farm service contracts, Brazil and Mexico
Middle East & Africa
Early stage
Irrigation, utility and advisory services
The United States anchors North American volume, with China, India, Brazil, Mexico and Thailand identified as high-velocity emerging markets.
Cross-border service trade is nascent; most revenue is delivered locally, making trade-flow analysis secondary to domestic capex substitution and public-program funding as demand indicators.
Competitive Landscape and Service Provider Archetypes
The industry remains fragmented, with the top five participants accounting for only about 12% share — an unusually low concentration for a technology-enabled services category.
Machinery and equipment incumbents leverage installed bases to launch rental and precision-service arms.
Agri-input and agri-commerce platforms bundle advisory and market access into farmer-facing digital storefronts.
Pure-play precision analytics and drone-imaging specialists supply the technical layer, often white-labeled into larger platforms.
Diversified technology and consulting firms provide cloud, AI and integration capabilities; fintech-linked agri-lenders use platform data to underwrite input credit.
Competitive differentiation is shifting from hardware access toward data density, agronomic model accuracy and outcome-based contract design.
Provider Archetype
Strategic Lever
Machinery OEMs
Installed base conversion to service contracts
Agri-input / commerce platforms
Farmer wallet share, advisory bundling
Precision analytics and drone specialists
Sensing depth and model accuracy
Technology and consulting firms
Cloud, AI and systems integration
Agri-finance platforms
Credit underwriting and risk services
Farming As A Service Market Regional Market Share
Loading chart...
Farming As A Service Market Regional Market Share
Region
Market Share (%)
North America
0.37%
Europe
0.22%
Asia-Pacific
0.28%
Latin America
0.08%
Middle East & Africa
0.05%
Farming As A Service Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Farming As A Service Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 16.0% from 2020-2034
Segmentation
By Service
Farm Management Solutions
Production Assistance
Access to Markets
By Delivery Model
Subscription
Pay-per-Use
By End-User
Farmers
Government
Corporate
Financial Institutions
Advisory Bodies
By Application
Yield Mapping and Monitoring
Soil Management
Crop Health Management
Navigation and Positioning
By Geography
North America
United States
Canada
Europe
Germany
UK
France
Italy
Spain
Asia Pacific
China
Japan
India
Indonesia
Australia
Latin America
Brazil
Mexico
Argentina
Middle East & Africa
Israel
GCC
South Africa
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Service
5.1.1. Farm Management Solutions
5.1.2. Production Assistance
5.1.3. Access to Markets
5.2. Market Analysis, Insights and Forecast - by Delivery Model
5.2.1. Subscription
5.2.2. Pay-per-Use
5.3. Market Analysis, Insights and Forecast - by End-User
5.3.1. Farmers
5.3.2. Government
5.3.3. Corporate
5.3.4. Financial Institutions
5.3.5. Advisory Bodies
5.4. Market Analysis, Insights and Forecast - by Application
5.4.1. Yield Mapping and Monitoring
5.4.2. Soil Management
5.4.3. Crop Health Management
5.4.4. Navigation and Positioning
5.5. Market Analysis, Insights and Forecast - by Region
5.5.1. North America
5.5.2. Europe
5.5.3. Asia Pacific
5.5.4. Latin America
5.5.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Service
6.1.1. Farm Management Solutions
6.1.2. Production Assistance
6.1.3. Access to Markets
6.2. Market Analysis, Insights and Forecast - by Delivery Model
6.2.1. Subscription
6.2.2. Pay-per-Use
6.3. Market Analysis, Insights and Forecast - by End-User
6.3.1. Farmers
6.3.2. Government
6.3.3. Corporate
6.3.4. Financial Institutions
6.3.5. Advisory Bodies
6.4. Market Analysis, Insights and Forecast - by Application
6.4.1. Yield Mapping and Monitoring
6.4.2. Soil Management
6.4.3. Crop Health Management
6.4.4. Navigation and Positioning
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Service
7.1.1. Farm Management Solutions
7.1.2. Production Assistance
7.1.3. Access to Markets
7.2. Market Analysis, Insights and Forecast - by Delivery Model
7.2.1. Subscription
7.2.2. Pay-per-Use
7.3. Market Analysis, Insights and Forecast - by End-User
7.3.1. Farmers
7.3.2. Government
7.3.3. Corporate
7.3.4. Financial Institutions
7.3.5. Advisory Bodies
7.4. Market Analysis, Insights and Forecast - by Application
7.4.1. Yield Mapping and Monitoring
7.4.2. Soil Management
7.4.3. Crop Health Management
7.4.4. Navigation and Positioning
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Service
8.1.1. Farm Management Solutions
8.1.2. Production Assistance
8.1.3. Access to Markets
8.2. Market Analysis, Insights and Forecast - by Delivery Model
8.2.1. Subscription
8.2.2. Pay-per-Use
8.3. Market Analysis, Insights and Forecast - by End-User
8.3.1. Farmers
8.3.2. Government
8.3.3. Corporate
8.3.4. Financial Institutions
8.3.5. Advisory Bodies
8.4. Market Analysis, Insights and Forecast - by Application
8.4.1. Yield Mapping and Monitoring
8.4.2. Soil Management
8.4.3. Crop Health Management
8.4.4. Navigation and Positioning
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Service
9.1.1. Farm Management Solutions
9.1.2. Production Assistance
9.1.3. Access to Markets
9.2. Market Analysis, Insights and Forecast - by Delivery Model
9.2.1. Subscription
9.2.2. Pay-per-Use
9.3. Market Analysis, Insights and Forecast - by End-User
9.3.1. Farmers
9.3.2. Government
9.3.3. Corporate
9.3.4. Financial Institutions
9.3.5. Advisory Bodies
9.4. Market Analysis, Insights and Forecast - by Application
9.4.1. Yield Mapping and Monitoring
9.4.2. Soil Management
9.4.3. Crop Health Management
9.4.4. Navigation and Positioning
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Service
10.1.1. Farm Management Solutions
10.1.2. Production Assistance
10.1.3. Access to Markets
10.2. Market Analysis, Insights and Forecast - by Delivery Model
10.2.1. Subscription
10.2.2. Pay-per-Use
10.3. Market Analysis, Insights and Forecast - by End-User
10.3.1. Farmers
10.3.2. Government
10.3.3. Corporate
10.3.4. Financial Institutions
10.3.5. Advisory Bodies
10.4. Market Analysis, Insights and Forecast - by Application
10.4.1. Yield Mapping and Monitoring
10.4.2. Soil Management
10.4.3. Crop Health Management
10.4.4. Navigation and Positioning
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Deere & Company
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Mahindra and Mahindra
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. ITC Limited
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Trimble Inc.
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. EM3 Agriservices
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Apollo Agriculture
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Accenture plc
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Taranis
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Precision Hawk
11.1.9.1. Company Overview
11.1.9.2. Products
12. Research Methodology
List of Figures
Figure 1: Farming As A Service Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Farming As A Service Market Revenue (Billion), by Service 2026 & 2034
Figure 3: North America Farming As A Service Market Revenue Share (%), by Service 2026 & 2034
Figure 4: North America Farming As A Service Market Revenue (Billion), by Delivery Model 2026 & 2034
Figure 5: North America Farming As A Service Market Revenue Share (%), by Delivery Model 2026 & 2034
Figure 6: North America Farming As A Service Market Revenue (Billion), by End-User 2026 & 2034
Figure 7: North America Farming As A Service Market Revenue Share (%), by End-User 2026 & 2034
Figure 8: North America Farming As A Service Market Revenue (Billion), by Application 2026 & 2034
Figure 9: North America Farming As A Service Market Revenue Share (%), by Application 2026 & 2034
Figure 10: North America Farming As A Service Market Revenue (Billion), by Country 2026 & 2034
Figure 11: North America Farming As A Service Market Revenue Share (%), by Country 2026 & 2034
Figure 12: Europe Farming As A Service Market Revenue (Billion), by Service 2026 & 2034
Figure 13: Europe Farming As A Service Market Revenue Share (%), by Service 2026 & 2034
Figure 14: Europe Farming As A Service Market Revenue (Billion), by Delivery Model 2026 & 2034
Figure 15: Europe Farming As A Service Market Revenue Share (%), by Delivery Model 2026 & 2034
Figure 16: Europe Farming As A Service Market Revenue (Billion), by End-User 2026 & 2034
List of Tables
Table 1: Farming As A Service Market Revenue Billion Forecast, by Service 2020 & 2034
Table 2: Farming As A Service Market Revenue Billion Forecast, by Delivery Model 2020 & 2034
Table 3: Farming As A Service Market Revenue Billion Forecast, by End-User 2020 & 2034
Table 4: Farming As A Service Market Revenue Billion Forecast, by Application 2020 & 2034
Table 5: Farming As A Service Market Revenue Billion Forecast, by Region 2020 & 2034
Table 6: North America Farming As A Service Market Revenue Billion Forecast, by Service 2020 & 2034
Table 7: North America Farming As A Service Market Revenue Billion Forecast, by Delivery Model 2020 & 2034
Table 8: North America Farming As A Service Market Revenue Billion Forecast, by End-User 2020 & 2034
Table 9: North America Farming As A Service Market Revenue Billion Forecast, by Application 2020 & 2034
Table 10: North America Farming As A Service Market Revenue Billion Forecast, by Country 2020 & 2034
Table 11: United States Farming As A Service Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 12: Canada Farming As A Service Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 13: Europe Farming As A Service Market Revenue Billion Forecast, by Service 2020 & 2034
Table 14: Europe Farming As A Service Market Revenue Billion Forecast, by Delivery Model 2020 & 2034
Table 15: Europe Farming As A Service Market Revenue Billion Forecast, by End-User 2020 & 2034
Table 16: Europe Farming As A Service Market Revenue Billion Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. What is the farming as a service market size in 2026 and 2036?
Our proprietary modeling values the global farming as a service market at USD 6.04 billion in 2026, rising to USD 26.65 billion by 2036. The 2027 estimate stands at USD 7.01 billion, implying a 16.0% CAGR over the 2027–2036 forecast period.
2. Which region dominates the farming as a service market?
North America holds the largest share at roughly 45–46%, sustained by high mechanization and a strong agricultural machinery ecosystem. Asia Pacific is the fastest-growing region, driven by smallholder access programs and digital public infrastructure such as India's Digital Agriculture Mission.
3. Which delivery model is growing fastest in farming as a service?
Subscription delivery is projected to record the highest CAGR through 2036, holding an estimated 58.7% to 65% of the delivery-model mix. Seasonal contracts of 3–4 months make subscription more economical than pay-per-use for most commercial and semi-commercial farms.
4. What share of the market do farm management solutions represent?
Farm management solutions are estimated to account for approximately 77% of farming as a service revenue by 2036. Precision farming tools within that layer alone command an estimated 55% share, supported by drone, satellite and sensor-based analytics adoption.
5. What are the main barriers to farming as a service adoption?
High initial setup costs, data privacy and security concerns, limited digital literacy and rural connectivity gaps are the principal restraints. These frictions are most acute among small-scale farmers in emerging economies, where service providers must absorb upfront technology costs.
6. Who are the leading participants in the farming as a service industry?
The landscape is fragmented, with the top five players holding only about 12% share. Participants span machinery OEMs such as Deere & Company and Mahindra and Mahindra, agri-platforms including Ninjacart, BigHaat and EM3 Agriservices, and technology firms such as IBM, Trimble and Accenture.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70–80% of the evidence base is generated through primary research: structured interviews, CATI surveys and field briefings with service providers, machinery OEMs, agri-platform operators and farm-level buyers across North America, Europe, Asia Pacific and Latin America.
Participant panels include precision-agriculture service providers, farm equipment rental and leasing operators, agri-input and agri-commerce platforms, agri-fintech and rural lending institutions, and public agricultural extension agencies.
Stakeholder interviews target roles such as Chief Operating Officer (agri-services), Head of Precision Agriculture, Farm Operations Manager, and Program Director for Digital Agriculture at government agencies.
Primary inputs are cross-checked against operational telemetry disclosed by providers, including contracted hectares, seasonal equipment utilization and subscription renewal rates.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Chief Operating Officer (Agri-Services)
30%
Head of Precision Agriculture
27%
Farm Operations Manager
25%
Program Director, Digital Agriculture
18%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Precision agriculture and drone service providers
32%
Farm equipment OEMs and rental operators
24%
Agri-input and agri-commerce platforms
18%
Agri-fintech and rural financial institutions
14%
Government and public extension agencies
12%
Secondary Research & Industry Benchmarking
20–30% of the evidence base draws on secondary research and independent benchmarking against official multilateral and governmental sources, including the FAO, OECD, World Bank, International Grains Council and national digital agriculture programs.
Standard financial databases — Bloomberg, Factiva, Hoovers and PitchBook — are used for corporate filings, funding events and competitive intelligence, supplemented by official registries at .gov and .org domains and recognized non-profit trade associations.
Key benchmarks include FAO hunger and production statistics, OECD-FAO Agricultural Outlook 2025–2034 production projections, World Bank agribusiness financing commitments and India's Digital Agriculture Mission outlay.
Every report is refreshed to the date of purchase, with figures re-validated against the latest official releases before delivery.
Demand Modeling & Market Estimation
Top-down and bottom-up methodologies are run simultaneously and reconciled through multi-level data triangulation, ensuring internal consistency between service-level, delivery-model and regional cuts.
Bottom-up modeling aggregates quantitative metrics including contracted service hectares, average annual service revenue per farm, subscription attach rates, equipment rental days per season, and installed precision-device counts per region.
Segment revenue is built from service lines (farm management solutions, production assistance, access to markets) and weighted by observed subscription versus pay-per-use mix by crop and geography.
Regional models incorporate public-program funding, mechanization indices and smallholder aggregation potential to size addressable versus served markets.
Data Accuracy & Quality Check
Estimated data accuracy is guaranteed at an 85–90% confidence level, with variance flags attached to fast-moving emerging-market estimates.
Multi-level triangulation reconciles primary interview outputs against official statistics, provider disclosures and financial database records before any figure is published.
A senior analyst review board validates CAGR assumptions, base-year anchoring and segment share logic, and applies sensitivity testing to key adoption variables.
Client-specific customization requests are routed through dedicated consultants to maintain methodological integrity across all delivered datasets.
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. IBM
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. BigHaat Agro Pvt Ltd
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. Ninjacart
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. Føn Energy Services
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. SGS Société Générale de Surveillance SA
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.1.15. 63Ideas Infolabs Private Limited
11.1.15.1. Company Overview
11.1.15.2. Products
11.1.15.3. Company Financials
11.1.15.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
Figure 17: Europe Farming As A Service Market Revenue Share (%), by End-User 2026 & 2034
Figure 18: Europe Farming As A Service Market Revenue (Billion), by Application 2026 & 2034
Figure 19: Europe Farming As A Service Market Revenue Share (%), by Application 2026 & 2034
Figure 20: Europe Farming As A Service Market Revenue (Billion), by Country 2026 & 2034
Figure 21: Europe Farming As A Service Market Revenue Share (%), by Country 2026 & 2034
Figure 22: Asia Pacific Farming As A Service Market Revenue (Billion), by Service 2026 & 2034
Figure 23: Asia Pacific Farming As A Service Market Revenue Share (%), by Service 2026 & 2034
Figure 24: Asia Pacific Farming As A Service Market Revenue (Billion), by Delivery Model 2026 & 2034
Figure 25: Asia Pacific Farming As A Service Market Revenue Share (%), by Delivery Model 2026 & 2034
Figure 26: Asia Pacific Farming As A Service Market Revenue (Billion), by End-User 2026 & 2034
Figure 27: Asia Pacific Farming As A Service Market Revenue Share (%), by End-User 2026 & 2034
Figure 28: Asia Pacific Farming As A Service Market Revenue (Billion), by Application 2026 & 2034
Figure 29: Asia Pacific Farming As A Service Market Revenue Share (%), by Application 2026 & 2034
Figure 30: Asia Pacific Farming As A Service Market Revenue (Billion), by Country 2026 & 2034
Figure 31: Asia Pacific Farming As A Service Market Revenue Share (%), by Country 2026 & 2034
Figure 32: Latin America Farming As A Service Market Revenue (Billion), by Service 2026 & 2034
Figure 33: Latin America Farming As A Service Market Revenue Share (%), by Service 2026 & 2034
Figure 34: Latin America Farming As A Service Market Revenue (Billion), by Delivery Model 2026 & 2034
Figure 35: Latin America Farming As A Service Market Revenue Share (%), by Delivery Model 2026 & 2034
Figure 36: Latin America Farming As A Service Market Revenue (Billion), by End-User 2026 & 2034
Figure 37: Latin America Farming As A Service Market Revenue Share (%), by End-User 2026 & 2034
Figure 38: Latin America Farming As A Service Market Revenue (Billion), by Application 2026 & 2034
Figure 39: Latin America Farming As A Service Market Revenue Share (%), by Application 2026 & 2034
Figure 40: Latin America Farming As A Service Market Revenue (Billion), by Country 2026 & 2034
Figure 41: Latin America Farming As A Service Market Revenue Share (%), by Country 2026 & 2034
Figure 42: Middle East & Africa Farming As A Service Market Revenue (Billion), by Service 2026 & 2034
Figure 43: Middle East & Africa Farming As A Service Market Revenue Share (%), by Service 2026 & 2034
Figure 44: Middle East & Africa Farming As A Service Market Revenue (Billion), by Delivery Model 2026 & 2034
Figure 45: Middle East & Africa Farming As A Service Market Revenue Share (%), by Delivery Model 2026 & 2034
Figure 46: Middle East & Africa Farming As A Service Market Revenue (Billion), by End-User 2026 & 2034
Figure 47: Middle East & Africa Farming As A Service Market Revenue Share (%), by End-User 2026 & 2034
Figure 48: Middle East & Africa Farming As A Service Market Revenue (Billion), by Application 2026 & 2034
Figure 49: Middle East & Africa Farming As A Service Market Revenue Share (%), by Application 2026 & 2034
Figure 50: Middle East & Africa Farming As A Service Market Revenue (Billion), by Country 2026 & 2034
Figure 51: Middle East & Africa Farming As A Service Market Revenue Share (%), by Country 2026 & 2034
Table 17: Europe Farming As A Service Market Revenue Billion Forecast, by Country 2020 & 2034
Table 18: Germany Farming As A Service Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 19: UK Farming As A Service Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 20: France Farming As A Service Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 21: Italy Farming As A Service Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 22: Spain Farming As A Service Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 23: Asia Pacific Farming As A Service Market Revenue Billion Forecast, by Service 2020 & 2034
Table 24: Asia Pacific Farming As A Service Market Revenue Billion Forecast, by Delivery Model 2020 & 2034
Table 25: Asia Pacific Farming As A Service Market Revenue Billion Forecast, by End-User 2020 & 2034
Table 26: Asia Pacific Farming As A Service Market Revenue Billion Forecast, by Application 2020 & 2034
Table 27: Asia Pacific Farming As A Service Market Revenue Billion Forecast, by Country 2020 & 2034
Table 28: China Farming As A Service Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 29: Japan Farming As A Service Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 30: India Farming As A Service Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 31: Indonesia Farming As A Service Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 32: Australia Farming As A Service Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 33: Latin America Farming As A Service Market Revenue Billion Forecast, by Service 2020 & 2034
Table 34: Latin America Farming As A Service Market Revenue Billion Forecast, by Delivery Model 2020 & 2034
Table 35: Latin America Farming As A Service Market Revenue Billion Forecast, by End-User 2020 & 2034
Table 36: Latin America Farming As A Service Market Revenue Billion Forecast, by Application 2020 & 2034
Table 37: Latin America Farming As A Service Market Revenue Billion Forecast, by Country 2020 & 2034
Table 38: Brazil Farming As A Service Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 39: Mexico Farming As A Service Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 40: Argentina Farming As A Service Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 41: Middle East & Africa Farming As A Service Market Revenue Billion Forecast, by Service 2020 & 2034
Table 42: Middle East & Africa Farming As A Service Market Revenue Billion Forecast, by Delivery Model 2020 & 2034
Table 43: Middle East & Africa Farming As A Service Market Revenue Billion Forecast, by End-User 2020 & 2034
Table 44: Middle East & Africa Farming As A Service Market Revenue Billion Forecast, by Application 2020 & 2034
Table 45: Middle East & Africa Farming As A Service Market Revenue Billion Forecast, by Country 2020 & 2034
Table 46: Israel Farming As A Service Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 47: GCC Farming As A Service Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 48: South Africa Farming As A Service Market Revenue (Billion) Forecast, by Application 2020 & 2034
 Farming As A Service Market