 Agriculture Drones Market
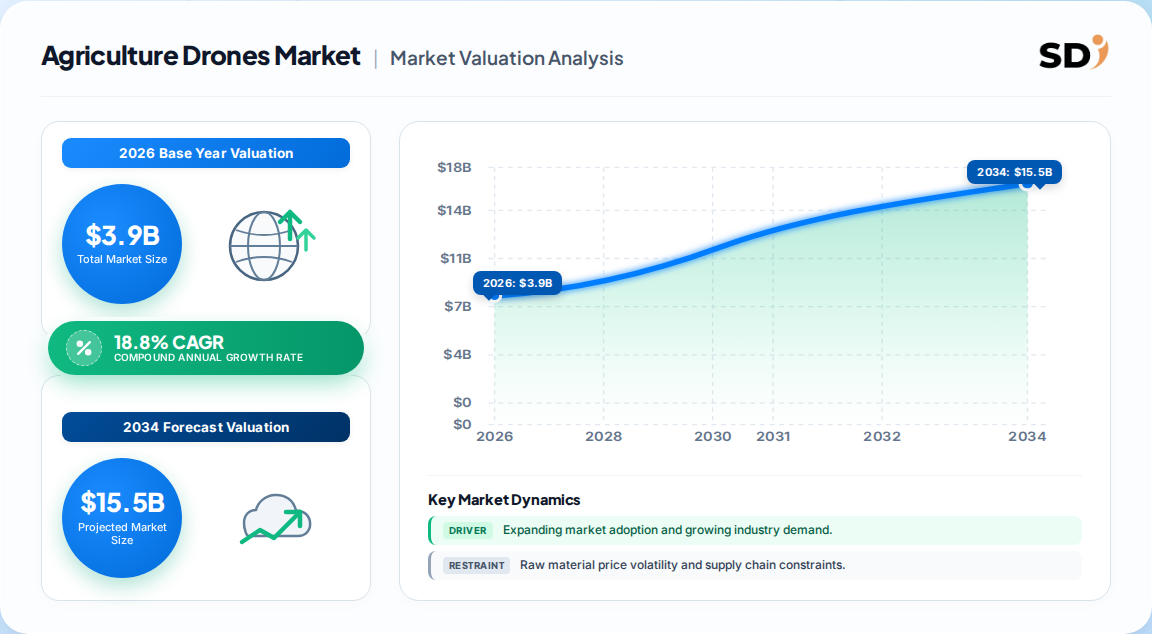
: $3.9B in 2026 to $13.2B by 2033
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 235

Atul Bhusare
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Agriculture Drones Market
Atul Bhusare
Research Associate

| Year | Market Size |
|---|---|
| 2025 | 3.400 B |
| 2026 | 3.900 B |
| 2027 | 4.600 B |
| 2028 | 5.500 B |
| 2029 | 6.500 B |
| 2030 | 7.800 B |
| 2031 | 9.200 B |

The agriculture drones market encompasses unmanned aerial vehicles (UAVs) equipped with sensors, cameras, and spraying systems used for precision farming tasks including crop monitoring, field mapping, targeted spraying, and livestock management. It spans hardware, software, and services sold to farms and service providers globally.
This analysis covers the global agriculture drones market across type (fixed-wing, rotary-wing, hybrid VTOL), component (hardware, software, services), farming environment (indoor, outdoor), and application (crop management, field mapping, crop spraying, livestock monitoring). It spans North America, Europe, Asia-Pacific, South America, and the Middle East & Africa. This analysis does not cover consumer photography drones, military UAVs, or general-purpose industrial inspection drones outside agricultural use cases.
The market is estimated at USD 3.9 billion in 2026, with forecasts ranging from USD 6.7 billion by 2035 to USD 29.5 billion by 2034, reflecting divergent assumptions on adoption speed, regulatory clarity, and service-model penetration.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 3.4B → USD 13.2B | 2025 | 2033 | 18.8% | Global, all segments included | One published estimate |
| USD 1.63B → USD 6.72B | 2025 | 2035 | 15.2% | Global, conservative hardware-led view | Competing analysis |
| USD 3.46B → USD 29.46B | 2025 | 2034 | 26.85% | Global, aggressive DaaS-inclusive view | Alternate published estimate |
Our analysis suggests the 18.8% CAGR figure is the most defensible midpoint. The 15.2% estimate likely underweights DaaS and services growth, while the 26.85% projection may overstate near-term regulatory clearances for BVLOS operations. The spread implies buyers should stress-test investment models across a 15–27% CAGR band.
The market segments by type, component, farming environment, and application, with rotary-wing drones and hardware dominating current revenue while services accelerate fastest.
| Parent Segment | Children | Leading Sub-segment (2025) |
|---|---|---|
| By Type | Fixed-Wing, Rotary-Wing, Hybrid VTOL | Rotary-Wing (61.7% share) |
| By Component | Hardware, Software, Services | Hardware (~59%), Services fastest (28% CAGR) |
| By Farming Environment | Indoor, Outdoor | Outdoor (82.3% share) |
| By Application | Crop Management, Field Mapping, Crop Spraying, Livestock Monitoring | Crop Management (24.9%) |
North America leads the global agriculture drones market with a 33.5% revenue share in 2025, driven by large-scale row-crop farming and FAA Part 107 regulatory clarity. Asia-Pacific is the fastest-growing region at a projected 17.0% CAGR.
| Region | Market Share (%) |
|---|---|
| North America | 0.34% |
| Europe | 0.24% |
| Asia-Pacific | 0.31% |
| South America | 0.07% |
| Middle East & Africa | 0.04% |
The primary growth drivers are rising agrochemical input costs, government subsidies, BVLOS regulatory liberalization, and edge AI adoption, while high upfront costs, fragmented airspace rules, and battery constraints restrain faster adoption.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Rising agrochemical input costs | Driver | High | Targeted spraying cuts chemical use 25–30% |
| Government subsidies (USDA, SMAM, Australia) | Driver | High | De-risks upfront hardware investment |
| BVLOS regulatory liberalization | Driver | Medium | Expands addressable acreage per sortie |
| Edge AI and on-board processing | Driver | Medium | Real-time crop stress classification |
| High upfront investment | Restraint | High | Delays smallholder adoption |
| Fragmented airspace regulations | Restraint | Medium | Slows cross-border scaling |
| Battery energy density limits | Restraint | Medium | Caps flight time and payload |
The balance of evidence favors growth: input-cost savings pay back hardware within two to three growing seasons, and subsidy programs in the US, India, and Australia materially lower entry barriers. However, battery and regulatory constraints mean near-term upside is concentrated in large-scale commercial farms (59% of 2025 revenue).
The competitive landscape is led by DJI and XAG in hardware and spraying platforms, with Trimble, AgEagle, Parrot, and Yamaha Motor competing across software, fixed-wing, and hybrid VTOL segments. Differentiation increasingly rests on AI analytics and service ecosystems.
| Company | Segment Focus | Key Differentiator |
|---|---|---|
| DJI | Rotary-wing, spraying, imaging | Global scale and integrated ecosystem |
| XAG | Spraying drones, smart agriculture | China and Asia-Pacific fleet leadership |
| Trimble | Software, data analytics | Precision-ag integration |
| AgEagle Aerial Systems | Fixed-wing, mapping | Sensor and analytics depth |
| Parrot SA | Multispectral imaging | European regulatory positioning |
| Yamaha Motor | Spraying (legacy & new) | Established agricultural trust |
Competitive moats are shifting from hardware specs toward software lock-in, data platforms, and service networks. Vendors lacking DaaS capability face commoditization risk as hardware margins compress.
Buyers should prioritize payload versatility, sensor accuracy, and integration with existing farm-management software, as switching costs rise sharply once data pipelines are established. Regulatory compliance — particularly BVLOS waivers and Part 107 certification — is a mission-critical selection criterion, especially for large-acreage operators. Procurement risk is concentrated in battery lifecycle costs and service-contract terms; operators should model total cost of ownership over at least three seasons. Vendors offering DaaS subscription models lower capital barriers but introduce vendor-lock-in risk that buyers must negotiate carefully.
The balance of evidence favors a services-led growth thesis. The 28% CAGR in services and the rise of DaaS models signal that value is migrating from hardware to recurring software and service revenue. Hardware-led vendors that do not build analytics or service layers risk margin compression as Chinese manufacturers scale and commoditize airframes.
The strongest counter-argument is that hardware still commands ~59% of revenue and subsidy programs primarily fund equipment purchases, not subscriptions — meaning near-term revenue remains hardware-tilted. However, this is a transitional dynamic; as BVLOS rules clarify by 2027 and edge AI matures, service models will capture disproportionate value.
Actionable Strategy:
What would change our conclusion: A prolonged stall in BVLOS rulemaking or a sharp reversal in agrochemical prices would weaken the services-led thesis and favor hardware-centric incumbents. Precise sub-segment forecasting and country-level DaaS penetration data — covered in the full report — are essential to refining these positions.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 18.8% from 2020-2034 |
| Segmentation |
|
The agriculture drones market is estimated at USD 3.9 billion in 2026, growing from USD 3.4 billion in 2025. It is projected to reach USD 13.2 billion by 2033 at an 18.8% CAGR.
North America leads with approximately 33.5% revenue share in 2025, driven by large-scale row-crop farming and FAA Part 107 regulatory clarity. Asia-Pacific is the fastest-growing region at a projected 17.0% CAGR.
Services are the fastest-growing component at a 28.0% CAGR, fueled by Drone-as-a-Service subscription models. Hybrid VTOL drones are the fastest-growing product type at 20.5% CAGR.
Leading vendors include DJI, XAG, Trimble, AgEagle Aerial Systems, Parrot SA, and Yamaha Motor. Competition is shifting from hardware specifications toward AI analytics and service ecosystems.
Rising agrochemical input costs, government subsidies, BVLOS regulatory liberalization, and edge AI adoption are the primary drivers. Targeted spraying cuts chemical use by 25–30%, delivering payback within two to three growing seasons.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study employs a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the value chain, including airframe and sensor manufacturers, software analytics providers, drone-as-a-service operators, agricultural cooperatives, and regional distributors. Decision-makers interviewed include VP-level sourcing executives, heads of R&D, technical directors, and commercial operations leads across North America, Europe, and Asia-Pacific.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 40% |
| Procurement & Sourcing Leads | 35% |
| Commercial Operations Leads | 25% |
| Company Type | Representation (%) |
|---|---|
| Drone Manufacturers & Airframe OEMs | 40% |
| Sensor & Software Providers | 30% |
| DaaS Operators & Distributors | 30% |
Secondary validation draws on official multilateral trade databases including UN Comtrade, WTO tariff schedules, US ITC data, and Eurostat agricultural machinery statistics. Corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized technical standards from FAA Part 107, EASA, and ISO are systematically reviewed to corroborate vendor and adoption claims.
Market sizing uses simultaneous top-down (macroeconomic agricultural GDP and segment allocation) and bottom-up (manufacturer capacity, unit pricing, and end-use consumption) triangulation. Forecasts apply historical CAGR regression and demand elasticity modeling across type, component, farming environment, and application segments.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |