 Europe Agricultural Tying Equipment Market
 2026
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 277

Atul Bhusare
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Europe Agricultural Tying Equipment Market
Atul Bhusare
Research Associate

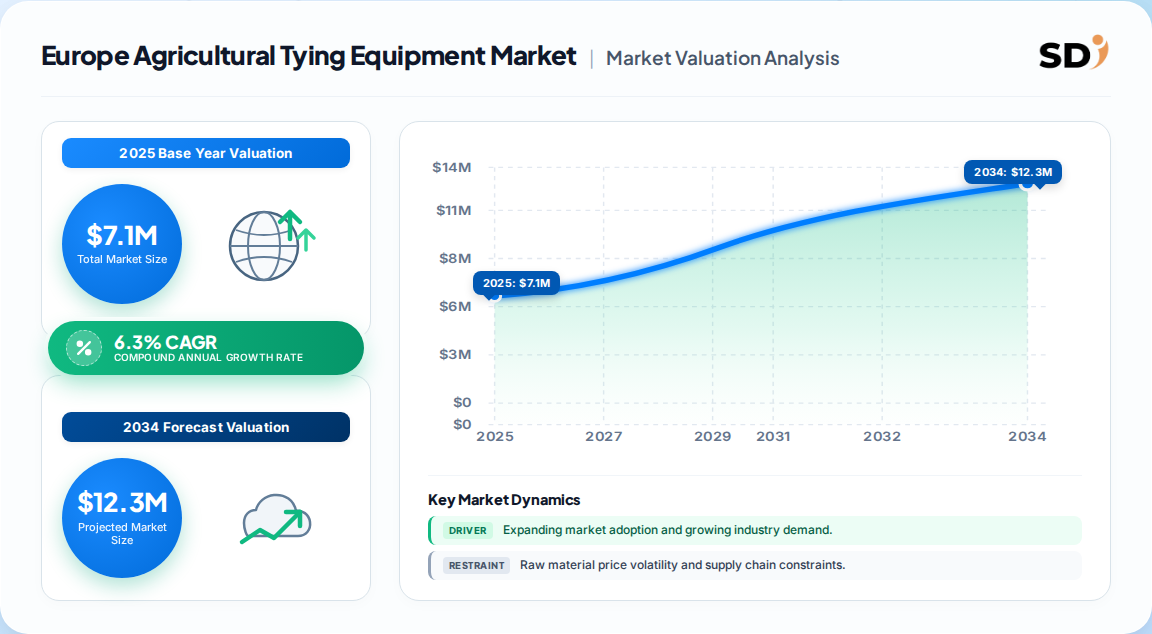
| Year | Market Size |
|---|---|
| 2025 | 7.000 M |
| 2026 | 8.000 M |
| 2027 | 8.000 M |
| 2028 | 9.000 M |
| 2029 | 9.000 M |
| 2030 | 10.00 M |
| 2031 | 10.00 M |

The Europe agricultural tying equipment market covers hand-held and battery-powered tools, tapeners and clipping devices used to fasten plants to supports, trellises and wires in greenhouses, orchards, vineyards and nurseries. It excludes twine, tape and staple consumables sold as stand-alone products, though tool-consumable compatibility is a central purchasing criterion.
This analysis covers equipment hardware — manual tying tools, battery-operated tapeners, clipping tools and their chargers, batteries and spare parts — sold to professional growers across European countries. Segment splits follow type, operation mode and crop. This analysis does not cover loose agricultural twine and netting, general-purpose power tools, full greenhouse structure systems, or tractor-mounted mechanization.
Scope matrix
| Dimension | Included | Excluded |
|---|---|---|
| Product | Tying tools, tapeners, clipping tools, batteries, chargers | Twine, tape, netting as stand-alone |
| Operation | Manual, battery-operated | Tractor-mounted systems |
| Crop | Tomato, bell pepper, vine, nursery | Arable field crops |
| Buyer | Commercial growers, horticultural contractors | Household gardeners |
The most defensible reading puts the market at USD 7.1 million in 2025, rising to USD 7.5 million in 2026 and USD 11.6 million by 2033 — a 6.3% CAGR. A second, widely circulated estimate claims USD 4.9 billion growing at 12.2%, which is not reconcilable with the equipment category described.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 7.1M → USD 11.6M | 2025 | 2033 | 6.3% | Hand-held tying/clipping tools, Europe only | One published estimate (specialist) |
| USD 4.9B → USD 12.3B | 2025 | 2033 | 12.2% | Self-described "Europe" figure with global-narrative text | A competing analysis |
| USD 159.4B (global farm equipment) | 2025 | 2035 | 5.3% | All farm machinery worldwide — contextual only | A competing analysis |
Our analysis suggests the USD 7.1 million base is credible: a niche tool category serving greenhouse horticulture across a handful of countries cannot plausibly reach billions. The billion-scale figure appears to be a template artifact — its own text describes North America and Asia-Pacific as key regions, contradicting a Europe-only scope. Buyers should anchor on the low-base, 6.3% trajectory.
Segmentation matters because growth is uneven: crop mix determines tying frequency, and operation mode determines unit price and aftermarket revenue. Tomato dominates volume; battery operation dominates value growth.
| Parent | Children | 2025 signal |
|---|---|---|
| Type | Tying tools/tapeners, clipping tools | Clipping tools ~5.9% CAGR |
| Operation | Manual, battery-operated | Manual ~3.9% CAGR; battery drives value |
| Crop | Tomato, bell pepper, vine, nursery, other | Tomato 58.4% share |
| Component | Tools, batteries, chargers, spares | Spares support recurring revenue |
The Netherlands leads with 18.3% of 2025 revenue, reflecting its dense glasshouse horticulture base. Southern and Western European protected-cultivation economies follow, with adoption tracking greenhouse area and labor cost rather than total farmland.
| Country | Est. 2025 share | Primary crop driver |
|---|---|---|
| Netherlands | 18.3% | Glasshouse tomato, pepper |
| Spain | ~15% | Almería protected vegetables |
| Italy | ~14% | Tomato, nursery, vineyard |
| France | ~12% | Protected vegetables, nursery |
| Germany | ~10% | Horticulture, nursery |
| Poland | ~8% | Protected vegetables, expansion |
This divergence implies a concentrated addressable base: five countries likely account for roughly two-thirds of revenue. Vendors should build dealer density there before expanding eastward.
Labor availability is the binding constraint. Where seasonal workers are scarce or costly, battery tapeners pay back within a season through faster per-plant tying; where farms are small and fragmented, the upfront tool-plus-battery cost does not clear the hurdle.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Labor scarcity in horticulture | Driver | Strong | Faster tying per worker; reduced seasonal headcount |
| Protected cultivation expansion | Driver | Strong | More plants requiring support per hectare |
| Battery tool adoption | Driver | Moderate–strong | Portability, consistent tension, less crop damage |
| Ergonomic/lightweight design | Opportunity | Moderate | Extends usable hours; lowers injury risk |
| Small, fragmented farms | Restraint | Strong | Low tying volume cannot justify capex |
| Input and battery cost volatility | Restraint | Moderate | Raises unit price; delays replacement |
The balance favors mechanization, but adoption will be tiered. Commercial glasshouse operations with high tying frequency will convert first; smaller growers will stay manual until compact, lower-cost entry tools arrive. That gap is the single largest untapped pool of demand.
No vendor holds a dominant share. The field splits between specialized tying-tool manufacturers, agricultural fastening suppliers and regional dealers, with competition decided by tool-consumable compatibility, battery runtime and dealer service reach.
| Vendor archetype | Typical strength | Moat | Watch-out |
|---|---|---|---|
| Specialized tying-tool makers | Crop-specific mechanisms | Consumable compatibility | Narrow product range |
| Agricultural fastening suppliers | Broad accessory portfolio | Dealer relationships | Less ergonomic focus |
| Regional distributors | Local service, spares | Proximity and trust | Limited R&D |
| General power-tool entrants | Battery platforms | Scale in cells | Weak horticultural fit |
Differentiation rests on the consumable interface. Once a grower standardizes on a clip or tape format, switching costs rise sharply — tool replacement plus retraining plus re-stocking. Our analysis suggests consumable lock-in, not hardware margin, is where durable profit sits.
Selection should be driven by total cost per 1,000 ties, not sticker price. Buyers should benchmark battery runtime across a full shift, clip/tape compatibility, spare-part lead times and dealer proximity, because a failed tool during peak tying season is far costlier than a higher purchase price.
Procurement risks concentrate in three areas: battery supply and replacement cost, single-source consumable dependence, and seasonal service bottlenecks. Regulatory exposure is modest but real — machinery safety, worker-protection rules and battery transport/disposal obligations all apply. Ergonomic documentation is increasingly requested in tenders, and growers should insist on trial periods during peak season before fleet-wide conversion.
The balance of evidence favors a tiered mechanization thesis: steady, unspectacular 6.3% growth concentrated in glasshouse tomato and pepper operations across the Netherlands, Spain, Italy and France. The strongest counter-argument is that small-farm fragmentation could cap adoption well below forecast — plausible if battery and tool prices stay elevated. We weight this as a timing risk, not a structural one, because labor scarcity keeps pushing payback periods shorter.
For decision-makers, the strategic implication is scale discipline. A sub-USD 12 million market rewards focused execution: own the consumable standard in two or three crops, and let adjacent crops follow. Vendors chasing broad portfolios will dilute service quality precisely where growers are most sensitive.
Actionable strategy
What would change our conclusion: a sharp fall in battery costs, or EU labor rules materially tightening seasonal-worker availability, would pull forward adoption and push growth above 6.3%. Conversely, sustained input-cost inflation without financing support would delay conversion among smaller growers.
| Region | Market Share (%) |
|---|---|
| Netherlands | 0.18% |
| Spain | 0.15% |
| Italy | 0.14% |
| France | 0.12% |
| Germany | 0.1% |
| Poland | 0.08% |
| Greece | 0.06% |
| Belgium | 0.05% |
| Portugal | 0.04% |
| Rest of Europe | 0.08% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.3% from 2020-2034 |
| Segmentation |
|
The market was valued at USD 7.1 million in 2025 and an estimated USD 7.5 million in 2026. It is projected to reach USD 11.6 million by 2033, growing at a 6.3% CAGR over the forecast period.
The Netherlands led with 18.3% revenue share in 2025, driven by dense glasshouse tomato and pepper cultivation. Spain, Italy, France and Germany follow, with adoption tracking protected-cultivation area and horticultural labor costs.
Tomato accounted for 58.4% of total market revenue in 2025. It is the highest-frequency tying crop in European protected cultivation, followed by bell pepper, vine and nursery applications across Southern and Western Europe.
Yes, though gradually. Battery-operated tapeners drive value growth because they cut tying time per plant and reduce seasonal labor dependence, while the manual segment grows at only about 3.9% CAGR as smaller farms retain conventional methods.
Small, fragmented farm structures and tight profitability constrain uptake. Where tying volumes are low, the upfront cost of tools, batteries, chargers and consumables is hard to justify, so mechanization concentrates in commercial glasshouse operations.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research program applies a 70/30 primary-to-secondary split. In-depth interviews were conducted across the tying-equipment value chain, including component and battery suppliers, specialized tying-tool and clip manufacturers, horticultural consumable producers, and agricultural dealer-distributor networks. Decision-makers interviewed include Heads of Product Development, Commercial Operations Leads, Procurement and Sourcing Directors, and Technical Service Managers responsible for grower support in protected cultivation.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Product & Technical Development Heads | 38% |
| Commercial Operations Leads | 30% |
| Procurement & Sourcing Directors | 20% |
| Grower Service Managers | 12% |
| Company Type | Representation (%) |
|---|---|
| Tying-Tool & Clip Manufacturers | 42% |
| Component & Battery Suppliers | 24% |
| Agricultural Dealers & Distributors | 22% |
| Horticultural Grower Operations | 12% |
Findings were cross-checked against official multilateral trade databases (UN Comtrade, Eurostat), corporate annual filings and investor presentations, patent and design registrations for tying mechanisms, and recognized technical standards and industry associations governing agricultural machinery safety and battery handling.
We run simultaneous top-down and bottom-up models. The top-down path allocates macroeconomic horticultural output and greenhouse area to tying-equipment spend; the bottom-up path models manufacturer capacity, unit pricing, replacement cycles and consumable attachment rates by crop and country.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Country share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |