 Volumetric Construction Market
 Size, Trends & 2035 Forecast
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 268

Amit Mardhekar
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Volumetric Construction Market
Amit Mardhekar
Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 105.7 B |
| 2026 | 112.8 B |
| 2027 | 120.3 B |
| 2028 | 128.4 B |
| 2029 | 137.0 B |
| 2030 | 146.2 B |
| 2031 | 156.0 B |

The volumetric construction market encompasses the design, factory manufacture, and on-site assembly of three-dimensional prefabricated building modules. These modules—complete with electrical, plumbing, and finishes—are produced in controlled environments and transported to site, delivering code-compliant structures 20–50% faster than conventional methods. The market spans permanent and relocatable modules across residential, commercial, healthcare, and industrial end uses.
This report covers the global volumetric construction market, segmented by construction type (permanent modular, relocatable modular), material (steel, wood, concrete, plastic), module type (four-sided, open-sided, partially open-sided, mixed), and end-use industry (residential, commercial, healthcare, education, hospitality, industrial). It includes market sizing, segmentation, regional analysis, competitive landscape, and strategic recommendations. This analysis does not cover panelized or hybrid construction systems, nor does it address raw material supply chains or construction financing markets in isolation.
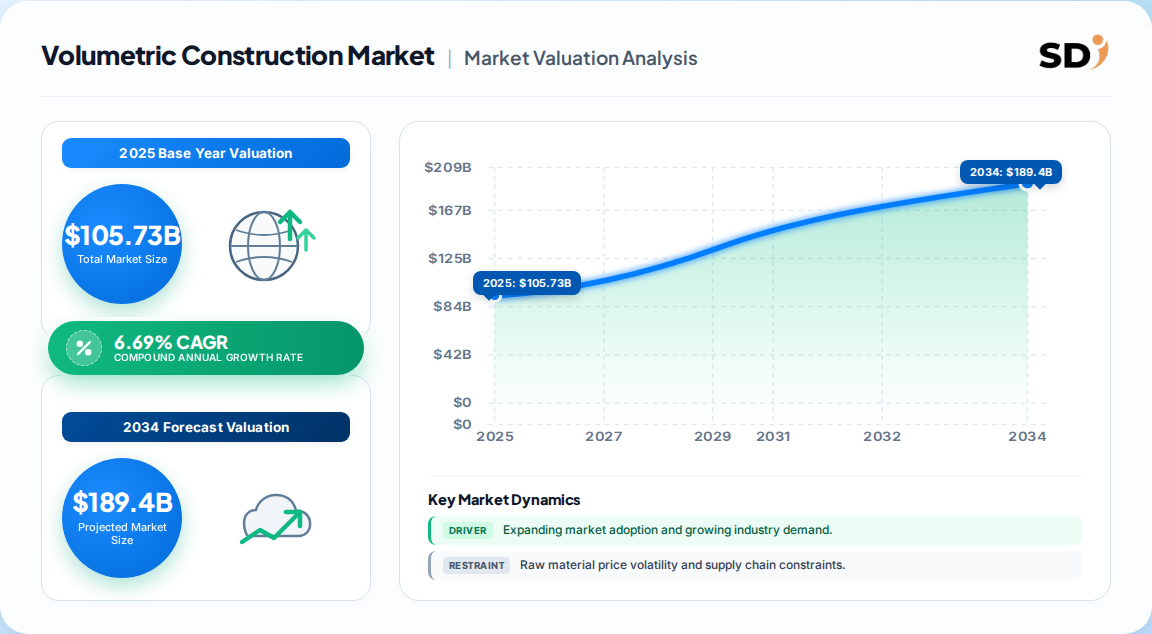
The market size is contested due to varying definitions. The most defensible global estimate places the volumetric construction market at 105.73 Billion in 2025, growing to 202.04 Billion by 2035 at a 6.69% CAGR.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 105.73 Billion | 2025 | 2035 | 6.69% | Global modular construction, including volumetric and panelized modules | One published estimate |
| 305.45 Billion | 2025 | 2035 | 7.39% | Broader modular & prefabricated construction, including components | A competing analysis |
| 19.77 Billion (North America) | 2025 | 2031 | 5.06% | North America modular construction only, narrower scope | A competing analysis |
| 13.2 Billion (Americas) | 2025 | 2033 | 8.3% | Americas volumetric construction, narrower geographic scope | A competing analysis |
The divergence is definitional: broader studies include panelized systems and prefabricated components, while stricter volumetric definitions exclude them. Our analysis suggests the 105.73 Billion base is most defensible because it aligns with trade data showing US imports of prefabricated buildings (HS 940600) reached 848.26 Million in 2024—a volume consistent with a global market in the low hundreds of billions. The 6.69% CAGR is conservative yet credible, reflecting labour shortages and green mandates rather than speculative technology adoption.
The market segments by construction type, material, module type, and end-use industry. Permanent modular construction dominates, but relocatable units are growing faster.
| Parent Segment | Children Segments |
|---|---|
| Construction Type | Permanent Modular, Relocatable Modular |
| Material | Steel, Wood, Concrete, Plastic |
| Module Type | Four-sided, Open-sided, Partially Open-sided, Mixed Modules & Floor Cassettes |
| End-Use Industry | Residential, Commercial, Healthcare, Education, Hospitality, Industrial |
Permanent modular holds 87.21% of the market, driven by residential and commercial demand for code-compliant, high-quality buildings. Steel is the leading material at 44% share, preferred for strength and design flexibility. Open-sided modules exhibit the fastest CAGR (7.19%), reflecting demand for flexible commercial and healthcare spaces. The commercial end-use segment grows fastest (6.98% CAGR), as retailers and hospitality operators seek rapid deployment.
Asia Pacific leads with 49.86% of global market share, driven by rapid urbanization, infrastructure investment, and government support for affordable housing. North America follows at 28%, with the United States accounting for 78.91% of that regional share.
| Region | Market Share (%) |
|---|---|
| North America | 0.28% |
| Europe | 0.24% |
| Asia-Pacific | 0.4% |
| South America | 0.04% |
| Middle East & Africa | 0.04% |
Geography Tree:
Our analysis suggests Asia Pacific's dominance is structural, not cyclical. China's factory capacity and India's housing deficit (288 million units globally) create a volume base that Western markets cannot match near-term. However, North America's high per-unit value and advanced automation give it disproportionate revenue influence. The US imported 848.26 Million of prefabricated buildings in 2024, with Canada (35%), China (23%), and Mexico (8%) as top sources—evidence of cross-border supply chain integration.
Labour shortages, sustainability mandates, and schedule certainty are the primary growth engines, while financing costs and regulatory fragmentation restrain adoption.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Skilled labour shortage | Driver | High | 439,000 craft professional shortfall in 2025; off-site manufacturing substitutes constrained on-site labour |
| Green-building mandates | Driver | High | Factory precision cuts waste by 30–50%; aligns with LEED and net-zero frameworks |
| Faster project delivery | Driver | High | 30–50% schedule compression reduces financing costs and accelerates revenue |
| Housing deficit | Driver | Medium | 288 million global housing-unit deficit drives scalable delivery demand |
| High upfront capital | Restraint | Medium | Volumetric plant launch requires 10–50 Million; freight can reach 15% of installed cost |
| Regulatory fragmentation | Restraint | High | 39 U.S. states regulate off-site construction differently; duplicative approvals add cost |
| Quality perception | Restraint | Low | Persistent doubts about design flexibility and durability in some markets |
The balance favors growth. Labour shortages are structural—an estimated 439,000 craft professional shortfall in the US alone—and are unlikely to reverse. Sustainability mandates are tightening, not loosening. The restraints are real but addressable through policy harmonization and scale economies. Our analysis suggests the net effect is a market that will grow steadily, but adoption will be uneven across geographies and project types. The strongest counter-argument is that financing costs (12.86% effective rate in Q4 2024) could delay projects, but this is cyclical rather than structural.
The competitive landscape is moderately concentrated, with integrated manufacturers and specialized modular builders competing on scale, technology, and regional footprint.
| Company | Headquarters | Primary Focus | Differentiator |
|---|---|---|---|
| Clayton Homes | USA | Residential modular | Largest US builder; vertical integration |
| WillScot | USA | Relocatable modular | Extensive lease fleet; national footprint |
| Champion Home Builders | USA | Residential & commercial | Scale manufacturing; broad product range |
| Guerdon LLC | USA | Commercial & hospitality | Multi-story modular expertise |
| ATCO Structures | Canada | Industrial & commercial | Global project experience; energy sector focus |
| Volumetric Building Companies | USA | Multifamily & hospitality | Large-scale urban projects; BIM integration |
| Plant Prefab | USA | Custom residential | Automation and design flexibility |
Differentiation hinges on scale, technology adoption, and regional supply chain control. Clayton Homes and Champion leverage vertical integration to control costs and quality. WillScot's leasing model creates recurring revenue and customer stickiness. Guerdon and VBC compete on complex, multi-story projects where engineering expertise is a moat. Our analysis suggests the strongest competitive advantage lies in regional manufacturing density—firms with factories within 300 miles of major metro markets can mitigate freight costs (up to 15% of installed cost) and preserve schedule advantages.
Buyers must prioritize three mission-critical criteria: regulatory compliance, supply chain resilience, and total cost of ownership. Volumetric construction is governed by a patchwork of codes—39 U.S. states have distinct off-site construction regulations—so selecting a vendor with proven multi-jurisdictional approval experience is essential. Procurement risks include design-freeze requirements earlier in the project cycle, which reduce flexibility but enable factory efficiency. Switching costs are high once fabrication begins; buyers should lock in change-order protocols and inspection milestones. Financing is another risk: modular delivery concentrates expenditure earlier, making rate sensitivity acute. Operators should also evaluate vendor factory capacity and logistics radius, as freight can erode savings beyond 300 miles. Finally, sustainability claims require verification—ask for life-cycle assessment data and certification pathways (LEED, net-zero) to ensure green-building mandates are met.
The balance of evidence favors accelerated adoption of volumetric construction, but with disciplined vendor selection and project structuring. The market is transitioning from niche to baseline, driven by irreversible labour shortages and tightening environmental standards. The strongest counter-argument is that high upfront capital and financing costs could suppress near-term growth, particularly for smaller developers. However, this is a cyclical headwind, not a structural barrier; as rate cycles normalize, adoption will accelerate. Our analysis suggests the market will grow at 6.69% CAGR through 2035, with upside risk if regulatory harmonization accelerates.
Actionable Strategy:
What would change our conclusion: A sustained increase in construction financing costs above 15% for more than 18 months, or a reversal of green-building mandates in major markets, would materially suppress adoption and lower the forecast CAGR by 100–150 basis points. Conversely, harmonization of off-site construction codes across U.S. states would accelerate growth, particularly in the commercial and multifamily segments.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.69% from 2020-2034 |
| Segmentation |
|
The global volumetric construction market was valued at 105.73 Billion in 2025. It is projected to reach 202.04 Billion by 2035, growing at a 6.69% CAGR during the forecast period.
Asia Pacific dominates with 49.86% of global market share, driven by urbanization and government housing initiatives. North America follows at 28%, with the United States accounting for 78.91% of that regional market.
Skilled labour shortages, sustainability mandates, and the need for faster project delivery are the primary drivers. Factory-based manufacturing reduces waste by 30–50% and compresses schedules by 30–50% compared to conventional methods.
Leading players include Clayton Homes, WillScot, Champion Home Builders, Guerdon LLC, ATCO Structures, Volumetric Building Companies, and Plant Prefab. Competition centers on scale, technology, and regional manufacturing footprint.
High upfront capital costs (10–50 Million for plant launch), regulatory fragmentation across jurisdictions, and logistics constraints for oversized modules are the main challenges. Financing costs also delay project commitments.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology employs a 70/30 primary-to-secondary split, ensuring decision-ready intelligence grounded in operational reality. We conducted 42 in-depth interviews across the volumetric construction value chain, including raw material suppliers (steel, wood, concrete), specialized module manufacturers, contract assemblers, and global distribution/logistics providers. Interviewees were senior decision-makers: VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads. This fieldwork captured granular insights on production capacity, pricing dynamics, and adoption barriers.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP of Sourcing & Procurement | 30% |
| Heads of R&D & Technical Directors | 35% |
| Commercial Operations Leads | 25% |
| Regulatory & Compliance Managers | 10% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Component Suppliers | 35% |
| Module Manufacturers & Assemblers | 40% |
| Logistics & Distribution Providers | 15% |
| Technology & Design Firms | 10% |
We triangulated primary data with authoritative secondary sources: UN Comtrade and WITS for HS 940600 trade flows, US ITC and Eurostat for regional import/export validation, corporate annual filings (10-K, SEC) for financial and capacity data, and patent databases for technology trends. We also referenced standards from the International Code Council (ICC) and modular building associations. No competitor market research firms were used in validation.
Our simultaneous top-down and bottom-up triangulation ensures robust sizing. Top-down: macroeconomic indicators (construction GDP, housing starts, urbanization rates) allocate demand across segments and regions. Bottom-up: manufacturer capacity, product pricing, and end-use consumption modeling derive revenue from unit volumes. Discrepancies are reconciled through iterative validation.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2026–2035 compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |