 Automotive Flooring Market
 Size, CAGR & Forecast 2026
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 273

Amit Mardhekar
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Automotive Flooring Market
Amit Mardhekar
Research Analyst

| Year | Market Size |
|---|---|
| 2024 | 38.30 B |
| 2025 | 39.80 B |
| 2026 | 41.20 B |
| 2027 | 42.80 B |
| 2028 | 44.40 B |
| 2029 | 46.00 B |
| 2030 | 47.70 B |

The automotive flooring market covers carpets, mats, trunk liners, and cargo-floor systems installed in passenger cars and commercial vehicles. These components deliver acoustic insulation, vibration damping, thermal protection, abrasion resistance, and interior aesthetics. The category spans OEM fitment and the aftermarket, and is defined by material systems, manufacturing processes, and vehicle-class-specific performance standards.
This analysis covers global OEM and aftermarket automotive flooring across passenger cars, light commercial vehicles, and heavy commercial vehicles, segmented by material (polyurethane, polypropylene, nylon, rubber, others), product (carpets, mats, trunk/cargo systems), and manufacturing process. It includes demand-side drivers, regulatory standards such as FMVSS 302, and vendor positioning. This analysis does not cover automotive seating, headliners, insulation blankets sold as standalone NVH products, or non-automotive carpet and mat applications.
The most defensible global figure for 2026 is 41.2 Billion, anchored to approximately 99.8 million global vehicle units sold in 2025 and consistent per-vehicle flooring content. Competing published estimates diverge by more than an order of magnitude, largely because of scope and unit errors, not genuine demand differences.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 41.2 Billion | 2026 | 2033 (53.3 Billion) | 3.7% | Full flooring: carpets, mats, trunk systems, OEM + aftermarket | One published estimate |
| 2.03 Billion | 2026 | 2034 (1.02 Billion) | 8.0% | Ambiguous scope; internally inconsistent base vs. forecast | A competing analysis |
| 9.03 Billion | 2025 | 2034 (13.45 Billion) | 4.5% | Flooring systems, narrower materials set | A competing analysis |
| 7.06 Billion | 2025 | 2035 (13.89 Billion) | 7.0% | Automotive carpet only, excluding mats | A competing analysis |
Our analysis suggests the 41.2 Billion figure is the most defensible because it survives a volume cross-check: at roughly 90 million light vehicles produced annually and 400-520 USD of flooring content per vehicle, implied revenue lands near 40-47 Billion. The 2.03 Billion estimate fails internal consistency, since its forecast value is lower than its base. The 7.06 Billion figure is credible only as a carpet-only subset, and the 9.03 Billion estimate likely excludes aftermarket and trunk systems.
Segmentation follows material, product, vehicle application, and manufacturing process. Material selection is the primary cost and performance lever, while product and vehicle class determine volume and specification complexity.
| Parent segment | Children |
|---|---|
| Material | Polyurethane, Polypropylene, Nylon, Rubber, Others (PVC, polyester, recycled polymers) |
| Product | Carpets, Mats, Trunk & cargo flooring |
| Application | Passenger cars, Light commercial vehicles, Heavy commercial vehicles |
| Manufacturing process | Tufted, Needle-punched, Compression molded / thermoformed, Injection molded |
| Channel | OEM, Aftermarket |
Nylon leads on abrasion resistance and moldability (~25% share), while polypropylene dominates on cost in volume programs. Our analysis suggests the fastest value migration is toward polyurethane and thermoplastic elastomers in EVs, where underfloor battery packaging demands thermal and acoustic performance that traditional needled carpets cannot deliver alone.
Asia Pacific leads with roughly 48% of global revenue, driven by vehicle assembly concentration in China, India, Japan, and South Korea. North America is the fastest-growing region on reshored EV and battery-linked assembly capacity, while Europe holds the second-largest share on premium and luxury mix.
| Region | Market Share (%) |
|---|---|
| North America | 0.22% |
| Europe | 0.24% |
| Asia-Pacific | 0.48% |
| South America | 0.04% |
| Middle East & Africa | 0.03% |
| Parent region | Countries covered |
|---|---|
| Asia Pacific | China, Japan, India, South Korea, Australia, Rest of Asia Pacific |
| Europe | Germany, UK, France, Italy, Spain, Rest of Europe |
| North America | USA, Canada, Mexico |
| South America | Brazil, Argentina, Rest of South America |
| Middle East & Africa | Saudi Arabia, UAE, South Africa, Rest of MEA |
| Region | 2025 revenue share |
|---|---|
| Asia Pacific | 48% |
| Europe | 24% |
| North America | 22% |
| South America | 3.5% |
| Middle East & Africa | 2.5% |
The Asia Pacific concentration implies sourcing risk: a single-region supply shock in needled carpet capacity would propagate globally within two model years. North America's growth premium, meanwhile, is a localization signal, not a demand signal, and suppliers should read it as a procurement invitation rather than a volume windfall.
Growth is propelled by rising global vehicle sales (99.8 million units in 2025, up 4.7% year on year per OICA), premiumization of interiors, EV acoustic requirements, and tightening flammability rules. Restraints center on raw-material cost volatility and price pressure from OEMs.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Global vehicle sales growth | Driver | High | Direct content-per-vehicle volume pull |
| EV acoustic and thermal needs | Driver | High | Underfloor battery packaging requires new insulation layers |
| Interior premiumization and customization | Driver | Medium-High | Higher content per vehicle in premium trims |
| FMVSS 302 and equivalent standards | Driver | Medium | Forces compliant, often costlier materials |
| Raw material price volatility | Restraint | High | Compresses Tier-2 margins; triggers re-sourcing |
| OEM cost-down pressure | Restraint | High | Limits value capture despite volume growth |
| Aftermarket growth | Driver | Medium | Replacement mats and carpets add recurring revenue |
The balance of evidence favors volume-led growth over price-led growth. Our analysis suggests that with only 3.7% CAGR, value gains will come from content per vehicle, not unit expansion, so suppliers that cannot raise content per platform will face structural margin compression even as revenue grows.
The vendor landscape is moderately concentrated at the Tier-1 level, with acoustic and interior system integrators holding platform-level contracts and regional specialists serving local OEMs and the aftermarket. Differentiation rests on material engineering, NVH integration, and global footprint.
| Company | HQ / region | Primary positioning |
|---|---|---|
| Autoneum Holding | Switzerland | Global acoustic and thermal systems, EV-focused flooring |
| Adler Pelzer Holding | Germany | Broad interior systems, high European OEM penetration |
| Auria Solutions | USA | North American carpets and acoustic systems |
| Toyota Boshoku | Japan | Integrated interior systems, Japanese OEM anchor |
| Hayashi Telempu | Japan | Carpets and interior materials, Asia-centric |
| UGN Inc. | USA | Acoustic flooring and NVH components |
| Suminoe Textile | Japan | Carpet and textile systems |
| 3M | USA | Aftermarket mats and specialty materials |
Competitive moats are built on platform nomination cycles of three to five years, co-development with OEM acoustic teams, and localized manufacturing near assembly plants. Our analysis suggests the strongest moat is not material IP but qualification lock-in: once a flooring system is validated for a platform, switching costs rise sharply for the life of that program.
Buyers should prioritize suppliers that can meet FMVSS 302 and equivalent regional flammability standards while delivering measurable NVH performance and recyclability. Total cost of ownership matters more than piece price: a cheaper mat that fails abrasion or odor testing creates warranty and re-validation costs that dwarf initial savings.
Procurement risk concentrates in single-source needled carpet supply and in raw-material index exposure for polyurethane and nylon. Switching costs are high mid-program, so qualification should begin 18-24 months before SOP. Our analysis implies that dual-sourcing by material family, not by identical part, provides the best resilience at acceptable cost.
Regulatory compliance is non-negotiable and increasingly extends to recycled content disclosure and VOC limits. Operators should build material traceability into contracts now, because EU and North American sustainability reporting requirements are tightening through 2029.
The balance of evidence favors a content-led growth thesis over a volume-led one. With the market growing at only 3.7% CAGR, the winners will be suppliers who raise value per vehicle through NVH integration, mono-material recyclable designs, and EV-specific thermal solutions, rather than those chasing unit share in commoditized mats.
The strongest counter-argument is that higher published growth rates (7-8%) reflect genuine carpet premiumization, and that the full market may compound faster than 3.7% if EV interior re-specification accelerates. We acknowledge this possibility, but the volume cross-check against 99.8 million vehicle sales constrains the upside: even aggressive content growth cannot lift a 40-Billion base to a double-digit CAGR without implausible per-vehicle spending.
The evidence that would change our conclusion is a sustained rise in per-vehicle flooring content above 600 USD, or a regulatory mandate for recycled content that resets qualification barriers in favor of incumbents.
[Gap note: this overview covers the aggregate market and principal segments. Precise sub-segment forecasting by material-vehicle-class combination, and platform-level vendor share, requires the full report's granular modeling.]
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 3.7% from 2020-2034 |
| Segmentation |
|
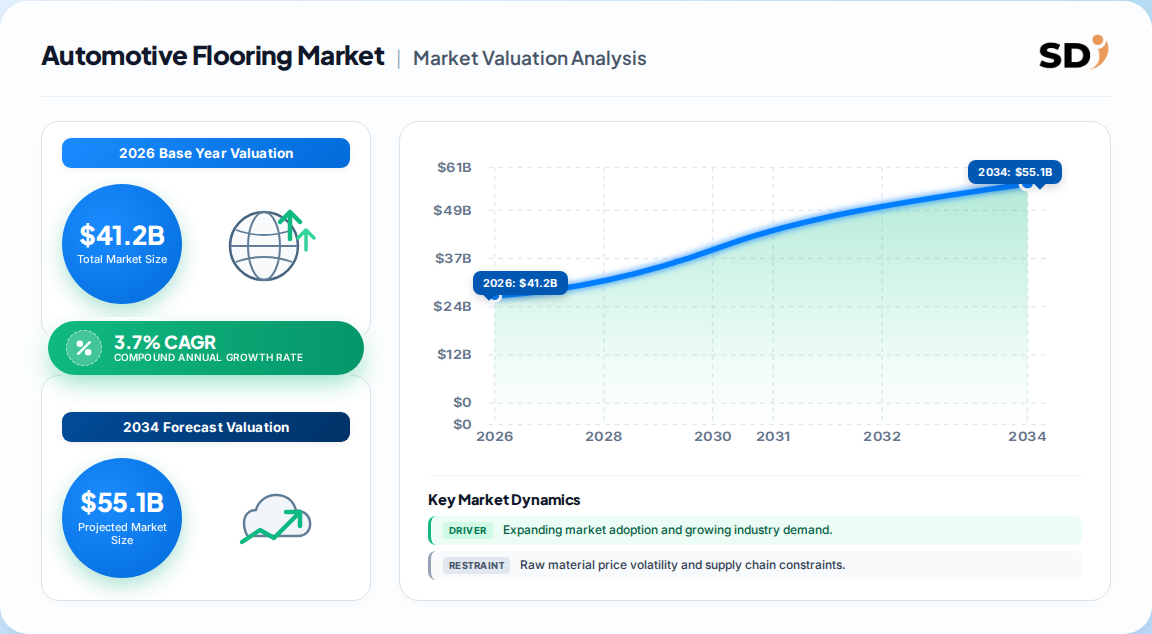
The global automotive flooring market is approximately 41.2 Billion in 2026. This figure covers carpets, mats, and trunk systems across passenger and commercial vehicles, and is the most defensible estimate after cross-checking against global vehicle production volumes.
The market is projected to grow at a 3.7% CAGR from 2026 to 2033, reaching 53.3 Billion by 2033. Higher published growth rates typically reflect narrower carpet-only or mat-only definitions rather than faster underlying demand.
Nylon leads with roughly 25% revenue share, valued for abrasion resistance and moldability. Polyurethane is the fastest-growing material, driven by acoustic insulation and thermal needs in electric vehicles.
Asia Pacific dominates with approximately 48% of global revenue, led by China, India, Japan, and South Korea. North America is the fastest-growing region, supported by reshored EV and battery-linked assembly capacity.
Leading suppliers include Autoneum, Adler Pelzer, Auria Solutions, Toyota Boshoku, Hayashi Telempu, UGN, Suminoe, and 3M. Competition centers on platform nominations, NVH integration, and localized manufacturing near assembly plants.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain with raw-material suppliers (polyurethane, polypropylene, nylon fiber), specialized flooring and carpet producers, contract acoustic-system integrators, and global interior-system distributors. Decision-maker designations interviewed include VP-level Sourcing leads, Heads of Interior R&D, Technical Directors for NVH and materials, and Commercial Operations Leads at Tier-1 and Tier-2 suppliers. Interview programs targeted platform nomination history, material substitution patterns, and qualification timelines.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Sourcing & Procurement Leads | 35% |
| Interior R&D & Technical Directors | 35% |
| Commercial Operations Leads | 18% |
| Quality & Regulatory Compliance | 12% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Fiber Producers | 42% |
| Specialized Flooring & Carpet Producers | 33% |
| Acoustic System Integrators | 15% |
| Distributors & Aftermarket Suppliers | 10% |
Secondary validation draws on official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings and investor presentations (10-K, SEC filings), patent databases for flooring and acoustic material innovation, and recognized technical standards bodies and industry associations. Vehicle production and sales benchmarks are cross-referenced against OICA statistics and national automotive association reporting.
Simultaneous top-down and bottom-up modeling is applied. Top-down allocation uses macroeconomic vehicle production and interior-content spending by segment and region. Bottom-up modeling uses manufacturer capacity, product pricing, and end-use consumption by vehicle class. Divergences between the two approaches are reconciled through weighted triangulation anchored to physical unit volumes.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |