 Italy Retail Vending Machine Market
 Outlook 2025
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 239

Vijayashree Ugale
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Italy Retail Vending Machine Market
Vijayashree Ugale
Research Analyst
| Year | Market Size |
|---|---|
| 2024 | 2.480 B |
| 2025 | 2.590 B |
| 2026 | 2.710 B |
| 2027 | 2.830 B |
| 2028 | 2.960 B |
| 2029 | 3.090 B |
| 2030 | 3.230 B |

The Italy retail vending machine market covers self-service automated retail equipment and the product sales transacted through it — snacks, beverages, fresh and frozen food, tobacco and adjacent convenience goods — deployed across offices, public spaces, transport hubs and institutions, including hardware, payment systems and operator services. Italy holds the highest vending machine density in Europe.
This analysis covers vending hardware, embedded payment technology and operator service revenue across Italy's retail vending channel, segmented by product, location and payment mode. This analysis does not cover full-line retail grocery, restaurant foodservice, unattended micromarket hardware distinct from vending cabinets, or reverse-vending deposit-return infrastructure.
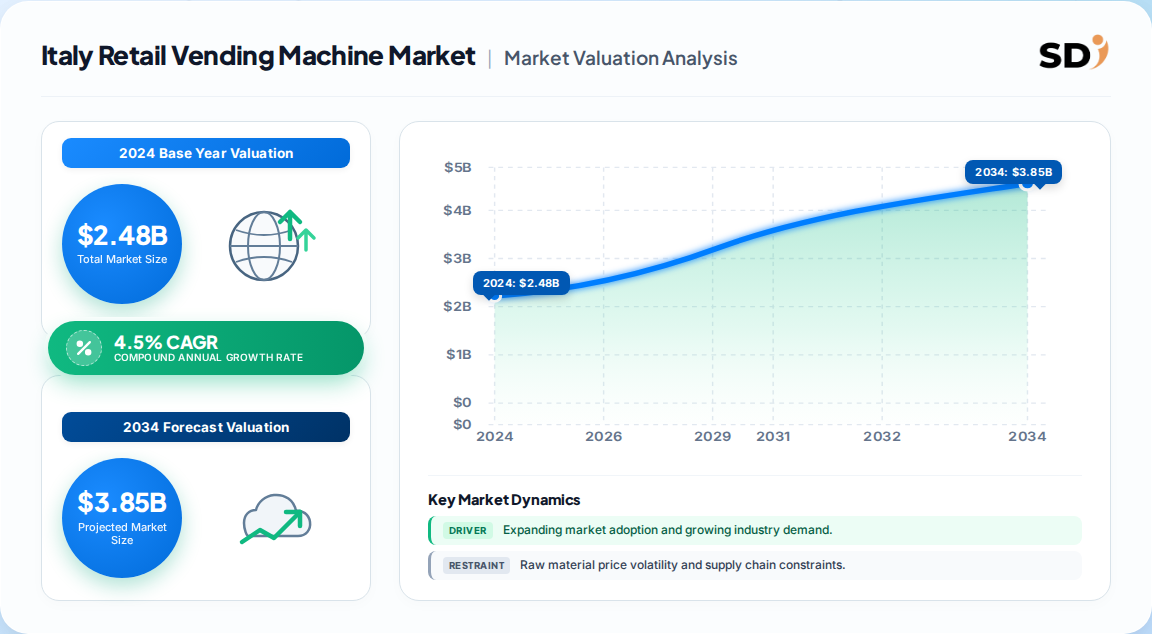
Italy's retail vending market is most defensibly sized at USD 2.48 billion for 2024, growing to USD 3.68 billion by 2033 at 4.5% CAGR — a mature-market trajectory typical of a country where installed density is already Europe's highest.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 2.48 Bn → 3.68 Bn | 2024 | 2033 | 4.5% | Italy retail vending, product + service revenue | One published industry estimate |
| ~13.5% CAGR (Europe intelligent vending) | 2025 | 2034 | 13.5% | Europe-wide smart/IoT-enabled units only | A competing analysis |
| 5.04% CAGR (global vending) | 2025 | 2031 | 5.04% | Global all-technology vending hardware | A competing analysis |
Our analysis suggests the 4.5% figure is the most defensible Italy-specific benchmark because it reconciles a saturated installed base with modest price and mix uplift. The 13.5% intelligent-vending CAGR measures only the smart sub-segment, not the whole market — conflating the two overstates Italian growth by roughly three times.
The market segments by product, location and payment mode; beverage machines lead revenue, manufacturing and office sites lead placement, and cashless is the leading payment mode.
| Parent | Children |
|---|---|
| By Product | Snacks, Beverage, Food, Frozen, Tobacco |
| By Location | Offices, Public Places, Manufacturing, Transport Hubs, Healthcare, Education |
| By Payment Mode | Cash, Cashless |
Beverage's 38.86% share reflects impulse hydration demand in Italy's warm climate and high-footfall hubs, while snacks are forecast to grow faster at 4.7% CAGR as operators upgrade to organic, protein and artisanal Italian ranges.
Lombardy leads Italy's vending deployment, consistent with its concentration of industrial estates, corporate offices and transport hubs; Lazio and Campania follow on population and tourism density.
| Region | Market Share (%) |
|---|---|
| Lombardy | 0.21% |
| Lazio | 0.12% |
| Campania | 0.11% |
| Veneto | 0.1% |
| Piedmont | 0.09% |
| Emilia-Romagna | 0.09% |
| Tuscany | 0.08% |
| Sicily | 0.07% |
| Apulia | 0.06% |
| Other Regions | 0.07% |
This distribution is an analytical synthesis rather than a published regional breakdown; precise provincial splits require the full report's placement-level dataset. Directionally, northern industrial regions carry the office and manufacturing bias that drives 34.24% of value, while southern regions skew toward public-place and seasonal tourism demand.
Growth is driven by premium and fresh assortments, cashless and telemetry adoption, and geographic expansion into hospitals, schools and tourist areas; high capex, maintenance and payment friction restrain it.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Premium/fresh product mix | Driver | High | Higher ticket and margin per vend |
| Cashless and telemetry | Driver | High | Route optimisation, fewer stockouts |
| Non-traditional sites | Driver | Medium | New demand in hospitals, schools, tourism |
| High smart-unit capex | Restraint | High | ~2.5x conventional unit cost |
| Machine downtime / freshness complaints | Restraint | Medium | Erodes repeat usage in older fleets |
| Low-density rural economics | Restraint | Medium | Longer restock routes compress margin |
Our analysis suggests the driver-restraint balance is asymmetric: premium mix and telemetry raise revenue per machine, while capex and downtime constrain only the pace of fleet replacement. The net effect supports steady rather than explosive growth.
Italy's competitive field spans domestic operators with dense networks, health-focused challengers, and equipment manufacturers whose export scale underpins Italy's role as a European production hub.
| Company | Role | Differentiator |
|---|---|---|
| IVS Italia | Operator | Wide national network, reliable service |
| Gruppo Argenta | Operator | Fresh food and premium snacking |
| Serim | Operator | Sustainable, health-focused ranges |
| DF Italia | Operator | Health-oriented offerings |
| Evoca | Manufacturer | Smart, eco-friendly machine design |
| Bianchi Industry | Manufacturer | Coffee and beverage systems |
| Rheavendors | Manufacturer | Automated retail equipment |
Our analysis suggests operator moats rest on site contracts and restocking density rather than hardware, while manufacturers compete on export reach — Italy shipped USD 103.5 million of vending machines in 2024, led by France (USD 16.8m), Brazil (USD 10.9m) and Germany (USD 8.9m).
Buyers should prioritise four criteria: cashless and mobile-wallet acceptance, telemetry for real-time stock and fault data, energy efficiency, and product-mix flexibility for fresh and premium SKUs. Machine downtime and inconsistent cashless payments are the most frequently cited consumer pain points, making predictive maintenance a procurement differentiator rather than a nice-to-have.
Switching costs are material. A site contract typically bundles hardware, restocking and payment processing, so operators changing suppliers face renegotiation, reader re-certification and staff retraining. Compliance also demands attention: payment processing fees of 2–5% compress margins, and European packaging and deposit-return obligations increasingly shape what cabinets can sell and how empties are recovered.
Procurement risk concentrates in older, non-urban installations where interfaces and product information are weakest. Buyers should contract explicitly on uptime, restock response time and cashless success rates.
The balance of evidence favours a mix-led, not volume-led, growth thesis for Italy. With the highest machine density in Europe, incremental profit comes from raising value per vend through premium coffee, fresh food and health-oriented snacks, supported by cashless conversion and telemetry-driven route optimisation.
The strongest counter-argument is that smart-vending CAGRs above 13% for Europe signal a step-change that could lift Italy faster than 4.5%. We reject this as a base case: those figures measure only the IoT-enabled sub-segment, and Italy's replacement cycle is gradual, constrained by roughly 2.5x conventional capex. The 4.5% trajectory remains the prudent planning anchor.
Actionable strategy:
Evidence that would change our conclusion: a sustained multi-year surge in cashless penetration above 70% of transactions, or policy-mandated deposit-return retrofits, which would accelerate replacement demand beyond our 4.5% forecast.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 4.5% from 2020-2034 |
| Segmentation |
|
The Italy retail vending machine market was estimated at USD 2.48 billion in 2024 and is projected to reach USD 3.68 billion by 2033, growing at a 4.5% CAGR from 2025 to 2033.
Beverage vending machines led with 38.86% revenue share in 2024, driven by bottled water, soft drinks, juices and energy drinks in high-footfall public and transport locations.
Yes. Cashless vending held the largest share of payment modes in 2024, supported by mobile wallets, contactless cards and telemetry systems across smart machine fleets.
Leading operators include IVS Italia and Gruppo Argenta, with Serim and DF Italia gaining ground on health-focused ranges. Equipment makers include Evoca, Bianchi Industry and Rheavendors.
Growth is driven by premium and organic product diversification, cashless and telemetry adoption, and expansion into hospitals, schools, airports and tourist areas rather than new machine proliferation.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. Structured depth interviews were conducted across the vending value chain, including vending equipment manufacturers, product brand suppliers, vending operators and franchise managers, payment technology providers, and facility and procurement managers at host sites. Decision-maker designations interviewed include VP of Operations, Head of Procurement, Technical Directors for fleet maintenance, and Commercial Operations Leads responsible for site contracts and restocking economics.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Operations & Commercial Leads | 40% |
| Procurement & Sourcing Directors | 30% |
| Technical & Maintenance Directors | 30% |
| Company Type | Representation (%) |
|---|---|
| Vending Equipment Manufacturers | 35% |
| Vending Operators & Franchise Managers | 40% |
| Payment & Telemetry Technology Providers | 15% |
| Host-Site Facility & Procurement Managers | 10% |
Secondary validation draws on official multilateral trade databases — UN Comtrade and WITS for HS 847619 automatic goods-vending machine flows, Eurostat and WTO statistics — alongside corporate annual filings and investor presentations, patent databases, and recognised industry associations and regulatory bodies governing payment security and packaging recovery.
We run simultaneous top-down allocation from macroeconomic retail and out-of-home consumption benchmarks and bottom-up modelling of manufacturer output, unit pricing, installed base and per-machine consumption. Discrepancies are reconciled through cross-segment ratio checks on beverage, snack and food mix.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
