 Dark Store Market
: Size, Forecast & Trends 2026
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 191

Vijayashree Ugale
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Dark Store Market
Vijayashree Ugale
Research Analyst
| Year | Market Size |
|---|---|
| 2025 | 30.10 B |
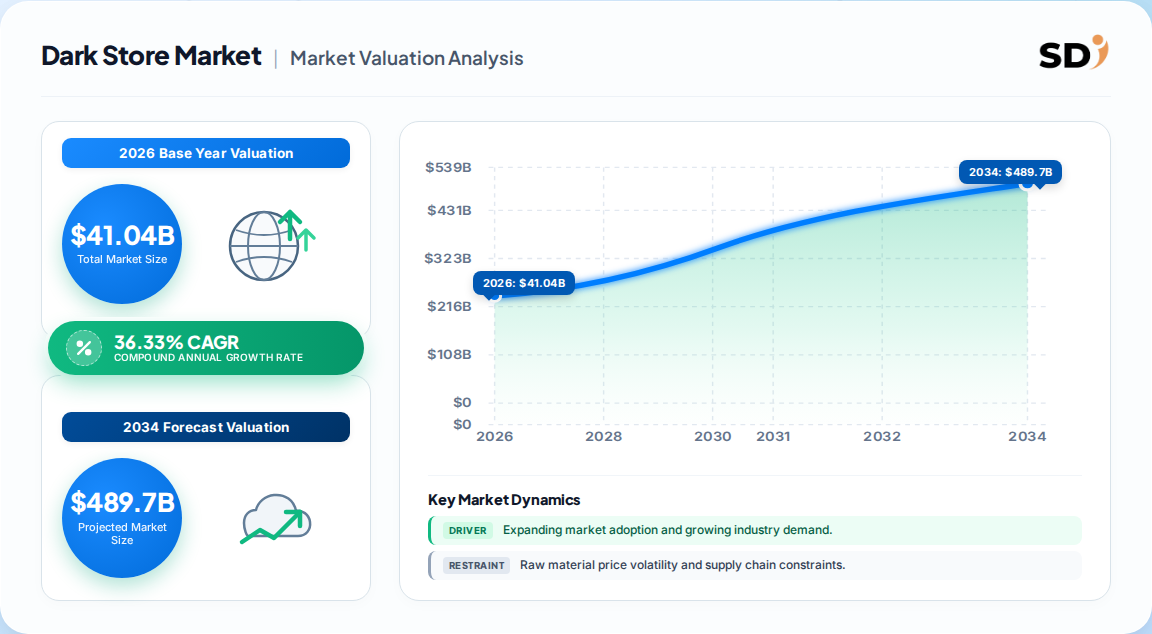
| 2026 | 41.04 B |
| 2027 | 55.96 B |
| 2028 | 76.29 B |
| 2029 | 104.0 B |
| 2030 | 141.8 B |
| 2031 | 193.3 B |

A dark store is a retail or distribution facility operated exclusively to fulfill online orders — picking, packing and dispatching — with no customer-facing browsing or checkout. The global Dark Store Market covers the revenue generated by these fulfillment assets across groceries, meat and dairy categories, sold through home delivery, curbside and in-store pickup channels.
This analysis covers global dark store facility revenue across three categories (groceries, meat, dairy), three age cohorts (children, adults, elderly), three distribution channels (in-store pickup, curbside pickup, home delivery), and ownership models (independent vs. chain-owned). It spans North America, Europe, Asia-Pacific, Latin America and the Middle East & Africa. This analysis does not cover traditional brick-and-mortar grocery retail, conventional third-party logistics (3PL) warehousing, dark kitchens/ghost kitchens, or general e-commerce fulfillment centers outside the rapid-order dark store format.
Estimates diverge sharply. One published estimate puts 2026 at $34.9 billion; a competing analysis puts it at $41.04 billion; a third at $46.19 billion. The gap reflects definitional scope — whether micro-fulfillment and hybrid store-fulfillment revenue are included — rather than demand disagreement.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| $34.9B | 2026 | 2030 | 36.6% | Pure dark store fulfillment, excl. hybrid retail | Published estimate A |
| $41.04B | 2026 | 2034 | 36.33% | Dark stores + micro-fulfillment centers | Published estimate B |
| $46.19B | 2026 | 2030 | 39.9% | Broad fulfillment incl. chain-owned hybrid | Published estimate C |
| $41.59B | 2026 | 2034 | 37.19% | Offering-led, incl. prepared meals & meal kits | Published estimate D |
Our analysis suggests the $41 billion midpoint is most defensible for 2026: it aligns with the consensus 36–37% CAGR cluster and reconciles the narrower pure-play and broader hybrid definitions. The $46 billion figure implies faster near-term adoption than urban real-estate constraints support.
| Year | Value (derived from $41.04B base, 36.33% CAGR) |
|---|---|
| 2025 | 30.10 Billion |
| 2026 | 41.04 Billion |
| 2027 | 55.96 Billion |
| 2028 | 76.29 Billion |
| 2029 | 104.01 Billion |
| 2030 | 141.80 Billion |
| 2031 | 193.32 Billion |
| 2032 | 263.55 Billion |
| 2033 | 359.30 Billion |
| 2034 | 489.65 Billion |
Segmentation is category-led, with groceries the anchor revenue pool and dairy the fastest-growing niche. Age-group and distribution-channel cuts reveal where demand concentration and wallet share are shifting.
| Parent segment | Children |
|---|---|
| By Category | Groceries (packaged foods, beverages, fresh produce, frozen), Meat (poultry, beef, pork, seafood), Dairy (milk & alternatives, cheese, yogurt, butter & cream) |
| By Age Group | Children, Adults, Elderly |
| By Distribution Channel | In-store pickup, Curbside pickup, Home delivery |
| By Ownership | Independently owned dark stores, Chain-owned dark stores |
Groceries command the largest revenue share (40–56% depending on definition) because they combine high purchase frequency with basket breadth. Dairy's ~38% CAGR is the standout: cold-chain maturation and organic/plant-based demand are converting a historically underserved category into a dark store battleground.
North America leads with roughly 35% of global revenue, driven by mature e-commerce penetration, dense urban metros and aggressive 10–30 minute delivery competition. Asia-Pacific is the fastest-growing region at ~22.4% CAGR, powered by India and Southeast Asia quick-commerce scale-up.
| Region | Market Share (%) |
|---|---|
| North America | 0.35% |
| Europe | 0.24% |
| Asia-Pacific | 0.27% |
| Latin America | 0.08% |
| Middle East & Africa | 0.06% |
| Region | Revenue share (2025) | Growth posture |
|---|---|---|
| North America | ~35.3% | Largest, mature; U.S. CAGR ~33.9% |
| Asia-Pacific | ~26.8% | Fastest-growing (~22.4% CAGR) |
| Europe | ~24.1% | Sustainability-led, regulation-heavy |
| Latin America | ~7.8% | Emerging, urban-concentrated |
| Middle East & Africa | ~6.0% | Early-stage, gulf-led |
Growth is driven by structural urban density and near-universal consumer preference for speed; the binding constraints are high urban real estate and labor costs plus zoning friction that slows site approval in exactly the metros where demand is highest.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Urbanization & density | Driver | High | 68% urban by 2050 raises last-mile demand |
| Same-day delivery expectation | Driver | High | 73% of online shoppers pay extra for speed |
| Automation & AI logistics | Driver | Medium | 20% order-processing efficiency gain |
| Online grocery expansion | Driver | High | U.S. online grocery $7.7B in 2024, +8% YoY |
| Urban real estate & labor cost | Restraint | High | Labor ~60% of fulfillment opex; rents +10%/yr |
| Zoning & community pushback | Restraint | Medium | Non-public stores conflict with retail zoning |
| Perishable-product management | Restraint | Medium | Cold-chain loss risk in dairy and meat |
Our analysis suggests the driver/restraint balance currently favors expansion, but the margin of safety is narrowing in mature metros. The critical second-order effect: as rents and labor inflate, the 10–30 minute promise becomes a cost arms race that only operators with automated picking and dense order batching can sustain.
The landscape is bifurcated between global retail incumbents (Walmart, Amazon, Kroger, Carrefour, Tesco) leveraging existing supply chains, and venture-backed quick-commerce specialists (Getir, Zepto, Gopuff, Flink, Samokat) built for speed but dependent on continuous capital.
| Vendor | Model | Primary strength | Strategic exposure |
|---|---|---|---|
| Walmart Inc. | Chain-owned hybrid | Store network + fulfillment scale | Legacy store cost drag |
| Amazon.com Inc. | Chain-owned micro-fulfillment | Logistics and automation depth | Real-estate intensity |
| The Kroger Co. | Chain-owned dark stores | Grocery breadth and loyalty data | Regional concentration |
| Ocado Group | Technology + automated fulfillment | Robotics and platform licensing | Capital-heavy infrastructure |
| Getir / Gopuff | Pure-play quick commerce | 10–30 minute urban density | Path-to-profitability pressure |
| Zepto / Swiggy / BigBasket | Asia-Pacific quick commerce | High-frequency metro demand | Regulatory and funding volatility |
Competitive moats are shifting from brand to fulfillment economics: order density per dark store, picking automation, and cold-chain reliability now determine unit profitability more than marketing spend. Incumbents hold structural cost advantages; specialists hold speed and consumer-app advantages.
Buyers evaluating dark store capability should prioritize order density per facility and cold-chain integrity over headline delivery-speed claims. A dark store servicing fewer than a threshold order volume per day cannot amortize urban rent, and dairy/meat category expansion collapses without validated refrigeration. Procurement risk concentrates in single-site dependency: a zoning reversal or lease escalation in a key metro can strand an entire delivery radius.
Switching costs are moderate for retailers using third-party dark store platforms but high for operators who have embedded proprietary inventory-management and routing software. Regulatory compliance — zoning classification, rider classification, food-safety licensing and perishable handling standards — varies by municipality and is the most common cause of launch delay. Our analysis suggests buyers should demand contractual protection on site continuity and cold-chain SLAs before signing multi-year fulfillment agreements.
The balance of evidence favors aggressive but disciplined expansion concentrated in high-density metros, with the $41 billion 2026 baseline and ~36–37% CAGR as the planning anchor. The strongest counter-argument is that quick-commerce unit economics remain unproven at scale: several pure-play operators have retrenched, and if urban real-estate costs outpace basket growth, the forecast cluster could prove optimistic on the upper end.
Our judgment is that the incumbents — retailers with existing store networks and cold-chain assets — are structurally favored over capital-dependent specialists through 2030. The hybrid model (store + dark fulfillment) spreads fixed costs and hedges zoning risk, which is why chain-owned formats are gaining share in mature markets. Asia-Pacific remains the highest-return growth theater but carries funding and regulatory volatility.
Actionable strategy:
Evidence that would change this conclusion: a sustained decline in urban industrial rents, a step-change in autonomous delivery economics, or regulatory liberalization of dark store zoning in major metros would tilt the advantage back toward pure-play specialists.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 36.33% from 2020-2034 |
| Segmentation |
|
The market is growing at roughly 36–37% CAGR, with consensus pointing to about 36.3% from 2026 to 2034, taking valuation from near $41 billion toward $490 billion by 2034.
North America leads with approximately 35% of global revenue, while Asia-Pacific is the fastest-growing region at around 22% CAGR, led by India and Southeast Asia.
Groceries account for the largest revenue share, typically 40–56% depending on scope, followed by meat and dairy; dairy is the fastest-growing sub-category at about 38% CAGR.
Leading players include Walmart, Amazon, Kroger, Carrefour, Tesco, Ocado, Getir, Gopuff, Zepto, Swiggy and BigBasket, spanning incumbent retailers and quick-commerce specialists.
High urban real-estate and labor costs, plus zoning restrictions on non-public retail facilities, are the primary constraints, alongside perishable-product cold-chain management complexity.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the dark store value chain with grocery and quick-commerce operators, micro-fulfillment technology providers, cold-chain logistics firms, real-estate site-selection specialists, and last-mile delivery platforms. Decision-makers interviewed included VP-level Sourcing and Real Estate leads, Heads of Fulfillment Operations, Technical Directors for Automation, and Commercial Operations Leads.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Fulfillment Operations Heads | 35% |
| Procurement & Real Estate Leads | 30% |
| Automation Technical Directors | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Grocery & Quick-Commerce Operators | 40% |
| Micro-Fulfillment Technology Providers | 30% |
| Cold-Chain & Last-Mile Logistics | 20% |
| Real Estate & Site Selection | 10% |
Findings are benchmarked against official multilateral and public sources: UN Comtrade and WTO trade statistics, U.S. Census Bureau and Bureau of Labor Statistics data, Eurostat retail indicators, corporate 10-K and annual investor filings, patent databases, and recognized non-profit industry associations. No competitor market-research publications are used as validation inputs.
Market sizing is triangulated simultaneously top-down (macroeconomic retail and e-commerce allocation by region) and bottom-up (dark store facility counts, order density per store, average basket value and channel-mix modeling) to reconcile scope differences across published definitions.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up facility and revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, facility mapping & commercial filings | High |
