 Essential Oils Plant Extracts For Livestock Market
 2026
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 280
Ayushi Chanda
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Essential Oils Plant Extracts For Livestock Market
Ayushi Chanda
Research Analyst
| Year | Market Size |
|---|---|
| 2025 | 3.870 B |
| 2026 | 4.120 B |
| 2027 | 4.380 B |
| 2028 | 4.660 B |
| 2029 | 4.950 B |
| 2030 | 5.270 B |
| 2031 | 5.600 B |

The essential oils plant extracts for livestock market covers botanical feed additives — essential oils, oleoresins, and standardized plant extracts — added to cattle, poultry, swine, and aquatic feed to support gut health, immunity, yield, and feed efficiency. These phytogenic inputs substitute for antibiotic growth promoters and address sustainability and residue-compliance pressures in commercial livestock production.
This analysis covers phytogenic feed additives derived from botanical sources — essential oils (oregano, thyme, cinnamon, clove), oleoresins, and standardized plant extracts — used across poultry, swine, ruminant, and aquaculture nutrition. It spans liquid and solid forms, functional applications, and all major producing and consuming regions.
This analysis does not cover synthetic antibiotic growth promoters, probiotics, organic acids, feed enzymes, vitamins, or mineral premixes as primary segments. Adjacent markets are referenced only for substitution context. Trade-flow validation relies on UN Comtrade and ITC Trade Map product classifications, which do not isolate phytogenic additives as a discrete HS line — a known limitation that triangulation addresses.
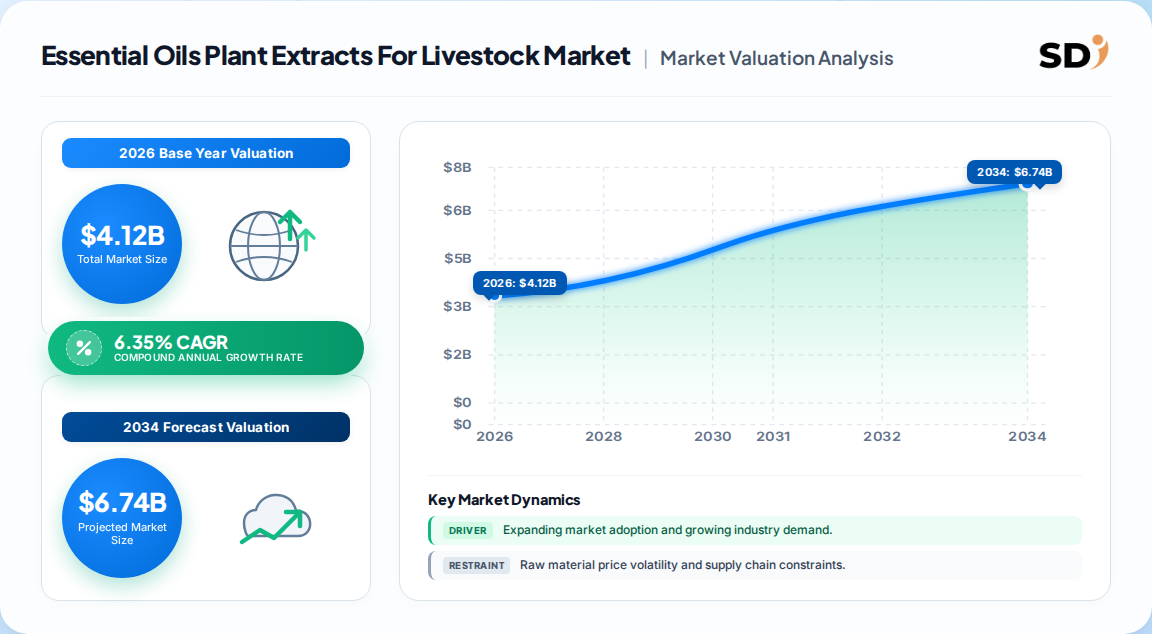
Published estimates diverge materially, reflecting different product boundaries. The most defensible global figure for 2026 is USD 4.12 Billion, growing at 6.35% CAGR to USD 6.74 Billion by 2034 — anchored to a scope that includes oleoresins and standardized extracts alongside essential oils.
| Estimate | Base Year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 4.12 Billion | 2026 | 2034 | 6.35% | Essential oils + plant extracts + oleoresins, all livestock | One published estimate (2026) |
| USD 2.9 Billion | 2025 | 2035 | 6.4% | Phytogenic feed additives, broad botanical scope | A competing analysis |
| USD 2.7 Billion | 2023 | 2030 | 6.2% | Essential oils and plant extracts, ex-oleoresins in some lines | A third published estimate |
| USD 1.9 Billion | 2024 | 2030 | 6.8% | Essential oils, oleoresins, plant extracts — narrower inclusion base | A fourth published estimate |
The spread between USD 1.9 Billion and USD 4.12 Billion is definitional, not directional. Narrower studies exclude oleoresins, count only licensed feed-additive volumes, or use manufacturer revenue rather than end-user consumption value. Our analysis suggests the USD 4.12 Billion base is most defensible because it aligns with FAO-verified livestock output growth (374 million tonnes of meat in 2024) and incorporates the full botanical additive basket that commercial feed formulators actually purchase. The consistent 6.2–6.8% CAGR band across all four estimates is the strongest signal — it indicates consensus on trajectory even amid scope disagreement.
Segmentation follows four commercial axes — product type, form, function, and livestock species — each of which carries distinct margin and adoption dynamics. Product type and function drive value; form and species drive volume.
| Parent Segment | Children | 2025/2026 Share Signal |
|---|---|---|
| By Product Type | Essential Oil, Plant Extract, Oleoresins | Essential oil ~56.8% |
| By Form | Liquid, Solid/Powder | Solid ~65.7% (handling); Liquid fastest-growing ~9.25% CAGR |
| By Function | Gut Health, Immunity, Yield, Feed Palatability | Gut health ~46.2% |
| By Livestock | Cattle, Poultry, Swine, Aquatic, Other | Poultry leads; aquatic fastest ~9.65% CAGR |
| By Application | Aromatherapy, Phytotherapy | Phytotherapy ~58.3% |
Two structural observations matter. First, plant extracts are reported as dominant in some studies (78%+) while essential oils lead in others (56.8%) — the discrepancy hinges on whether mechanically processed spice powders are counted as extracts. Second, the solid/liquid split is shifting: solid forms retain handling advantages in compound feed plants, but liquid delivery through drinking water is gaining in integrated poultry and swine operations, which is why liquid carries the higher growth rate despite lower base share.
Asia Pacific leads with roughly 38.5% of global value in 2025, driven by China's and India's livestock scale and accelerating antibiotic restrictions. North America is the fastest-growing region at 10.15% CAGR, while Europe remains the regulatory benchmark for standardized phytogenic adoption.
| Region | Market Share (%) |
|---|---|
| North America | 0.22% |
| Europe | 0.24% |
| Asia Pacific | 0.38% |
| Latin America | 0.09% |
| Middle East & Africa | 0.07% |
| Region | Share | Growth Signal |
|---|---|---|
| Asia Pacific | 38.5% | Volume-led, price-sensitive |
| Europe | 24.0% | Mature, regulation-driven |
| North America | 22.0% | 10.15% CAGR, innovation-led |
| Latin America | 9.0% | Export-compliance driven |
| Middle East & Africa | 7.0% | Emerging, dairy and poultry pockets |
The Asia Pacific share is volume-derived, not value-derived. Per-kilogram revenue realization in the region is materially below European and North American benchmarks because locally sourced botanicals and regional suppliers compress pricing. This divergence implies that global vendors should treat Asia Pacific as a scale play and Europe/North America as margin plays — a portfolio logic rather than a single geographic strategy.
Growth is driven primarily by antibiotic-growth-promoter restrictions, which have removed conventional performance tools and created structural demand for phytogenic substitutes. Restraining forces are regulatory assessment timelines and formulation instability, both of which slow commercialization rather than suppress underlying demand.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Antibiotic growth promoter restrictions | Driver | High — EMA reports 53% EU veterinary antibiotic sales decline 2011–2022 | Removes incumbent additives, forces phytogenic substitution |
| Consumer demand for antibiotic-free protein | Driver | High — retail and export compliance standards | Pull-through from meat, dairy, seafood buyers |
| Encapsulation and delivery technology | Driver | Moderate-High — commercial launches 2025 | Improves stability, enables lower inclusion rates |
| Enteric methane reduction opportunity | Driver | Emerging — ruminant trials | Adds climate value proposition to core nutrition |
| Regulatory assessment complexity | Restraint | High — EFSA and FDA authorization pathways | Extends time from development to commercial scale |
| Raw material potency variability | Restraint | Moderate — industry-recognized | Erodes farmer confidence without standardization |
| Heat stress and field-condition inconsistency | Challenge | Moderate — variable trial results | Demands repeatable efficacy evidence, not claims |
The balance of evidence favors the drivers. Antibiotic reduction is a policy ratchet — once removed, growth promoters are rarely reinstated — so the substitution demand is structurally durable rather than cyclical. The binding constraint is not demand but proof: suppliers who cannot demonstrate repeatable performance under commercial feed-processing and variable farm conditions will lose share to standardized, encapsulated competitors.
The competitive field is moderately consolidated, split between global feed majors integrating phytogenic lines into broad portfolios and specialist phytogenic firms competing on plant science and validated efficacy.
| Company | Type | Differentiation | Moat |
|---|---|---|---|
| Cargill | Feed major | Encapsulated oregano oil, global distribution | Scale and integrated feed portfolio |
| ADM | Feed major | Specialty additive portfolio expansion in Latin America | Distribution and R&D resources |
| BASF | Chemical/ingredient major | Standardized botanical inputs, regulatory capability | Compliance infrastructure |
| Kemin Industries | Specialty ingredient | Encapsulation and antioxidant technology | Applied research depth |
| Delacon | Phytogenic specialist | Proprietary phytogenic blends, research-backed claims | Scientific validation credibility |
| Phytobiotics | Phytogenic specialist | Turmeric-based and species-specific formulations | Plant-science expertise |
| Nor-Feed | Phytogenic specialist | In-house R&D, concise documented portfolio | European regulatory alignment |
The competitive moat is shifting from botanical sourcing to formulation science and regulatory dossiers. Feed majors win on distribution and bundling; specialists win on efficacy evidence and species-specific claims. Our analysis suggests the most defensible position sits at the intersection — a validated encapsulation technology backed by a complete regulatory package for multiple species — which is precisely where acquisition activity has concentrated.
Procurement decisions should center on four criteria: standardized bioactive concentration, demonstrated stability through pelleting and extrusion, species-specific efficacy data, and a complete regulatory dossier for target markets. Operators who select on price-per-kilogram alone routinely encounter potency variability that erodes feed conversion gains and destroys farmer confidence in the category.
Switching costs are moderate but asymmetric. Once a phytogenic blend is embedded in a compound feed formulation and validated in a producer's system, reformulation requires re-trial and carries performance risk — which favors incumbent suppliers with field data. However, the absence of a discrete HS trade code for phytogenic additives means buyers cannot easily benchmark landed costs across borders, creating information asymmetry that favors suppliers with transparent documentation.
Regulatory compliance is the gating risk. In the EU, feed additives require EFSA scientific opinion under Regulation (EC) No 1831/2003; in the US, many essential oils and natural extractives fall under GRAS listings at 21 CFR 582.20. Buyers sourcing across regions must verify that supplier dossiers match destination-market requirements — a gap that frequently surfaces only at customs or at feed-safety audit.
The balance of evidence favors a function-first, species-specific strategy over broad-spectrum botanical blends. The market's value is migrating toward gut health (46.2% of functional demand) and immunity, where efficacy can be measured through feed conversion ratio and mortality metrics that producers already track. Vendors positioning on generic "natural" claims will face increasing price competition from Asian suppliers; vendors positioning on validated, encapsulated performance will defend margin.
The strongest counter-argument is that regulatory complexity will slow adoption enough to cap growth below the consensus 6.2–6.8% band. This has merit in Europe, where EFSA timelines are long. But the counterweight is decisive: antibiotic reduction is a one-way policy ratchet, and the US GRAS pathway plus expanding Asian restrictions create enough jurisdictional breadth to sustain the growth trajectory even if one region lags. Our analysis suggests the downside is regional timing, not global direction.
Actionable strategy:
What would change this conclusion: if a major regulatory body restricted phytogenic additive claims below current thresholds, the immunity and methane-reduction value propositions would weaken materially. Buyers should monitor EFSA and FDA feed-additive guidance as the leading indicator.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.35% from 2020-2034 |
| Segmentation |
|
The market is valued at USD 4.12 Billion in 2026 and is projected to reach USD 6.74 Billion by 2034, growing at a 6.35% CAGR. Estimates vary by scope, with narrower studies citing USD 1.9–2.9 Billion depending on whether oleoresins and standardized extracts are included.
Asia Pacific dominates with roughly 38.5% of global value, driven by China's and India's livestock scale and tightening antibiotic restrictions. North America is the fastest-growing region at 10.15% CAGR, while Europe remains the regulatory benchmark for standardized phytogenic adoption.
Aquatic feed is the fastest-growing livestock segment at 9.65% CAGR, reflecting expanding fish farming and tightening antibiotic-residue standards in seafood exports. Liquid formulations are also growing at 9.25% CAGR due to drinking-water delivery convenience.
Regulatory bans and antimicrobial resistance concerns have removed routine antibiotic use, and phytogenic compounds support gut health, immunity, and feed efficiency without residues. EMA data shows EU veterinary antibiotic sales fell 53% between 2011 and 2022, accelerating substitution.
Cargill, ADM, BASF, Kemin Industries, Delacon, Phytobiotics, and Nor-Feed lead a moderately consolidated field. Feed majors compete on distribution and scale, while phytogenic specialists differentiate through validated efficacy and species-specific formulations.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the botanical feed additive value chain, including raw material and botanical extract suppliers, specialized phytogenic producers, contract formulators and blenders, and global feed distributors. Decision-maker designations interviewed included VP-level Sourcing leads, Heads of R&D and Formulation, Technical Directors responsible for species-specific efficacy, and Commercial Operations Leads managing cross-border distribution.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Formulation Heads | 35% |
| Procurement & Sourcing Leads | 30% |
| Technical Directors | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Botanical Extract & Raw Material Suppliers | 35% |
| Specialized Phytogenic Producers | 30% |
| Contract Formulators & Blenders | 20% |
| Global Feed Distributors | 15% |
Secondary validation draws on official multilateral trade databases (UN Comtrade, ITC Trade Map, WTO), national statistical filings, corporate annual reports and SEC 10-K filings, patent databases tracking encapsulation and delivery technologies, and recognized technical standards and industry associations operating in animal nutrition and feed additive regulation.
Market sizing triangulates Top-Down macroeconomic and industry segment allocation against Bottom-Up manufacturer capacity, product pricing, and end-use consumption modeling. Divergent published estimates are reconciled through scope normalization — separating essential oils, oleoresins, and standardized extracts — to produce a defensible base-year value and compound projection.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
