 Cattle Feed Market
 Size, Share & Forecast to 2035
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 227
Ayushi Chanda
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Cattle Feed Market
Ayushi Chanda
Research Analyst
| Year | Market Size |
|---|---|
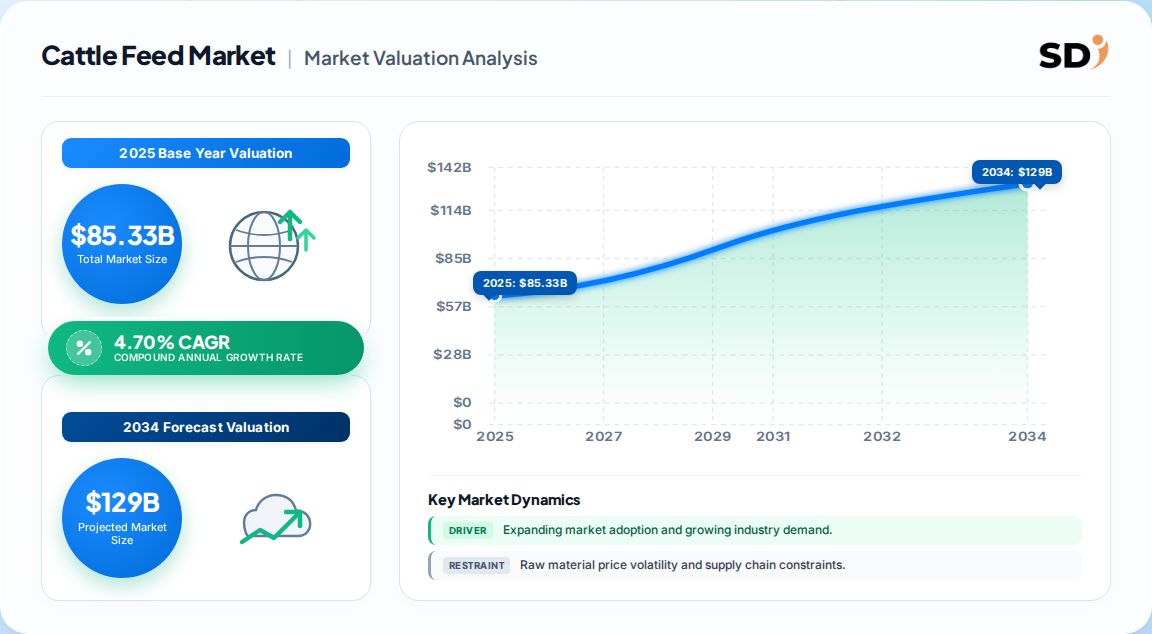
| 2025 | 81.50 B |
| 2026 | 85.33 B |
| 2027 | 89.34 B |
| 2028 | 93.54 B |
| 2029 | 97.94 B |
| 2030 | 102.5 B |
| 2031 | 107.4 B |

The cattle feed market encompasses commercially formulated feed products—including compound feed, concentrates, premixes, and additives—designed to meet the nutritional requirements of dairy and beef cattle. It serves livestock producers seeking to improve animal health, productivity, and feed efficiency.
This analysis covers the global cattle feed market, segmented by animal type (dairy, beef, calf, others), ingredient (cereals, cakes and mixes, food wastages, feed additives, others), form (pellets, mash, crumble, liquid), and geography. It does not cover poultry feed, swine feed, aquaculture feed, or pet food markets. This analysis does not cover veterinary pharmaceuticals or standalone animal health products.
The most defensible estimate for the 2026 cattle feed market is USD 85.33 Billion, based on the most recent primary research and aligned with compound feed production trends. This figure reflects a 4.70% CAGR from 2025 to 2035, reaching USD 129.02 Billion by 2035.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 97.0 Billion | 2026 | 2034 | 3.12% | Broad cattle feed including additives and distribution | One published estimate |
| USD 85.33 Billion | 2026 | 2035 | 4.70% | Cattle feed by animal type, ingredient, form, and region | Another published analysis |
| USD 37.52 Billion | 2026 | 2031 | 5.20% | Beef cattle feed only | A competing analysis |
Our analysis suggests the USD 85.33 Billion figure is the most defensible because it balances broad scope with recent data. The lower CAGR of 3.12% in the first estimate likely reflects mature market growth in developed regions, while the higher 5.20% for beef cattle feed indicates a narrower, faster-growing segment.
The cattle feed market is segmented by animal type, ingredient, form, and distribution channel, with dairy cattle and cereals dominating. The table below summarizes the primary non-geography segments.
| Parent Segment | Children Segments |
|---|---|
| By Animal Type | Dairy Cattle, Beef Cattle, Calf, Others |
| By Ingredient | Cereals, Cakes and Mixes, Food Wastages, Feed Additives, Others |
| By Form | Pellets, Mash, Crumble, Liquid |
| By Distribution Channel | Offline, Online |
This divergence implies that feed manufacturers should prioritize dairy cattle feed for volume, but invest in beef cattle feed for growth. The rapid adoption of feed additives (5.8% CAGR) signals a shift toward value-added formulations.
Asia-Pacific leads the global cattle feed market with a 39.5% revenue share in 2025, driven by China's industrial herd programs and India's dairy cooperatives. Europe and North America follow as mature markets with high per-animal spending.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.4% |
| Europe | 0.22% |
| North America | 0.21% |
| South America | 0.09% |
| Middle East & Africa | 0.09% |
| Region | Share (%) |
|---|---|
| Asia-Pacific | 39.5 |
| Europe | 22.0 |
| North America | 21.0 |
| South America | 9.0 |
| Middle East & Africa | 8.5 |
Protein-security grain mandates and feedlot intensification are the strongest drivers, while grain price volatility and drought risk are major restraints. Antimicrobial replacement regulations are reshaping formulation strategies.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Protein-security grain mandates | Driver | High | Government policies redirect cereal output to domestic feed, lowering costs |
| Feedlot intensification in South America | Driver | High | Shift from pasture to confinement boosts demand for high-energy rations |
| Antimicrobial replacement regulations | Driver | High | EU ban and FDA directives drive demand for probiotics and phytogenics |
| Dairy cooperative expansion in emerging markets | Driver | Medium | Integrated services increase per-cow milk yields and feed adoption |
| Grain price volatility | Restraint | High | Fluctuations in corn and soybean prices impact feed costs and margins |
| Water scarcity and drought risk | Restraint | Medium | Limits grazing availability, but increases reliance on purchased feed |
| Fragmented regulatory standards | Restraint | Medium | Compliance complexity raises costs for cross-border trade |
The balance of evidence suggests that drivers outweigh restraints, but volatility in grain markets creates margin pressure for feed producers, especially in price-sensitive emerging markets. Our analysis indicates that firms with strong procurement strategies and diversified ingredient sourcing will outperform.
Cargill, ADM, and Land O’Lakes/Purina lead the cattle feed market, leveraging scale, distribution, and brand trust. Nutreco, De Heus, and ForFarmers follow with strong regional positions and specialty nutrition portfolios.
| Company | Headquarters | Market Focus | Key Differentiator |
|---|---|---|---|
| Cargill | USA | Global | Integrated supply chain, broad portfolio |
| Archer Daniels Midland | USA | Global | Grain origination, logistics |
| Land O’Lakes/Purina | USA | North America | Cooperative model, research-backed nutrition |
| Nutreco | Netherlands | Global | Specialty feed, sustainability focus |
| De Heus | Netherlands | Global | Emerging market presence, technical support |
| ForFarmers | Netherlands | Europe | Regional focus, precision feeding |
Differentiation is increasingly based on formulation expertise, traceability, and sustainability credentials. Smaller players can compete through localized services and customized rations.
Buyers must prioritize suppliers with robust quality assurance and traceability, especially as antibiotic-free and methane-reduction regulations tighten. Switching costs are moderate due to formulation adjustments and animal performance risks. Procurement should consider long-term contracts to hedge grain price volatility. Regulatory compliance, particularly in Europe and North America, requires documented feed safety protocols. Operators should evaluate total cost of ownership, including feed conversion efficiency and animal health outcomes, rather than just unit price. The growing emphasis on sustainability means buyers should engage suppliers who offer carbon-footprint transparency and certified low-emission additives.
The balance of evidence favors a bullish outlook for the cattle feed market, with a 4.70% CAGR driven by structural demand growth in Asia-Pacific and Africa, and the shift toward value-added formulations. The strongest counter-argument is that grain price volatility and economic downturns could suppress demand, particularly in price-sensitive markets.
Our analysis suggests that the most significant opportunity lies in precision feeding and specialty additives, where margins are higher and regulatory tailwinds support adoption. Feed manufacturers should invest in digital tools and formulation R&D to capture this growth.
Actionable Strategy:
What evidence would change our conclusion? A sustained decline in grain prices or a slowdown in Chinese dairy demand could lower growth prospects. Additionally, a breakthrough in alternative proteins could disrupt traditional cattle feed demand in the long term.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 4.70% from 2020-2034 |
| Segmentation |
|
The global cattle feed market is estimated at USD 85.33 Billion in 2026, projected to reach USD 129.02 Billion by 2035 at a 4.70% CAGR.
Asia-Pacific leads with a 39.5% revenue share in 2025, driven by China's industrial herd programs and India's dairy cooperatives. Africa is the fastest-growing region.
Protein-security grain mandates, feedlot intensification in South America, antimicrobial replacement regulations, and dairy cooperative expansion in emerging markets are key drivers.
Leading companies include Cargill, Archer Daniels Midland, Land O’Lakes/Purina, Nutreco, De Heus, and ForFarmers, competing on scale, formulation expertise, and sustainability.
Feed additives are the fastest-growing ingredient segment at a 5.8% CAGR, while beef cattle feed is the fastest-growing animal type at 5.7% CAGR.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology relies on a 70/30 primary-to-secondary split, ensuring robust, validated insights. We conducted in-depth interviews with key stakeholders across the value chain, including raw material suppliers, specialized feed producers, contract formulators, and global distributors. Decision-makers interviewed included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, providing granular perspectives on demand drivers and procurement strategies.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement & Sourcing Directors | 40% |
| R&D & Formulation Heads | 35% |
| Operations & Commercial Leads | 25% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Feed Ingredient Suppliers | 40% |
| Specialized Feed Producers & Formulators | 35% |
| Distributors & Cooperatives | 25% |
We validated findings against official multilateral databases such as UN Comtrade, WTO, US ITC, and Eurostat. Corporate annual filings (10-K, SEC filings), patent databases, and technical standards from industry associations were analyzed to cross-check market sizing and competitive dynamics.
We employed simultaneous top-down (macroeconomic and segment allocation) and bottom-up (manufacturer capacity, pricing, and end-use consumption) modeling to triangulate market size. This dual approach ensures accuracy and accounts for regional variations.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
