 Human Resource HR Professional Services Market
HR Professional Services Market Size & Forecast to 2031
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 218

Khageshwar Rongkali
Senior Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Human Resource HR Professional Services Market
Khageshwar Rongkali
Senior Analyst
| Year | Market Size |
|---|---|
| 2024 | 78.15 B |
| 2025 | 83.75 B |
| 2026 | 89.75 B |
| 2027 | 96.19 B |
| 2028 | 103.1 B |
| 2029 | 110.5 B |
| 2030 | 118.4 B |

The Human Resource HR Professional Services Market comprises external providers that manage workforce functions—recruitment, payroll administration, benefits, compliance, training, and strategic human capital consulting—for client organizations. It spans consulting firms, SaaS platforms, and staffing agencies delivering specialized HR expertise across industries and geographies.
This report covers the global Human Resource HR Professional Services Market across provider types (consulting, SaaS), function types (recruitment, benefits, workforce analytics, and others), and end-user industries (BFSI, healthcare, IT & telecom, manufacturing, retail, government, and academia). It analyzes market sizing, segmentation, regional dynamics, competitive landscape, and growth drivers from 2026 to 2031.
This analysis does not cover internal HR departments, in-house HR software development, or adjacent markets such as enterprise resource planning (ERP) platforms outside HR modules, nor does it include pure staffing/temporary labor markets except where integrated with professional HR services.
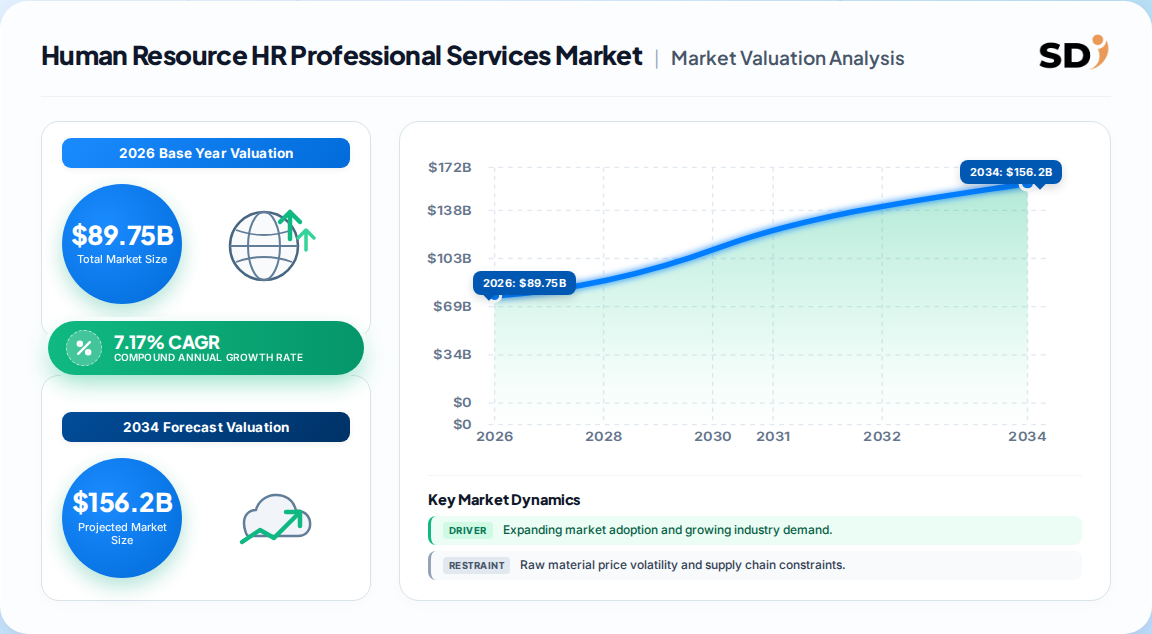
The market was valued at USD 83.75 Billion in 2025 and is estimated at USD 89.75 Billion in 2026, reaching USD 126.85 Billion by 2031 at a 7.17% CAGR. Competing estimates diverge widely due to scope differences, as shown below.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 126.85 Billion | 2026 | 2031 | 7.17% | Broad HR professional services incl. consulting, SaaS, staffing | One published estimate (Mordor Intelligence) |
| USD 13.6 Billion | 2024 | 2030 | 13.4% | Narrow HR services excluding staffing, focus on core HR and talent management | One published estimate (Grand View Research) |
| USD 18.47 Billion | 2025 | 2031 | 10.26% | External HR providers covering recruitment, payroll, and strategic consulting | One published estimate (TechSci Research) |
| USD 51.13 Billion | 2024 | 2035 | 3.94% | HR professional services across service types including staffing and training | One published estimate (Market Research Future) |
Our analysis suggests the USD 89.75 Billion (2026) figure is most defensible for the broad market definition because it aligns with staffing industry benchmarks—the American Staffing Association reported USD 124.0 Billion in U.S. staffing sales for 2024—and captures the full scope of HR professional services including staffing-adjacent functions. The narrower estimates likely exclude substantial staffing and outsourcing revenue streams, creating an apparent divergence that reflects scope, not contradiction. Buyers should calibrate their addressable market using the definition that matches their service portfolio.
The market segments by provider type, function type, and end-user industry. Consulting & advisory services dominate current revenue, while SaaS platforms and workforce analytics represent the fastest-growing segments.
| Parent Segment | Children |
|---|---|
| By Provider Type | Consulting Companies, Software-as-a-Service Companies |
| By Function Type | Recruitment & Talent Acquisition, Benefits & Claims Management, Workforce Planning & Analytics, Payroll Services, Training & Development, Core HR Services |
| By End-User Industry | BFSI, Healthcare, IT & Telecom, Manufacturing, Retail, Government, Academia |
Consulting & advisory services led with 37.52% share in 2025, reflecting enterprise demand for compliance expertise and strategic workforce transformation. SaaS providers are growing at 14.67% CAGR, driven by mid-market shift from traditional outsourcing to modular subscriptions embedding analytics and automated workflows. Recruitment & talent acquisition accounts for 26.88% share, while workforce planning & analytics is the fastest-growing function at 11.9% CAGR. Among end-users, IT & telecom holds 21.93% share, with healthcare forecast to grow at 11% CAGR.
North America leads with 39.45% revenue share in 2025, followed by Europe and Asia-Pacific. Asia-Pacific is the fastest-growing region at 10.07% CAGR, propelled by greenfield manufacturing, shared-services hubs, and hyper-local compliance demand.
| Region | Market Share (%) |
|---|---|
| North America | 0.37% |
| Europe | 0.27% |
| Asia-Pacific | 0.24% |
| Latin America | 0.06% |
| Middle East & Africa | 0.06% |
| Parent Region | Children |
|---|---|
| North America | USA, Canada, Mexico |
| Europe | Germany, UK, France, Italy, Spain, Netherlands |
| Asia-Pacific | China, Japan, India, South Korea, Australia |
| Latin America | Brazil, Mexico, Argentina, Chile |
| Middle East & Africa | Saudi Arabia, UAE, South Africa, Nigeria |
North America's dominance stems from mature HR outsourcing adoption, complex multi-state labor regulations, and concentration of major vendors (ADP, ManpowerGroup, Korn Ferry). Europe follows with strong demand for GDPR-compliant HR services and works council advisory. Asia-Pacific's growth is fueled by rapid industrialization and regulatory change velocity exceeding 12 substantive updates per jurisdiction annually, creating defensible moats for providers with on-ground expertise.
Generative AI adoption (+1.8% CAGR impact), cloud migration of legacy HR suites (+1.4% CAGR), and hyper-local compliance demand (+1.5% CAGR) are the primary growth drivers. Data-sovereignty rules and cyber-insurance premiums are the main restraints, pressuring delivery margins.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Gen-AI powered recruitment automation | Driver | High | Trims time-to-hire by 30%, raises candidate quality scores |
| Data-driven payroll error-prediction tools | Driver | High | Slashes remediation costs averaging USD 291 per error |
| Hyper-local compliance expertise demand | Driver | High | Non-compliance penalties exceed 300% of foregone fees |
| Cloud migration of legacy HR suites | Driver | High | Enables modular SaaS subscriptions, compresses vendor selection |
| Outcome-based HR service contracts | Driver | Medium | Aligns fees with retention and quality metrics |
| Data-sovereignty & privacy regulations | Restraint | High | Raises compliance costs, deters full outsourcing |
| Rising cyber-insurance premiums | Restraint | Medium | Pressures delivery margins, requires privacy-by-design investment |
| Client hesitancy over sensitive data outsourcing | Restraint | Medium | Limits adoption among multinational enterprises |
The balance of evidence favors sustained growth, with AI and compliance driving demand while data-security concerns slow—but do not reverse—adoption. The net effect is a market expanding at 7.17% CAGR, with faster growth in SaaS and analytics sub-segments offsetting slower consulting expansion.
The market is moderately concentrated, with global staffing and HR services giants competing alongside specialized SaaS platforms and regional compliance advisors.
| Company | Headquarters | Primary Focus | Differentiator |
|---|---|---|---|
| ADP | USA | Payroll, HR outsourcing | Scale and data-driven error-prediction tools |
| Randstad | Netherlands | Staffing, recruitment | Global talent pool and hyper-local compliance |
| Adecco Group | Switzerland | Staffing, workforce solutions | Multi-country compliance expertise |
| ManpowerGroup | USA | Staffing, talent acquisition | Skilled talent scarcity and green skills |
| Korn Ferry | USA | Consulting, talent management | Leadership advisory and org design |
| Robert Half | USA | Professional staffing | Finance and technology specialization |
| Allegis Group | USA | Staffing, RPO | Integrated talent solutions |
| Hays | UK | Recruitment | Sector-specific expertise |
| Mercer | USA | Benefits, HR consulting | Actuarial and benefits analytics |
| Aon | UK | Benefits, risk | Integrated HR risk management |
Competitive moats are shifting toward domain-specific training data and proprietary AI models that create sticky platform dependencies. Vendors pairing AI sourcing with human interview coaching report improved first-year retention—a metric increasingly embedded in outcome-based fee schedules. Regional compliance credentials generate defensible advantages against purely virtual rivals, with providers securing certified experts in Southeast Asia and Sub-Saharan Africa posting 40–50% annual revenue gains.
Buyers evaluating HR professional services should prioritize compliance coverage depth and data-sovereignty architecture as mission-critical selection criteria. The complexity of multi-jurisdictional data security—over 80% of privacy teams reported added responsibilities in 2024 (IAPP)—creates substantial legal and reputational risk when outsourcing sensitive employee records. Procurement should demand transparent model-audit trails for AI-driven recruitment tools, as North American regulators have issued preliminary algorithmic bias guidelines.
Switching costs are rising as vendors embed proprietary analytics into ERP integrations, creating sticky dependencies. Mid-market buyers increasingly bypass traditional RPO bids for direct SaaS subscriptions, compressing vendor selection cycles but reducing negotiating leverage. Operators must assess total cost of ownership beyond license fees, factoring in integration APIs, audit-log compliance, and country-specific tax reform cycles that encourage extended contract durations. Regulatory change velocity in emerging markets—often exceeding 12 substantive updates per jurisdiction annually—means vendors without on-ground advisory teams will struggle to maintain compliance SLAs.
The balance of evidence strongly favors SaaS-first, AI-native providers capturing disproportionate value through 2031. The market's 7.17% CAGR masks a structural bifurcation: traditional consulting and staffing grow at mid-single digits while SaaS and analytics expand above 14% CAGR. Vendors clinging to batch-processing models face margin compression as clients demand outcome-based contracts tied to retention and quality metrics. Our analysis suggests the most defensible position combines proprietary AI training data with hyper-local compliance expertise—a combination that creates both platform stickiness and regulatory moats.
The strongest counter-argument is that data-sovereignty concerns could slow outsourcing adoption enough to cap market growth below consensus, particularly among multinational enterprises handling sensitive records. Over 80% of privacy teams reported expanded responsibilities in 2024, and cyber-insurance premiums are rising. However, this restraint likely redirects rather than suppresses demand—toward privacy-by-design providers with distributed data centers and transparent audit trails.
Actionable Strategy:
What would change our conclusion: evidence of regulatory action forcing widespread repatriation of HR data or a sharp decline in AI adoption rates among mid-market buyers would materially alter the growth trajectory. Absent such shocks, the SaaS-led expansion thesis holds.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.17% from 2020-2034 |
| Segmentation |
|
The market was valued at USD 83.75 Billion in 2025 and is estimated at USD 89.75 Billion in 2026, projected to reach USD 126.85 Billion by 2031 at a 7.17% CAGR, per one published estimate covering consulting, SaaS, and staffing services.
North America leads with 39.45% revenue share in 2025, driven by mature HR outsourcing adoption and complex multi-state labor regulations. Asia-Pacific is the fastest-growing region at 10.07% CAGR, fueled by industrialization and compliance demand.
Software-as-a-Service companies are the fastest-growing provider type at 14.67% CAGR through 2031, while workforce planning & analytics leads function segments at 11.9% CAGR. Generative AI recruitment automation is the primary accelerator.
ADP, Randstad NV, Adecco Group, ManpowerGroup, and Korn Ferry are the major players, alongside Robert Half, Allegis Group, Hays, Mercer, and Aon, operating in a moderately concentrated competitive landscape.
Generative AI recruitment automation, cloud migration of legacy HR suites, hyper-local compliance expertise demand, and data-driven payroll error-prediction tools are primary drivers. AI adoption among organizations reached 51% in recruiting, per SHRM's 2025 Talent Trends report.
Data security and compliance across multiple international jurisdictions is the primary challenge. Over 80% of privacy teams reported added responsibilities in 2024, and divergent privacy laws create legal and reputational risks that deter full outsourcing by multinational enterprises.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research employs a 70/30 primary-to-secondary split, with in-depth interviews conducted across the HR professional services value chain. We engaged decision-makers at consulting firms, SaaS platform providers, staffing agencies, payroll aggregators, and regional compliance advisory firms. Interviews spanned VP-level HR operations leads, Chief People Officers, procurement directors, and compliance heads, capturing both buy-side and sell-side perspectives on service selection, pricing, and vendor evaluation criteria.
| Stakeholder Role | Interview Share (%) |
|---|---|
| HR Operations & People Officers | 35% |
| Procurement & Sourcing Directors | 30% |
| Compliance & Privacy Leads | 20% |
| Finance & CFO Office | 15% |
| Company Type | Representation (%) |
|---|---|
| Consulting & Advisory Firms | 40% |
| SaaS Platform Providers | 30% |
| Staffing & Recruitment Agencies | 20% |
| Regional Compliance Advisors | 10% |
We validate findings against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings), investor presentations, patent databases, and recognized industry associations including the Society for Human Resource Management (SHRM), American Staffing Association, and World Employment Confederation. These sources provide independent corroboration of market sizing and growth trajectory assumptions.
Our approach applies simultaneous top-down macroeconomic and industry segment allocation with bottom-up manufacturer capacity, service pricing, and end-use consumption modeling. Cross-validation between the two methods reconciles discrepancies and produces a consensus market estimate anchored to verified demand indicators across provider types and end-user industries.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
