 Boutique Hotel Market
 Size, Growth & Forecast 2026
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 184
Jaishree Sankhla
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Boutique Hotel Market
Jaishree Sankhla
Research Associate

| Year | Market Size |
|---|---|
| 2025 | 28.50 B |
| 2026 | 30.40 B |
| 2027 | 32.70 B |
| 2028 | 35.10 B |
| 2029 | 37.80 B |
| 2030 | 40.60 B |
| 2031 | 43.60 B |

The Boutique Hotel market covers small-scale, design-led accommodation properties distinguished by individual character, local cultural influence, and personalized high-touch service. Unlike standardized chains, boutique hotels compete on authenticity, architectural narrative, and experiential programming, often operating within heritage buildings or lifestyle districts and monetizing ancillary food, beverage, and event revenue.
This analysis covers global boutique hotel accommodation revenue across luxury, mid-scale, and budget tiers, segmented by traveler type, booking channel, and region. It addresses branded soft-collections, independent properties, and converted heritage assets.
This analysis does not cover the broader global hotel market (valued far larger), vacation rentals and short-term homestays, cruise accommodation, or camping grounds. Adjacent hospitality textile and FF&E supply chains are referenced only as procurement context and are excluded from sizing.
Estimates diverge sharply because "boutique" is defined inconsistently: narrow definitions count only small design-led independents, while broad definitions sweep in every lifestyle and soft-brand property. Reconciliation hinges on scope, not on demand.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 30.4 Billion | 2026 | 2033 | 7.5% | Design-led, experiential, small-format | One published estimate |
| 156.77 Billion | 2026 | 2034 | 5.0% | Broad lifestyle + soft-brand + boutique | A competing analysis |
| 18.54 Billion | 2025 | 2035 | 4.97% | Narrow independent-focused classification | A competing analysis |
The narrow-to-mid figure is most defensible for operational planning. The 156 Billion figure almost certainly folds in soft-branded lifestyle inventory from major chains, inflating the pool. Our analysis suggests buyers should anchor on the 30 Billion base and 7.5% growth, treating the larger estimate as an upper-bound landscape view rather than a serviceable market.
| Milestone | Value |
|---|---|
| 2025 market size | 28.5 Billion |
| 2026 estimate | 30.4 Billion |
| 2033 forecast | 50.5 Billion |
| CAGR 2026–2033 | 7.5% |
Segmentation matters because margin and growth differ sharply by tier and traveler type; luxury and leisure dominate revenue today, but mid-scale and business demand are where volume scaling occurs.
| Parent segment | Children |
|---|---|
| By Type | Luxury, Mid-Scale, Budget |
| By Traveler Type | Leisure Travelers, Business Travelers |
| By Booking Mode | Direct Booking, Travel Agents, Online Travel Agencies |
| By Hotel Size | Small (up to 50 rooms), Medium (51–100 rooms), Large (101–150 rooms) |
| By Price Tier | Economy, Mid-Range, Luxury |
Luxury leads at 53.5% revenue share, while leisure travelers account for 70.8%. Our analysis suggests the mid-scale tier is underweighted in current headline data — a gap that creates whitespace for operators targeting design-conscious travelers at accessible price points.
North America leads the global Boutique Hotel market with roughly 36% revenue share, driven by urban lifestyle demand, while Asia Pacific posts the fastest growth as intra-regional travel and new design-led inventory expand.
| Region | Market Share (%) |
|---|---|
| North America | 0.33% |
| Europe | 0.31% |
| Asia-Pacific | 0.22% |
| South America | 0.07% |
| Middle East & Africa | 0.07% |
| Region | 2025 share |
|---|---|
| North America | 33% |
| Europe | 31% |
| Asia Pacific | 22% |
| South America | 7% |
| Middle East & Africa | 7% |
Europe is the closest challenger, with heritage conversions in the UK, Italy, and Spain sustaining premium rates. Our analysis suggests Europe's share could rise if adaptive-reuse pipelines accelerate.
Growth is driven by experiential travel demand, personalization economics, short-haul leisure frequency, and sustainability alignment; restraint comes from high operating costs, seasonality, and limited room capacity that caps peak revenue.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Experiential, design-led demand | Driver | High | Premium rates for differentiated stays |
| Personalization and service intimacy | Driver | High | Smaller room counts enable tailored service |
| Short-haul and domestic leisure | Driver | Medium | Frequent weekend and city-break trips |
| Sustainability and authenticity | Driver | Medium | Adaptive reuse and local sourcing appeal |
| High operating and maintenance costs | Restraint | High | Compresses margins for independents |
| Seasonal and location dependence | Restraint | Medium | Uneven occupancy and cash-flow volatility |
| Limited room capacity | Restraint | Medium | Caps peak-period revenue capture |
The balance favors growth, but margin capture is uneven. Our analysis suggests operators who fail to convert experience into ancillary revenue will see cost inflation erode the premium that design once guaranteed.
Major hotel groups dominate branded boutique expansion, converting independent character into soft-collection scale, while independent operators retain a design and authenticity moat that chains struggle to replicate consistently.
| Company | Strategic position | Boutique approach |
|---|---|---|
| Marriott International | Global chain, scaled soft brands | Lifestyle and design collections |
| Accor | Lifestyle-led, The Hoxton owner | High-design lobbies, accessible rates |
| Hilton | Luxury and lifestyle expansion | Small Luxury Hotels partnership |
| Hyatt | Upscale lifestyle focus | Thompson and design-led brands |
| IHG | Broad portfolio | Boutique and lifestyle conversions |
| Small Luxury Hotels of the World | Independent alliance | Curated independent network |
Differentiation rests on distribution, loyalty, and revenue management for chains, versus authenticity and local immersion for independents. Our analysis suggests the strongest moat combines design integrity with chain-grade yield and distribution.
Buyers and operators should prioritize design authenticity, location within lifestyle districts, and ancillary revenue potential over raw room count when evaluating assets. Procurement risk concentrates in service consistency, staffing quality, and renovation upkeep — all recurring costs that erode margins for undercapitalized independents.
Switching costs are high for property-management and distribution systems, so operators should select scalable, cloud-based PMS and dynamic pricing early to avoid costly migration. Regulatory exposure includes heritage-building compliance, local zoning, and sustainability disclosure requirements gaining traction across Europe. Our analysis suggests due diligence should weight operating-cost structure and seasonality more heavily than headline ADR, because boutique premiums are only realizable where occupancy and ancillary capture are stable.
The balance of evidence favors a cautious-premium position: boutique demand is structurally sound, but the sector's headline growth masks margin fragility among small independents. The strongest counter-argument is that experiential travel is a cyclical luxury, and a leisure slowdown would disproportionately hit design-led properties with high fixed costs. We discount this because short-haul and domestic demand now cushions the segment.
Our analysis suggests the definitive second-order effect is the "experience premium" migrating from design to service and programming — design alone is increasingly replicable, so operators must differentiate on curation and local partnerships. Chains are closing the design gap via soft collections; independents must defend on authenticity and community embeddedness.
Evidence that would change our conclusion: sustained occupancy declines in leisure-dependent markets, or margin compression across mid-scale boutique tiers. Precise sub-segment forecasting by tier and metro requires the full report's granular datasets, which this overview intentionally summarizes.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.5% from 2020-2034 |
| Segmentation |
|
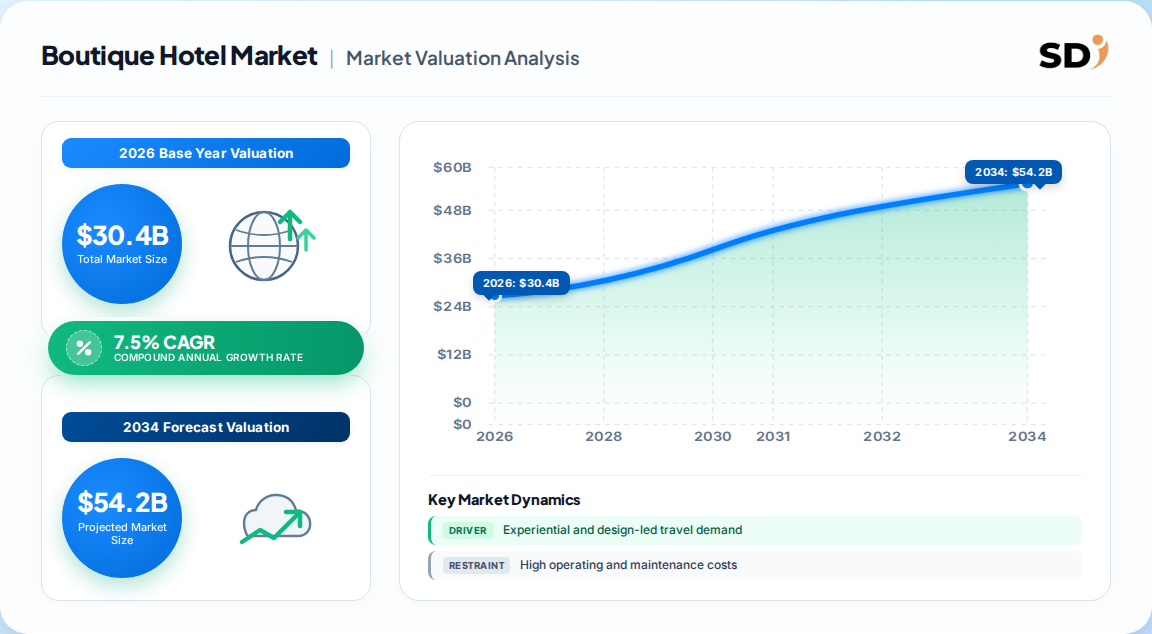
The boutique hotel market is valued at approximately 30.4 Billion in 2026, growing to a projected 50.5 Billion by 2033 at a 7.5% CAGR, driven by demand for experiential, design-led stays.
North America leads with roughly 36% revenue share, supported by urban lifestyle demand. Asia Pacific is the fastest-growing region as intra-regional travel and new design-led inventory expand.
Luxury boutique properties hold the largest revenue share at 53.5%, while direct booking is the fastest-growing channel, reflecting travelers' preference for personalized, brand-controlled engagement.
High operating and maintenance costs, seasonal tourism dependence, and limited room capacity pressure margins, particularly for independent operators with constrained financial resources and distribution reach.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis applies a 70/30 primary-to-secondary research split, prioritizing in-depth interviews across the boutique hospitality value chain. We conduct structured interviews with independent boutique operators, soft-brand collection managers, hotel asset-management firms, interior and FF&E procurement specialists, and hospitality distribution platforms. Decision-maker designations include property owners and general managers, Heads of Revenue Management, Design and Brand Directors, and Commercial Operations Leads. Fieldwork captures operating-cost structures, rate dynamics, and ancillary revenue performance.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Owners & General Managers | 35% |
| Revenue & Commercial Leads | 30% |
| Design & Brand Directors | 20% |
| Procurement Specialists | 15% |
| Company Type | Representation (%) |
|---|---|
| Boutique Hotel Operators | 40% |
| Hotel Asset Management Firms | 25% |
| Design & FF&E Suppliers | 20% |
| Distribution & OTA Platforms | 15% |
We validate findings against official multilateral and public databases, including UN Tourism arrivals data, Eurostat accommodation statistics, WTO tourism flows, and national statistics offices. Corporate annual filings (10-K, investor presentations) from listed hotel groups, patent and design registries, and recognized industry associations inform competitive and sustainability benchmarking. This anchors estimates to auditable public evidence.
We triangulate simultaneously via Top-Down allocation of macro hospitality revenue by segment and region, and Bottom-Up modeling of property counts, room capacity, ADR, occupancy, and ancillary spend. Gross booking value is reconciled to net operator revenue to preserve scope integrity.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up property and revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression and demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border travel flow and consumption analysis | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping and filings | High |