Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Apparel Market Size, Growth & Forecast 2026
Apparel Market
Apparel Market Size, Growth & Forecast 2026
Apparel Market by End User (Women, Men, Children), by Product Type (Casual Wear, Sportswear, Formal Wear, Night & Underwear, Accessories & Other), by Fabric Material (Cotton, Polyester, Nylon, Wool, Blends), by Category (Mass, Premium, Luxury), by Distribution Channel (Offline Stores, Online Stores, Catalog), by Asia Pacific (China, Japan, India, South Korea), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by South America (Brazil, Argentina, Colombia), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 203
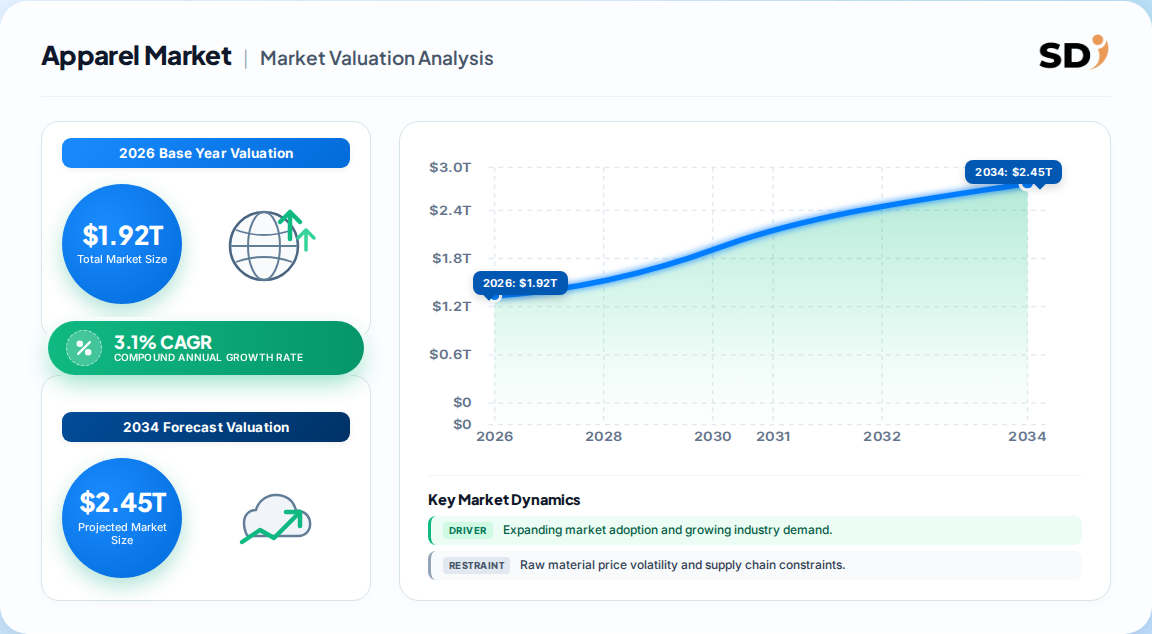
USD 1.92 trillion is the headline global apparel market size for 2026, with a defensible conservative CAGR near 3.1% through 2033.
Forecasts diverge sharply: published estimates range from USD 1.9 trillion to USD 2.5 trillion by 2033, reflecting category-definition differences more than demand disagreement.
Asia-Pacific leads with roughly 40% of global revenue; China is the largest single country market, and South America is the fastest-growing region.
Women's apparel is the largest segment at over half of revenue; mass/category apparel holds roughly 68–88% share depending on definitional treatment of premium.
Offline stores still capture 70–78% of sales, but online is the fastest-growing channel at mid-single-digit CAGR.
Key players include Nike, ZARA (Inditex), H&M, Uniqlo (Fast Retailing), Adidas and VF Corporation, competing on speed, brand and supply-chain control.
Why this matters for decision-makers: Vendors must pivot toward omnichannel fulfillment, traceable materials and localized assortment to defend margin as tariffs and returns pressure intensify.
Apparel Market Size (In Million)
2.5M
2.0M
1.5M
1.0M
500.0k
0
1.920 M
2026
1.980 M
2027
2.040 M
2028
2.100 M
2029
2.170 M
2030
2.240 M
2031
2.310 M
2032
Apparel Market Size (In Million)
Year
Market Size
2026
1.920 M
2027
1.980 M
2028
2.040 M
2029
2.100 M
2030
2.170 M
2031
2.240 M
2032
2.310 M
What is the Apparel Market?
The apparel market covers clothing produced for private end consumers, segmented into women's, men's and children's apparel. It excludes workwear, footwear, handbags, watches, jewelry and ski suits. Revenue is measured at retail value across mass, premium and luxury tiers, sold through offline stores, e-commerce and catalog channels.
Scope: what this report covers and excludes
This analysis covers global apparel demand across women's, men's and children's clothing, including casual wear, sportswear, nightwear and accessories that constitute actual articles of clothing. It spans mass, premium and luxury price tiers across all major regions and distribution channels.
This analysis does not cover footwear, handbags, watches and jewelry, workwear, ski suits, umbrellas, or the broader luxury goods category beyond apparel itself.
How big is the market for Apparel Market?
Global apparel revenue is estimated at USD 1.92 trillion in 2026, with forecasts converging on USD 2.4–2.5 trillion by the early 2030s. The spread across published estimates reflects differing category scope rather than genuine disagreement about underlying demand.
Estimate
Base Year
Horizon
CAGR
Definition / scope
Attribution
USD 1.92 trillion
2026
2031
2.62%
Private end-consumer clothing; excludes workwear and accessories
One published market forecast
USD 1.8 trillion
2025
2033
4.1%
Mass, premium, luxury apparel across all channels
A competing analysis
USD 1.44 trillion
2026
2032
3.05%
Apparel segmented by fabric, category and channel
A competing analysis
USD 1.9 trillion
2026
2033
4.1%
Broad apparel incl. premium and luxury tiers
A competing analysis
The most defensible viewpoint is a mid-single-digit CAGR near 3.1%, because the USD 1.92 trillion 2026 base is the broadest and most consistent with trade-flow evidence. The 4.1% forecasts likely embed premiumization and channel expansion that narrower definitions exclude. Our analysis suggests the true growth rate sits between these poles, closer to 3% than 4%.
How is the market segmented?
The market splits three ways: by consumer end-use, by product category, and by distribution channel. Women's apparel dominates revenue, while sportswear is the fastest-growing product line globally.
Parent segment
Children
By End User
Women, Men, Children
By Product Type
Casual Wear, Sportswear, Formal Wear, Night & Underwear, Accessories & Other
By Fabric Material
Cotton, Polyester, Nylon, Wool, Blends
By Category
Mass, Premium, Luxury
By Distribution Channel
Offline Stores, Online Stores, Catalog
Women's apparel holds roughly 51% of revenue, men's about 33%, and children's the remainder. Casual wear is the largest product type at about 37%, while sportswear grows fastest at roughly 4.5% CAGR. Cotton remains the leading fabric at near 41% share, though nylon is gaining on performance demand.
Which region leads in Apparel Market?
Asia-Pacific leads the global apparel market, accounting for approximately 40% of worldwide revenue in 2025–2026. Dense retail networks, rising branded demand and China's scale underpin the region's dominance, with South America the fastest-growing geography.
Apparel Market Regional Market Share
Loading chart...
Apparel Market Regional Market Share
Region
Market Share (%)
Asia-Pacific
0.39%
North America
0.23%
Europe
0.21%
South America
0.09%
Middle East & Africa
0.08%
Asia-Pacific — China, Japan, India, South Korea, ASEAN
North America — United States, Canada, Mexico
Europe — Germany, UK, France, Italy, Spain
South America — Brazil, Argentina, Colombia
Middle East & Africa — Saudi Arabia, UAE, South Africa
China is the largest single country market and is approaching parity with the United States as the world's leading fashion market. The United States remains the largest single-country revenue pool at roughly USD 373 billion in 2026. This divergence implies that Asia-Pacific's lead is volume-and-breadth driven, while North America's is value-and-premium driven.
What is driving growth — and what is holding it back?
Fabric innovation, sports participation and social commerce are the strongest growth drivers, while counterfeiting, raw-material volatility and tariff uncertainty are the principal restraints.
Factor
Direction
Evidence strength
Mechanism
Fabric and design innovation
Driver
High
Performance and comfort justify premium pricing
Rising sports participation
Driver
High
Expands performance apparel customer base
Social media and endorsements
Driver
Medium
Accelerates trend-led capsule launches
Sustainable apparel demand
Driver
Medium
Premiumization and brand differentiation
Counterfeit proliferation
Restraint
High
Erodes brand equity and margin
Raw material price volatility
Restraint
Medium
Squeezes production economics
Tariff and trade uncertainty
Restraint
High
Raises landed cost and sourcing complexity
The balance favors growth: demand-side drivers are structural and broad-based, while restraints are cyclical and policy-driven. Our analysis suggests tariff volatility is the single most underrated near-term risk, because roughly 89% of US apparel is imported and sourcing realignment takes years to complete.
Who are the leading vendors?
The competitive landscape is fragmented but consolidating around global brands with owned supply chains and digital reach. Market concentration is moderate, with no single player exceeding low double-digit share.
Company
Core strength
Strategic moat
Nike
Performance sportswear
Brand, R&D, athlete partnerships
Inditex (ZARA)
Fast fashion
Vertical integration, speed to shelf
H&M Group
Value fashion
Scale, private-label breadth
Fast Retailing (Uniqlo)
Basics and fabric tech
Material innovation, supply control
Adidas
Sportswear
Brand heritage, football franchise
VF Corporation
Outdoor and lifestyle
Portfolio of iconic brands
Differentiation rests on three moats: supply-chain speed, proprietary materials, and brand equity. This implies that mid-tier players without a defensible fabric or speed advantage face the sharpest margin compression.
What do buyers and operators need to know?
Buyers should prioritize suppliers with traceable material provenance, reliable replenishment and channel-specific service capability. The rise of private labels means retailers increasingly compete directly with the brands they stock, raising switching costs and requiring careful vendor-margin negotiation.
Procurement risk centers on tariff exposure, raw-material volatility and return rates. Online apparel returns remain elevated due to fit uncertainty, so operators investing in virtual try-on and sizing analytics reduce both cost and carbon footprint.
Regulatory compliance is tightening around sustainability claims and supply-chain transparency. Operators should verify eco-label substantiation and labor-practice audits before scaling sustainable lines, because greenwashing risk now carries reputational and legal consequences.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a cautiously optimistic outlook: global apparel demand is structurally sound, growing near 3% annually, but margin pools are shifting decisively toward operators who control materials, speed and channel data. The strongest counter-argument is that tariff escalation and weak discretionary spending in developed markets could compress growth below 2% through 2027, particularly for import-dependent US retailers.
We judge that risk real but temporary. The 2026 US Supreme Court tariff ruling and sourcing diversification efforts reduce policy tail risk over the medium term, while Asia-Pacific and South America provide volume offsets. The decisive variable is not demand but execution capability: brands that localize assortment, shorten lead times and substantiate sustainability claims will capture share from undifferentiated competitors.
Actionable Strategy:
Investors should overweight suppliers with proprietary fabric technology and vertical integration, where pricing power is most durable.
Retail operators should accelerate omnichannel fulfillment and sizing analytics to cut returns and defend margin against tariff-driven cost inflation.
Brands should localize assortment by region while retaining global brand architecture, capturing cross-border trend speed without over-indexing on uniform purchase behavior.
Evidence that would change our conclusion: a sustained sub-2% US discretionary spending print combined with fresh tariff escalation above 2025 levels would justify a downgrade to a defensive stance.
Apparel Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Apparel Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 3.1% from 2020-2034
Segmentation
By End User
Women
Men
Children
By Product Type
Casual Wear
Sportswear
Formal Wear
Night & Underwear
Accessories & Other
By Fabric Material
Cotton
Polyester
Nylon
Wool
Blends
By Category
Mass
Premium
Luxury
By Distribution Channel
Offline Stores
Online Stores
Catalog
By Geography
Asia Pacific
China
Japan
India
South Korea
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
South America
Brazil
Argentina
Colombia
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by End User
5.1.1. Women
5.1.2. Men
5.1.3. Children
5.2. Market Analysis, Insights and Forecast - by Product Type
5.2.1. Casual Wear
5.2.2. Sportswear
5.2.3. Formal Wear
5.2.4. Night & Underwear
5.2.5. Accessories & Other
5.3. Market Analysis, Insights and Forecast - by Fabric Material
5.3.1. Cotton
5.3.2. Polyester
5.3.3. Nylon
5.3.4. Wool
5.3.5. Blends
5.4. Market Analysis, Insights and Forecast - by Category
5.4.1. Mass
5.4.2. Premium
5.4.3. Luxury
5.5. Market Analysis, Insights and Forecast - by Distribution Channel
5.5.1. Offline Stores
5.5.2. Online Stores
5.5.3. Catalog
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. Asia Pacific
5.6.2. North America
5.6.3. Europe
5.6.4. South America
5.6.5. Middle East & Africa
6. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by End User
6.1.1. Women
6.1.2. Men
6.1.3. Children
6.2. Market Analysis, Insights and Forecast - by Product Type
6.2.1. Casual Wear
6.2.2. Sportswear
6.2.3. Formal Wear
6.2.4. Night & Underwear
6.2.5. Accessories & Other
6.3. Market Analysis, Insights and Forecast - by Fabric Material
6.3.1. Cotton
6.3.2. Polyester
6.3.3. Nylon
6.3.4. Wool
6.3.5. Blends
6.4. Market Analysis, Insights and Forecast - by Category
6.4.1. Mass
6.4.2. Premium
6.4.3. Luxury
6.5. Market Analysis, Insights and Forecast - by Distribution Channel
6.5.1. Offline Stores
6.5.2. Online Stores
6.5.3. Catalog
7. North America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by End User
7.1.1. Women
7.1.2. Men
7.1.3. Children
7.2. Market Analysis, Insights and Forecast - by Product Type
7.2.1. Casual Wear
7.2.2. Sportswear
7.2.3. Formal Wear
7.2.4. Night & Underwear
7.2.5. Accessories & Other
7.3. Market Analysis, Insights and Forecast - by Fabric Material
7.3.1. Cotton
7.3.2. Polyester
7.3.3. Nylon
7.3.4. Wool
7.3.5. Blends
7.4. Market Analysis, Insights and Forecast - by Category
7.4.1. Mass
7.4.2. Premium
7.4.3. Luxury
7.5. Market Analysis, Insights and Forecast - by Distribution Channel
7.5.1. Offline Stores
7.5.2. Online Stores
7.5.3. Catalog
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by End User
8.1.1. Women
8.1.2. Men
8.1.3. Children
8.2. Market Analysis, Insights and Forecast - by Product Type
8.2.1. Casual Wear
8.2.2. Sportswear
8.2.3. Formal Wear
8.2.4. Night & Underwear
8.2.5. Accessories & Other
8.3. Market Analysis, Insights and Forecast - by Fabric Material
8.3.1. Cotton
8.3.2. Polyester
8.3.3. Nylon
8.3.4. Wool
8.3.5. Blends
8.4. Market Analysis, Insights and Forecast - by Category
8.4.1. Mass
8.4.2. Premium
8.4.3. Luxury
8.5. Market Analysis, Insights and Forecast - by Distribution Channel
8.5.1. Offline Stores
8.5.2. Online Stores
8.5.3. Catalog
9. South America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by End User
9.1.1. Women
9.1.2. Men
9.1.3. Children
9.2. Market Analysis, Insights and Forecast - by Product Type
9.2.1. Casual Wear
9.2.2. Sportswear
9.2.3. Formal Wear
9.2.4. Night & Underwear
9.2.5. Accessories & Other
9.3. Market Analysis, Insights and Forecast - by Fabric Material
9.3.1. Cotton
9.3.2. Polyester
9.3.3. Nylon
9.3.4. Wool
9.3.5. Blends
9.4. Market Analysis, Insights and Forecast - by Category
9.4.1. Mass
9.4.2. Premium
9.4.3. Luxury
9.5. Market Analysis, Insights and Forecast - by Distribution Channel
9.5.1. Offline Stores
9.5.2. Online Stores
9.5.3. Catalog
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by End User
10.1.1. Women
10.1.2. Men
10.1.3. Children
10.2. Market Analysis, Insights and Forecast - by Product Type
10.2.1. Casual Wear
10.2.2. Sportswear
10.2.3. Formal Wear
10.2.4. Night & Underwear
10.2.5. Accessories & Other
10.3. Market Analysis, Insights and Forecast - by Fabric Material
10.3.1. Cotton
10.3.2. Polyester
10.3.3. Nylon
10.3.4. Wool
10.3.5. Blends
10.4. Market Analysis, Insights and Forecast - by Category
10.4.1. Mass
10.4.2. Premium
10.4.3. Luxury
10.5. Market Analysis, Insights and Forecast - by Distribution Channel
10.5.1. Offline Stores
10.5.2. Online Stores
10.5.3. Catalog
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Apparel Market Revenue Breakdown (Trillion, %) by Region 2026 & 2034
Figure 2: Apparel Market Volume Breakdown (pieces, %) by Region 2026 & 2034
Figure 3: Asia Pacific Apparel Market Revenue (Trillion), by End User 2026 & 2034
Figure 4: Asia Pacific Apparel Market Volume (pieces), by End User 2026 & 2034
Figure 5: Asia Pacific Apparel Market Revenue Share (%), by End User 2026 & 2034
Figure 6: Asia Pacific Apparel Market Volume Share (%), by End User 2026 & 2034
Figure 7: Asia Pacific Apparel Market Revenue (Trillion), by Product Type 2026 & 2034
Figure 8: Asia Pacific Apparel Market Volume (pieces), by Product Type 2026 & 2034
Figure 9: Asia Pacific Apparel Market Revenue Share (%), by Product Type 2026 & 2034
Figure 10: Asia Pacific Apparel Market Volume Share (%), by Product Type 2026 & 2034
Figure 11: Asia Pacific Apparel Market Revenue (Trillion), by Fabric Material 2026 & 2034
Figure 12: Asia Pacific Apparel Market Volume (pieces), by Fabric Material 2026 & 2034
Figure 13: Asia Pacific Apparel Market Revenue Share (%), by Fabric Material 2026 & 2034
Figure 14: Asia Pacific Apparel Market Volume Share (%), by Fabric Material 2026 & 2034
Figure 15: Asia Pacific Apparel Market Revenue (Trillion), by Category 2026 & 2034
Figure 16: Asia Pacific Apparel Market Volume (pieces), by Category 2026 & 2034
Figure 17: Asia Pacific Apparel Market Revenue Share (%), by Category 2026 & 2034
List of Tables
Table 1: Apparel Market Revenue Trillion Forecast, by End User 2020 & 2034
Table 2: Apparel Market Volume pieces Forecast, by End User 2020 & 2034
Table 3: Apparel Market Revenue Trillion Forecast, by Product Type 2020 & 2034
Table 4: Apparel Market Volume pieces Forecast, by Product Type 2020 & 2034
Table 5: Apparel Market Revenue Trillion Forecast, by Fabric Material 2020 & 2034
Table 6: Apparel Market Volume pieces Forecast, by Fabric Material 2020 & 2034
Table 9: Apparel Market Revenue Trillion Forecast, by Distribution Channel 2020 & 2034
Table 10: Apparel Market Volume pieces Forecast, by Distribution Channel 2020 & 2034
Table 11: Apparel Market Revenue Trillion Forecast, by Region 2020 & 2034
Table 12: Apparel Market Volume pieces Forecast, by Region 2020 & 2034
Table 13: Asia Pacific Apparel Market Revenue Trillion Forecast, by End User 2020 & 2034
Table 14: Asia Pacific Apparel Market Volume pieces Forecast, by End User 2020 & 2034
Table 15: Asia Pacific Apparel Market Revenue Trillion Forecast, by Product Type 2020 & 2034
Table 16: Asia Pacific Apparel Market Volume pieces Forecast, by Product Type 2020 & 2034
Table 17: Asia Pacific Apparel Market Revenue Trillion Forecast, by Fabric Material 2020 & 2034
Frequently Asked Questions
1. What is the current size of the global apparel market?
The global apparel market is estimated at USD 1.92 trillion in 2026, measured at retail value across women's, men's and children's clothing sold through offline and online channels worldwide.
2. How fast is the apparel market growing?
Growth is projected at roughly 3% annually through the early 2030s, with published estimates ranging from 2.6% to 4.1% depending on category definition and treatment of premium and luxury tiers.
3. Which region dominates apparel sales?
Asia-Pacific leads with approximately 40% of global revenue, driven by China's scale and rising branded demand. North America and Europe follow, with South America the fastest-growing region.
4. Who are the largest apparel companies?
Nike, Inditex (ZARA), H&M Group, Fast Retailing (Uniqlo), Adidas and VF Corporation lead the market, competing on brand strength, supply-chain speed and material innovation.
5. What is the biggest risk facing apparel operators?
Tariff and trade policy uncertainty is the most acute near-term risk, compounded by raw-material volatility and rising online return rates that erode margins across the value chain.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
This study follows a 70/30 primary-to-secondary research split. We conducted in-depth interviews across the apparel value chain, including fiber and fabric suppliers, cut-and-sew manufacturers, private-label specialists, brand owners and global distributors. Interviewees included VP-level sourcing executives, heads of product development, technical directors and commercial operations leads, ensuring coverage of both supply-side capability and demand-side purchasing behavior.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
VP Sourcing & Procurement
35%
Product Development & Design Heads
30%
Technical & Quality Directors
20%
Commercial Operations Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Fiber & Fabric Suppliers
30%
Cut-and-Sew Manufacturers
30%
Brand Owners & Private Label
25%
Distributors & Retailers
15%
Secondary Benchmarking & Public Trade Validation
We validated findings against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate filings including 10-K and annual investor presentations, patent databases for fabric and design innovation, and recognized industry associations and technical standards bodies. These sources anchored revenue totals, import dependency ratios and channel mix estimates.
Demand Modeling & Market Sizing Triangulation
We applied simultaneous top-down and bottom-up triangulation. The top-down model allocates macroeconomic consumer expenditure across apparel categories and regions, while the bottom-up model builds from manufacturer capacity, unit pricing and end-use consumption. Convergence between the two approaches established the base-year valuation and forecast band.
 Apparel Market