Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
Ammonia Fuel Cell by Type (Proton Exchange Membrane Fuel Cells (PEMFC), Alkaline Fuel Cells (AFC), Solid Oxide Fuel Cells (SOFC), Phosphoric Acid Fuel Cells (PAFC)), by Fuel Type (Green Ammonia, Blue Ammonia, Gray Ammonia, Synthetic Ammonia), by Power Output (Low Power, Medium Power, High Power), by Application (Transport, Power Generation, Industrial, Residential), by End-Use Industry (Automotive, Energy and Power, Marine, Telecommunication, Others), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Jul 2, 2026|Base Year : 2025|Pages : 90
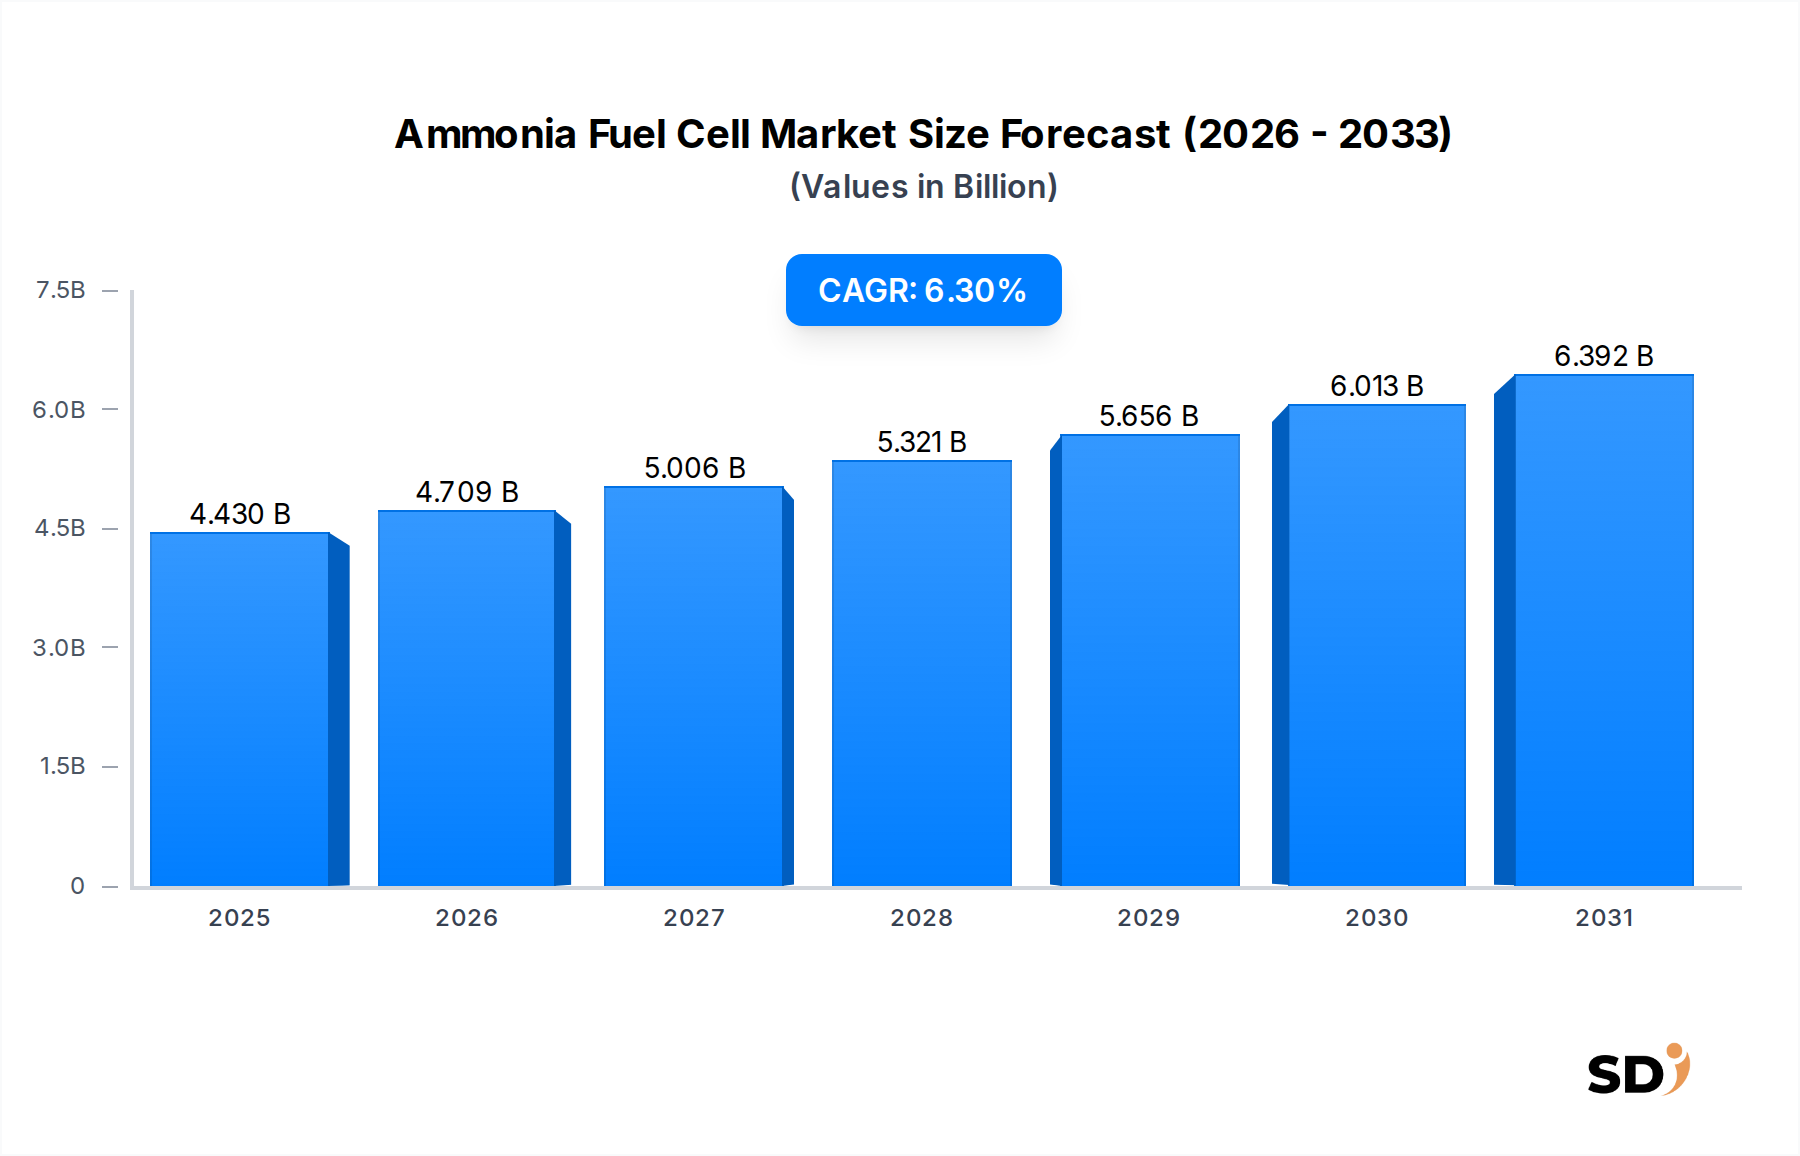
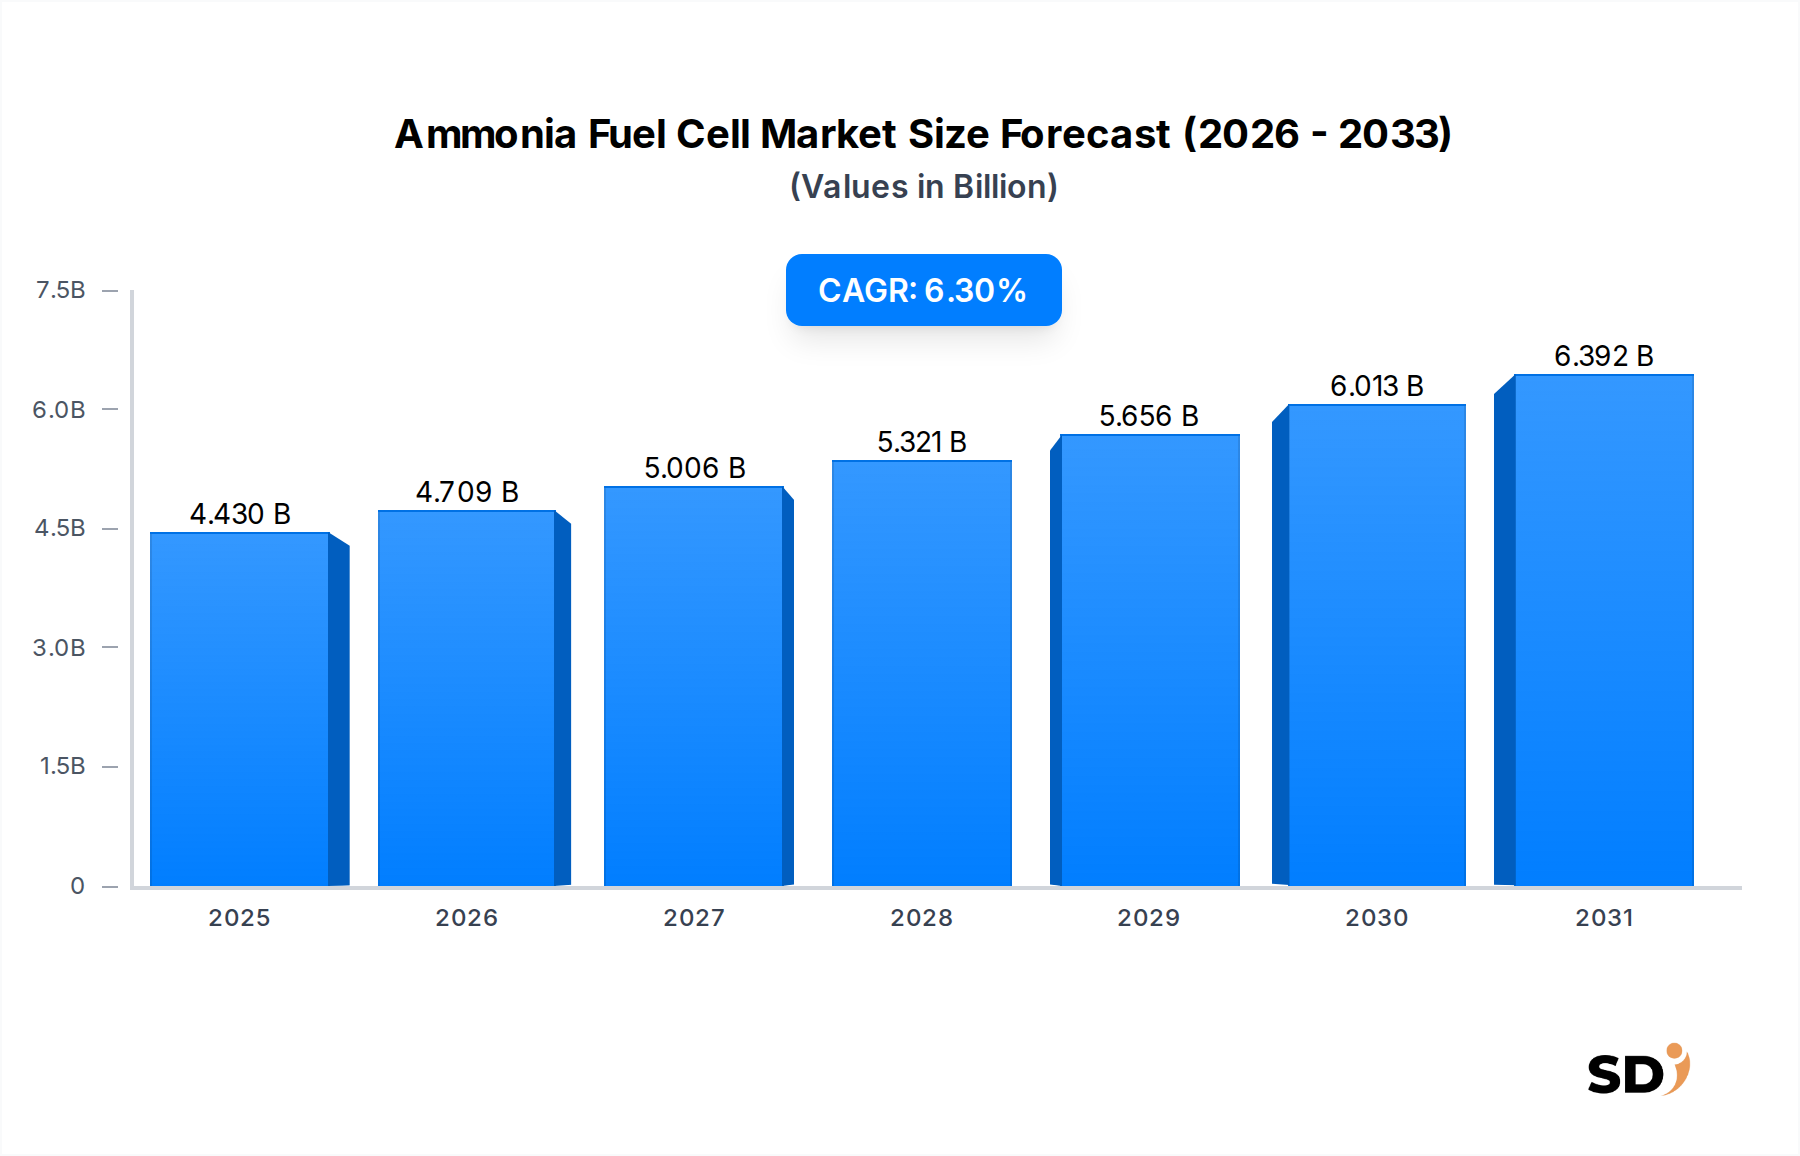
The global Ammonia Fuel Cell Market is positioned for robust expansion, propelled by an urgent global imperative for decarbonization across hard-to-abate sectors. Valued at an estimated $4.43 billion in 2025, the market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.3% through to 2032, reaching an estimated value of approximately $6.78 billion. This trajectory underscores ammonia's emerging role as a pivotal hydrogen carrier and a direct fuel source for advanced fuel cell technologies. Key demand drivers include stringent international emissions regulations, particularly within the maritime industry, the pursuit of energy independence, and the increasing viability of green ammonia production methods. Ammonia fuel cells offer a high energy density solution, significantly simplifying storage and distribution logistics compared to hydrogen, making them exceptionally attractive for heavy-duty transport, marine applications, and distributed power generation. The macro tailwinds supporting this growth encompass substantial investments in renewable energy infrastructure, a rapidly developing Hydrogen Economy Market, and governmental incentives aimed at fostering sustainable energy solutions. Furthermore, advancements in catalyst technology and stack design are continuously enhancing the efficiency and durability of ammonia-fueled systems, broadening their applicability. The outlook is decidedly positive, with sustained R&D, strategic partnerships, and scaling of green ammonia production expected to accelerate market adoption. Challenges persist, including capital costs, public perception, and the development of a comprehensive ammonia bunkering and refueling network. However, the overarching need for clean, scalable, and storable energy solutions firmly positions the Ammonia Fuel Cell Market as a critical component in achieving global net-zero targets.
Within the Ammonia Fuel Cell Market, the Solid Oxide Fuel Cell (SOFC) segment is poised to emerge as the dominant technology by revenue share, driven by its inherent advantages in directly utilizing ammonia without prior cracking. SOFCs operate at high temperatures (typically 600-1000°C), which facilitates the in-situ decomposition of ammonia (NH3) into hydrogen (H2) and nitrogen (N2) within the fuel cell stack itself. This eliminates the need for an external ammonia cracker, reducing system complexity, cost, and overall footprint, making SOFCs particularly well-suited for high-power applications. The high operating temperature also translates to superior electrical efficiencies, often exceeding 50-60% for power generation, and allows for combined heat and power (CHP) applications, further enhancing overall system economics. This makes them highly competitive in the Power Generation Market, particularly for baseload and grid-stabilization services. Key players such as GenCell Energy and AFC Energy are making significant strides in commercializing SOFC systems for ammonia. GenCell Energy, for instance, has demonstrated operational SOFC systems capable of running directly on ammonia, targeting off-grid and backup power solutions where fuel logistics are critical. Johnson Matthey, a leader in advanced materials and catalysts, is also contributing to the advancement of SOFC technology, focusing on performance and durability improvements. The inherent fuel flexibility of SOFCs, allowing them to operate on a variety of fuels beyond ammonia (e.g., natural gas, biogas, hydrogen), provides a significant strategic advantage, future-proofing investments as the global energy landscape evolves. While the high operating temperature poses material challenges and requires longer start-up times compared to lower-temperature fuel cells, ongoing research in material science is continuously mitigating these drawbacks. The segment's share is anticipated to grow considerably, especially with increasing adoption in the Marine Propulsion Market where high power output, compact size, and fuel availability are paramount. The scalability of SOFC technology, from kilowatt-scale auxiliary power units to megawatt-scale marine engines and industrial power plants, positions it as a cornerstone for the Ammonia Fuel Cell Market's future expansion. This robust technological foundation and application versatility underscore the SOFC segment's projected dominance and its critical role in the broader Clean Energy Technologies Market.
Decarbonization Mandates and Energy Security: Key Drivers in Ammonia Fuel Cell Market
The Ammonia Fuel Cell Market is fundamentally propelled by the global push for decarbonization and the strategic pursuit of energy security. Stringent international and national climate policies, exemplified by the International Maritime Organization's (IMO) target to reduce greenhouse gas emissions from shipping by 50% by 2050 relative to 2008 levels, are forcing industries to adopt zero-emission fuel alternatives. Ammonia, as a carbon-free fuel at the point of use, directly addresses these mandates, positioning ammonia fuel cells as a viable path towards compliance. For instance, countries in the European Union, under the "Fit for 55" package, are implementing measures to scale up renewable hydrogen and ammonia production and utilization, creating a regulatory pull for demand. Furthermore, the volatility in global energy markets and geopolitical shifts have underscored the critical need for diversified and resilient energy supply chains. Ammonia, produced from abundant natural gas (blue ammonia with carbon capture) or increasingly from renewable electricity (green ammonia), offers a pathway to reduce reliance on fossil fuels from politically sensitive regions. Investments in the Green Ammonia Market are soaring, driven by incentives to produce hydrogen from renewable sources, subsequently synthesizing it into ammonia for easier storage and transport. Major energy importing nations are actively seeking to secure future ammonia supplies as a strategic energy vector. For example, countries like Japan and South Korea, heavily reliant on imported energy, are investing in ammonia supply chains and related technologies to enhance their long-term energy security. While the capital expenditure for establishing green ammonia production facilities and the inherent toxicity of ammonia pose some constraints, the long-term benefits of emissions reduction and energy independence far outweigh these challenges. The ongoing development of the Electrolyzer Market is crucial for scaling green ammonia production, further reinforcing the viability and attractiveness of ammonia fuel cells as a solution to both climate change and energy security imperatives.
Competitive Ecosystem of Ammonia Fuel Cell Market
GenCell Energy: A leading provider of ammonia-powered fuel cell solutions, GenCell specializes in off-grid, backup, and primary power generation, leveraging its alkaline fuel cell technology to offer resilient and sustainable energy solutions globally. The company focuses on robust systems suitable for extreme conditions and critical infrastructure.
Johnson Matthey: A global leader in sustainable technologies, Johnson Matthey provides advanced catalyst materials and components crucial for various fuel cell types, including those optimized for ammonia decomposition and oxidation, enhancing efficiency and durability across the Ammonia Fuel Cell Market.
MAN Energy: A major player in marine and power plant engineering, MAN Energy is actively developing two-stroke engines capable of running on ammonia, signaling a strong commitment to decarbonizing the maritime sector and exploring fuel cell integration for ship propulsion.
Ballard Power: A prominent developer of proton exchange membrane (PEM) fuel cell products, Ballard Power is exploring ammonia as a hydrogen carrier, focusing on technologies for efficient ammonia cracking to feed its established PEM fuel cell systems for heavy-duty mobility and stationary power.
Amogy: Specializing in ammonia-to-power solutions, Amogy has successfully demonstrated ammonia-fueled powertrains for various applications, including tractors, drones, and heavy-duty trucks, showcasing its innovative ammonia cracking and fuel cell integration technology.
Hydrofuel Inc: An innovator in ammonia-based energy solutions, Hydrofuel Inc. focuses on developing efficient methods for storing and converting ammonia into power, contributing to both the production and utilization aspects of the ammonia energy ecosystem.
AFC Energy: Known for its proprietary alkaline fuel cell technology, AFC Energy is developing high-power fuel cell systems capable of running on hydrogen and is actively adapting its platforms to incorporate ammonia as a direct or indirect fuel source for large-scale industrial and marine applications.
Others: This category includes a growing number of startups, academic institutions, and consortiums globally that are contributing to R&D, pilot projects, and niche applications, fostering innovation and competition within the Ammonia Fuel Cell Market.
Recent Developments & Milestones in Ammonia Fuel Cell Market
January 2025: A consortium including Amogy and a major shipping company announced the successful demonstration of a 1 MW ammonia-fueled Solid Oxide Fuel Cell system for a maritime pilot project, aiming for full commercial deployment by the end of the decade.
March 2025: GenCell Energy secured a significant contract with a European telecommunications provider to deploy its ammonia-powered alkaline fuel cell backup generators across remote cellular tower sites, leveraging ammonia's logistical advantages over diesel.
May 2025: Regulatory bodies in Singapore and Rotterdam launched joint initiatives to develop standardized safety protocols and bunkering infrastructure for ammonia as a marine fuel, a critical step for accelerating adoption in the Marine Propulsion Market.
July 2025: Johnson Matthey unveiled a new generation of low-cost, high-efficiency Catalyst Market materials for ammonia decomposition, promising to reduce the capital expenditure for ammonia cracking units used in indirect ammonia fuel cell systems.
September 2025: A collaborative research project between a Japanese university and a leading automotive manufacturer successfully tested a small-scale Proton Exchange Membrane Fuel Cell Market prototype running on high-purity hydrogen derived from an on-board ammonia cracker, targeting heavy-duty vehicle applications.
November 2025: The U.S. Department of Energy announced a multi-million-dollar funding round for projects focused on accelerating the development of green ammonia production via advanced Electrolyzer Market technologies, aiming to drive down the cost of renewable ammonia.
February 2026: AFC Energy announced a partnership with a global industrial gas supplier to establish a dedicated supply chain for high-purity ammonia specifically for fuel cell applications, addressing a key market readiness factor.
April 2026: A new study published by an international energy agency highlighted ammonia as one of the most promising vectors for long-duration energy storage and seasonal shifting, bolstering its role in the future Power Generation Market and grid stability.
Regional Market Breakdown for Ammonia Fuel Cell Market
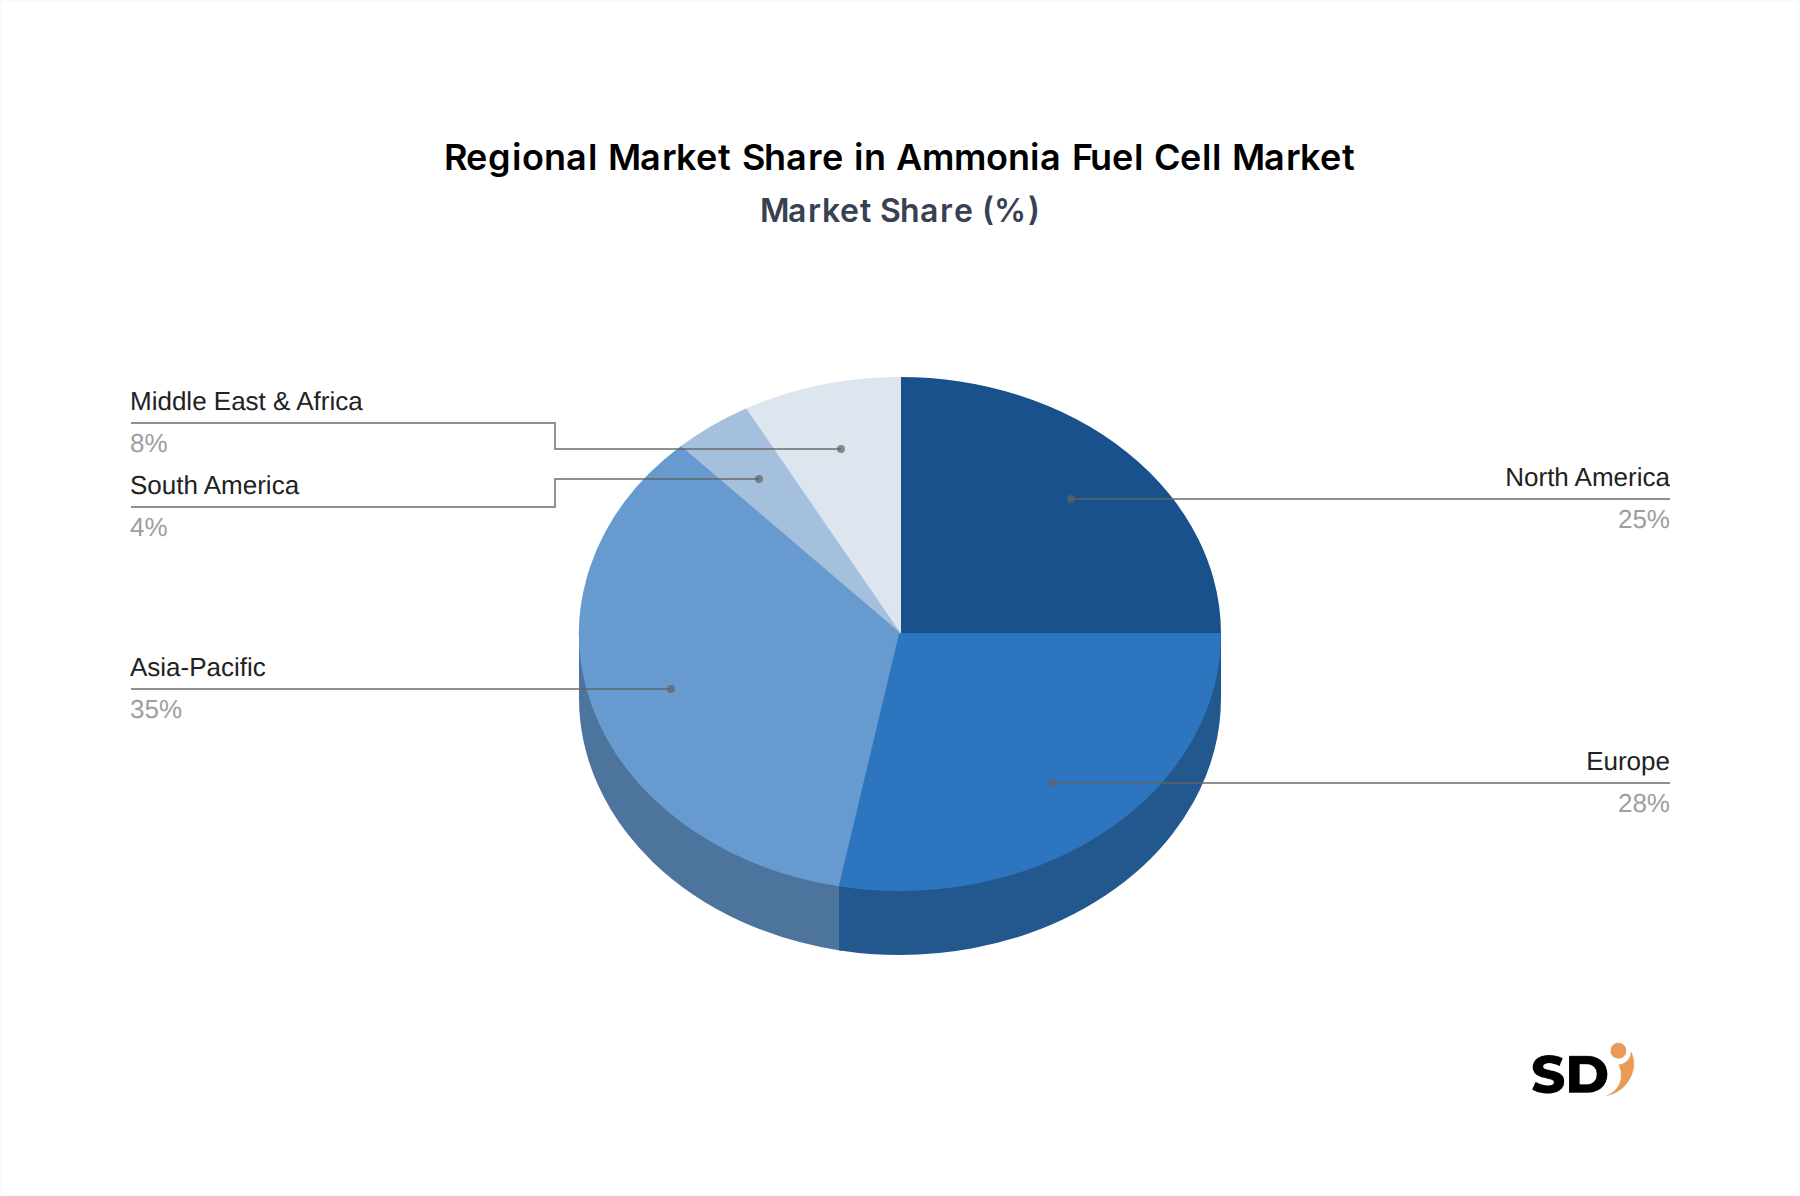
The Ammonia Fuel Cell Market exhibits significant regional disparities in adoption and growth trajectories, driven by varying regulatory environments, industrial landscapes, and strategic energy priorities. Asia Pacific is anticipated to be the fastest-growing region, primarily fueled by the strong maritime presence, rapid industrialization, and significant investments in green energy. Countries like Japan, South Korea, and China are at the forefront of developing ammonia as a marine fuel, with major shipping lines and shipbuilding companies investing heavily in ammonia-ready vessels and associated fuel cell technologies. India's burgeoning industrial sector and its focus on domestic green hydrogen and green ammonia production further bolster regional demand for fuel cell applications. The region's commitment to reducing air pollution and decarbonizing heavy industry also provides a substantial tailwind for the Ammonia Fuel Cell Market.
Europe represents a mature yet rapidly innovating market, driven by ambitious decarbonization targets set by the European Union. Strict emissions regulations, particularly for maritime transport and industrial processes, are accelerating the transition to alternative fuels. European nations are investing heavily in R&D for advanced fuel cell technologies and in the development of a comprehensive green ammonia production and distribution network. Germany, Norway, and the Netherlands are key players, with projects focusing on port infrastructure development and pilot applications in marine and stationary power.
North America, particularly the United States and Canada, demonstrates strong potential, propelled by government incentives for clean energy technologies and a robust R&D ecosystem. The focus here is on diverse applications, including heavy-duty trucking, rail, and distributed power generation. Investment tax credits and clean fuel standards are encouraging the exploration and deployment of ammonia fuel cell solutions. However, the existing low-cost natural gas infrastructure in some parts of the region may present a comparative challenge for rapid green ammonia adoption in some sectors.
The Middle East & Africa (MEA) region is emerging as a critical hub for green ammonia production due to abundant solar and wind resources for renewable electricity. Countries within the GCC, such as Saudi Arabia and the UAE, are investing billions in giga-projects aimed at becoming global exporters of green hydrogen and green ammonia. While the direct demand for ammonia fuel cells for internal consumption might develop slower, the region's role as a future supplier of competitively priced green ammonia will indirectly fuel the global Ammonia Fuel Cell Market, especially in importing regions like Asia Pacific and Europe.
Pricing Dynamics & Margin Pressure in Ammonia Fuel Cell Market
Pricing dynamics within the Ammonia Fuel Cell Market are influenced by a complex interplay of capital expenditure (CapEx) for the fuel cell system itself, the operational expenditure (OpEx) related to ammonia fuel costs, and the evolving competitive landscape. Currently, the average selling price (ASP) of ammonia fuel cell systems remains relatively high compared to conventional fossil-fuel-based power systems, primarily due to the nascent stage of technology commercialization, limited economies of scale, and the specialized materials required for efficient ammonia handling and conversion. Margin structures across the value chain are under pressure; upstream, the cost of green ammonia is a critical determinant. While gray ammonia is relatively inexpensive, the premium on blue and especially green ammonia significantly impacts the levelized cost of energy (LCOE) for ammonia fuel cells. Companies in the Green Ammonia Market face high CapEx for electrolyzers and renewable energy generation, leading to higher ex-plant ammonia prices, which directly affects the profitability of fuel cell integrators downstream. The Catalyst Market also plays a crucial role, with noble metals like platinum and ruthenium often used in efficient ammonia cracking or direct ammonia fuel cells, contributing to system costs. As manufacturing scales, and as the Electrolyzer Market matures and renewable energy prices continue to fall, the cost of green ammonia is expected to decrease, thereby alleviating OpEx pressure and improving the overall economics of ammonia fuel cell deployment. Competitive intensity among fuel cell manufacturers and the entry of new players are also exerting downward pressure on system pricing. However, the long-term benefits of zero emissions and energy security provide a strong value proposition, allowing for a certain degree of pricing power, especially in markets with strict decarbonization mandates like the Marine Propulsion Market and parts of the Power Generation Market. Strategic partnerships across the value chain, from ammonia producers to fuel cell developers and end-users, are key to optimizing cost structures and ensuring market competitiveness.
Supply Chain & Raw Material Dynamics for Ammonia Fuel Cell Market
The supply chain for the Ammonia Fuel Cell Market is intricate, characterized by upstream dependencies on ammonia production, the sourcing of specialized fuel cell components, and the logistics of ammonia distribution. Upstream, the availability and cost of ammonia are paramount. The rapidly expanding Green Ammonia Market relies heavily on the production of green hydrogen via electrolysis, which in turn depends on the supply of renewable electricity from wind, solar, or hydro sources. This makes the Ammonia Fuel Cell Market indirectly susceptible to price volatility in the renewable energy sector and the nascent state of the Electrolyzer Market. Delays or cost overruns in large-scale renewable projects or electrolyzer manufacturing can directly impact ammonia supply and pricing. Blue ammonia, derived from natural gas with carbon capture and storage (CCS), also faces upstream risks related to natural gas price fluctuations and the regulatory and technical challenges of CCS deployment.
Key raw materials for the fuel cell stacks themselves include ceramic materials for Solid Oxide Fuel Cell Market electrolytes, polymers for Proton Exchange Membrane Fuel Cell Market membranes, and various metals for interconnects and electrodes. The Catalyst Market is particularly crucial, as efficient and durable catalysts are essential for both ammonia cracking (in indirect systems) and direct ammonia oxidation within the fuel cell. Noble metals like platinum, ruthenium, and nickel are often employed, whose prices can be volatile due to geopolitical factors or supply constraints. Sourcing risks for these materials are a significant concern, necessitating diversification strategies and the development of less costly alternative materials. Furthermore, the global logistics infrastructure for ammonia, while established for the fertilizer industry, needs significant upgrades and expansions to meet the specific requirements for fuel-grade ammonia and bunkering for the Marine Propulsion Market. Potential disruptions include port congestion, pipeline limitations, and regulatory hurdles for transporting and handling a hazardous substance. Geopolitical events can also disrupt global trade routes, affecting the timely delivery of ammonia or critical components. Companies are increasingly focusing on localized supply chains for green ammonia production to mitigate these risks and enhance regional energy autonomy, further supporting the growth of the overall Clean Energy Technologies Market.
Ammonia Fuel Cell Segmentation
1. Type
1.1. Proton Exchange Membrane Fuel Cells (PEMFC)
1.2. Alkaline Fuel Cells (AFC)
1.3. Solid Oxide Fuel Cells (SOFC)
1.4. Phosphoric Acid Fuel Cells (PAFC)
2. Fuel Type
2.1. Green Ammonia
2.2. Blue Ammonia
2.3. Gray Ammonia
2.4. Synthetic Ammonia
3. Power Output
3.1. Low Power
3.2. Medium Power
3.3. High Power
4. Application
4.1. Transport
4.2. Power Generation
4.3. Industrial
4.4. Residential
5. End-Use Industry
5.1. Automotive
5.2. Energy and Power
5.3. Marine
5.4. Telecommunication
5.5. Others
Ammonia Fuel Cell Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Ammonia Fuel Cell REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 6.3% from 2020-2034
Segmentation
By Type
Proton Exchange Membrane Fuel Cells (PEMFC)
Alkaline Fuel Cells (AFC)
Solid Oxide Fuel Cells (SOFC)
Phosphoric Acid Fuel Cells (PAFC)
By Fuel Type
Green Ammonia
Blue Ammonia
Gray Ammonia
Synthetic Ammonia
By Power Output
Low Power
Medium Power
High Power
By Application
Transport
Power Generation
Industrial
Residential
By End-Use Industry
Automotive
Energy and Power
Marine
Telecommunication
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Type
Table 127: Rest of Asia Pacific Ammonia Fuel Cell Revenue (billion) Forecast, by Application 2020 & 2034
Table 128: Rest of Asia Pacific Ammonia Fuel Cell Volume (K) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
The research methodology for the "Ammonia Fuel Cell Market" report employs a robust and multi-faceted approach, combining rigorous primary and secondary research to ensure high data accuracy and comprehensive market understanding. Our firm adheres to a standard data accuracy level of 85-90%, providing clients with reliable and actionable insights. Every report is meticulously updated up to the date of purchase, reflecting the latest market dynamics and developments.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Head of R&D, Fuel Cell Systems
30%
VP of Business Development, Green Fuels
25%
Chief Engineer, Marine Propulsion
20%
Director of Product Management, Stationary Power Solutions
25%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Ammonia Production & Supply Companies
20%
Fuel Cell Stack Manufacturers
30%
Fuel Cell System Integrators
25%
End-Use Application Developers
15%
Catalyst & Component Suppliers
10%
Primary Research
Primary research forms the cornerstone of our market estimation, accounting for approximately 75% of the total research effort. This phase involves extensive qualitative and quantitative interviews with key opinion leaders, industry experts, and stakeholders across the value chain. Our structured interview process aims to gather first-hand intelligence on market trends, technological advancements, competitive landscape, regulatory environment, and future outlook.
Key participants in our primary research include representatives from:
Ammonia Production & Supply Companies: Firms involved in the production, storage, and distribution of green, blue, gray, and synthetic ammonia.
Fuel Cell Stack Manufacturers: Companies specializing in the design and manufacturing of various ammonia fuel cell types (Proton Exchange Membrane Fuel Cells (PEMFC), Alkaline Fuel Cells (AFC), Solid Oxide Fuel Cells (SOFC), Phosphoric Acid Fuel Cells (PAFC)).
Fuel Cell System Integrators: Businesses that integrate fuel cell stacks with balance of plant components to deliver complete ammonia fuel cell systems for diverse applications.
End-Use Application Developers: Manufacturers or developers deploying ammonia fuel cells in sectors such as automotive, marine, power generation, and industrial applications.
Catalyst & Component Suppliers: Providers of critical materials, catalysts, and components essential for ammonia cracker units and fuel cell stacks.
Specific job titles targeted for interviews include:
Head of R&D, Fuel Cell Systems: Providing insights into technological roadmaps, performance metrics, and cost reduction strategies.
VP of Business Development, Green Fuels: Offering perspectives on market adoption, strategic partnerships, and supply chain dynamics for ammonia.
Chief Engineer, Marine Propulsion: Discussing application-specific requirements, integration challenges, and regulatory compliance for marine use.
Director of Product Management, Stationary Power Solutions: Sharing insights on market demand, competitive positioning, and customer adoption in power generation.
Secondary Research & Industry Benchmarking
Secondary research constitutes approximately 25% of our methodology, providing foundational data, validating primary findings, and offering industry benchmarking. This stage involves an exhaustive review of published information from credible and authoritative sources. Our firm strictly avoids data from other market research websites to maintain the integrity and originality of our findings.
Sources for secondary research include:
Government Publications & Policies: Reports and guidelines from departments of energy, environmental protection agencies, and maritime authorities (e.g., U.S. Department of Energy, European Commission).
Company Annual Reports & Investor Presentations: Financial filings, corporate websites, and investor briefings of publicly traded companies in the ammonia, fuel cell, and end-use sectors.
Paid Databases: Leveraging subscriptions to premium financial and business intelligence databases including Bloomberg, Factiva, Hoovers, and PitchBook for company financials, market news, and private equity funding activities.
Academic Journals & Technical Papers: Peer-reviewed research on fuel cell technology, ammonia synthesis, and sustainable energy solutions.
Demand Modeling & Market Estimation
Our market sizing and forecasting employ a robust combination of top-down and bottom-up methodologies, meticulously triangulated to ensure accuracy.
Bottom-Up Approach: This method involves aggregating granular market data. For the Ammonia Fuel Cell market, we estimate market size by:
Analyzing the number of projected Ammonia Fuel Cell system deployments across various applications (Transport, Power Generation, Industrial, Residential) and by regions.
Determining the average price per kW or per unit of different Ammonia Fuel Cell types (PEMFC, AFC, SOFC, PAFC) across varying power outputs (Low Power, Medium Power, High Power).
Forecasting the installed capacity (MW) of Ammonia Fuel Cells, segmented by type, application, and region.
Estimating the ammonia fuel consumption (tonnes per year) specifically for fuel cell applications, differentiating by Green Ammonia, Blue Ammonia, Gray Ammonia, and Synthetic Ammonia.
Top-Down Approach: This involves assessing the overall addressable market from macroeconomic indicators, industry growth rates, and broad energy transition trends, then segmenting it down to the ammonia fuel cell market. Global GDP growth, industrial output, and government spending on sustainable energy infrastructure are key inputs.
Multi-Level Data Triangulation: Data derived from primary interviews, secondary research, and both top-down and bottom-up models are cross-verified and validated at multiple levels – by segment, region, application, and power output – to achieve a comprehensive and accurate market forecast from 2026 to 2034.
Data Accuracy & Quality Check
Maintaining a high standard of data accuracy (85-90%) is paramount. Our quality control process includes:
Expert Validation: All market figures, growth rates, and qualitative insights are validated through iterative discussions with subject matter experts and primary interviewees.
Statistical Analysis: Advanced statistical tools are utilized to identify trends, correlations, and outliers in the collected data, ensuring the robustness of our projections.
Peer Review: The entire research methodology, data analysis, and report drafting undergo rigorous internal peer review by senior analysts to eliminate biases and enhance the quality of findings.
Scenario Analysis: We conduct various scenario analyses (optimistic, pessimistic, realistic) to account for potential market uncertainties and provide a balanced forecast range.
Frequently Asked Questions
1. What technologies compete with Ammonia Fuel Cells?
Ammonia fuel cells offer an advantage for dense energy storage and long-range transport applications, competing primarily with direct hydrogen fuel cells that require advanced storage, and battery-electric systems limited by energy density. Their disruptive potential lies in efficient ammonia-to-electricity conversion across various power outputs.
2. Who are the key investors in Ammonia Fuel Cell technology?
While specific funding rounds are not detailed, active companies such as Amogy, GenCell Energy, and AFC Energy indicate significant investment interest in the ammonia fuel cell sector. The market's projected 6.3% CAGR from a $4.43 billion base in 2025 positions it as a growing area for capital deployment.
3. What challenges face the Ammonia Fuel Cell market?
Key challenges for ammonia fuel cells include optimizing the efficiency and scalability of ammonia cracking technology, developing robust infrastructure for ammonia supply and distribution, and ensuring stringent safety protocols for ammonia handling. These factors influence the pace of market adoption and operational deployment.
4. Why is demand for Ammonia Fuel Cells increasing?
Demand is increasing due to global decarbonization efforts, particularly for sustainable marine propulsion and heavy-duty transport applications seeking cleaner energy alternatives. Ammonia's high volumetric hydrogen density and easier storage compared to pure hydrogen make it a critical clean fuel source for Power Generation and Industrial uses. The market is expected to grow with a 6.3% CAGR.
5. How are Ammonia Fuel Cell technologies evolving?
Technological evolution focuses on enhancing the efficiency and durability of Proton Exchange Membrane Fuel Cells (PEMFC) and Solid Oxide Fuel Cells (SOFC) adapted for ammonia. R&D trends include developing advanced catalysts for efficient ammonia cracking and improving overall system integration for diverse power output requirements in segments like Marine and Automotive.
6. Which sectors primarily use Ammonia Fuel Cells?
Key application sectors for ammonia fuel cells include Transport, particularly Marine, alongside Power Generation and Industrial uses, leveraging them for clean electricity production. Different types, such as Solid Oxide Fuel Cells (SOFC) and Proton Exchange Membrane Fuel Cells (PEMFC), cater to specific power output and operational requirements across these end-use industries.