Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
Lithium-ion Battery Foil by Application (Car, Consumer electronics, Industry, Other), by Types (Aluminum Foil, Copper Foil, Other), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Jul 29, 2026|Base Year : 2025|Pages : 113
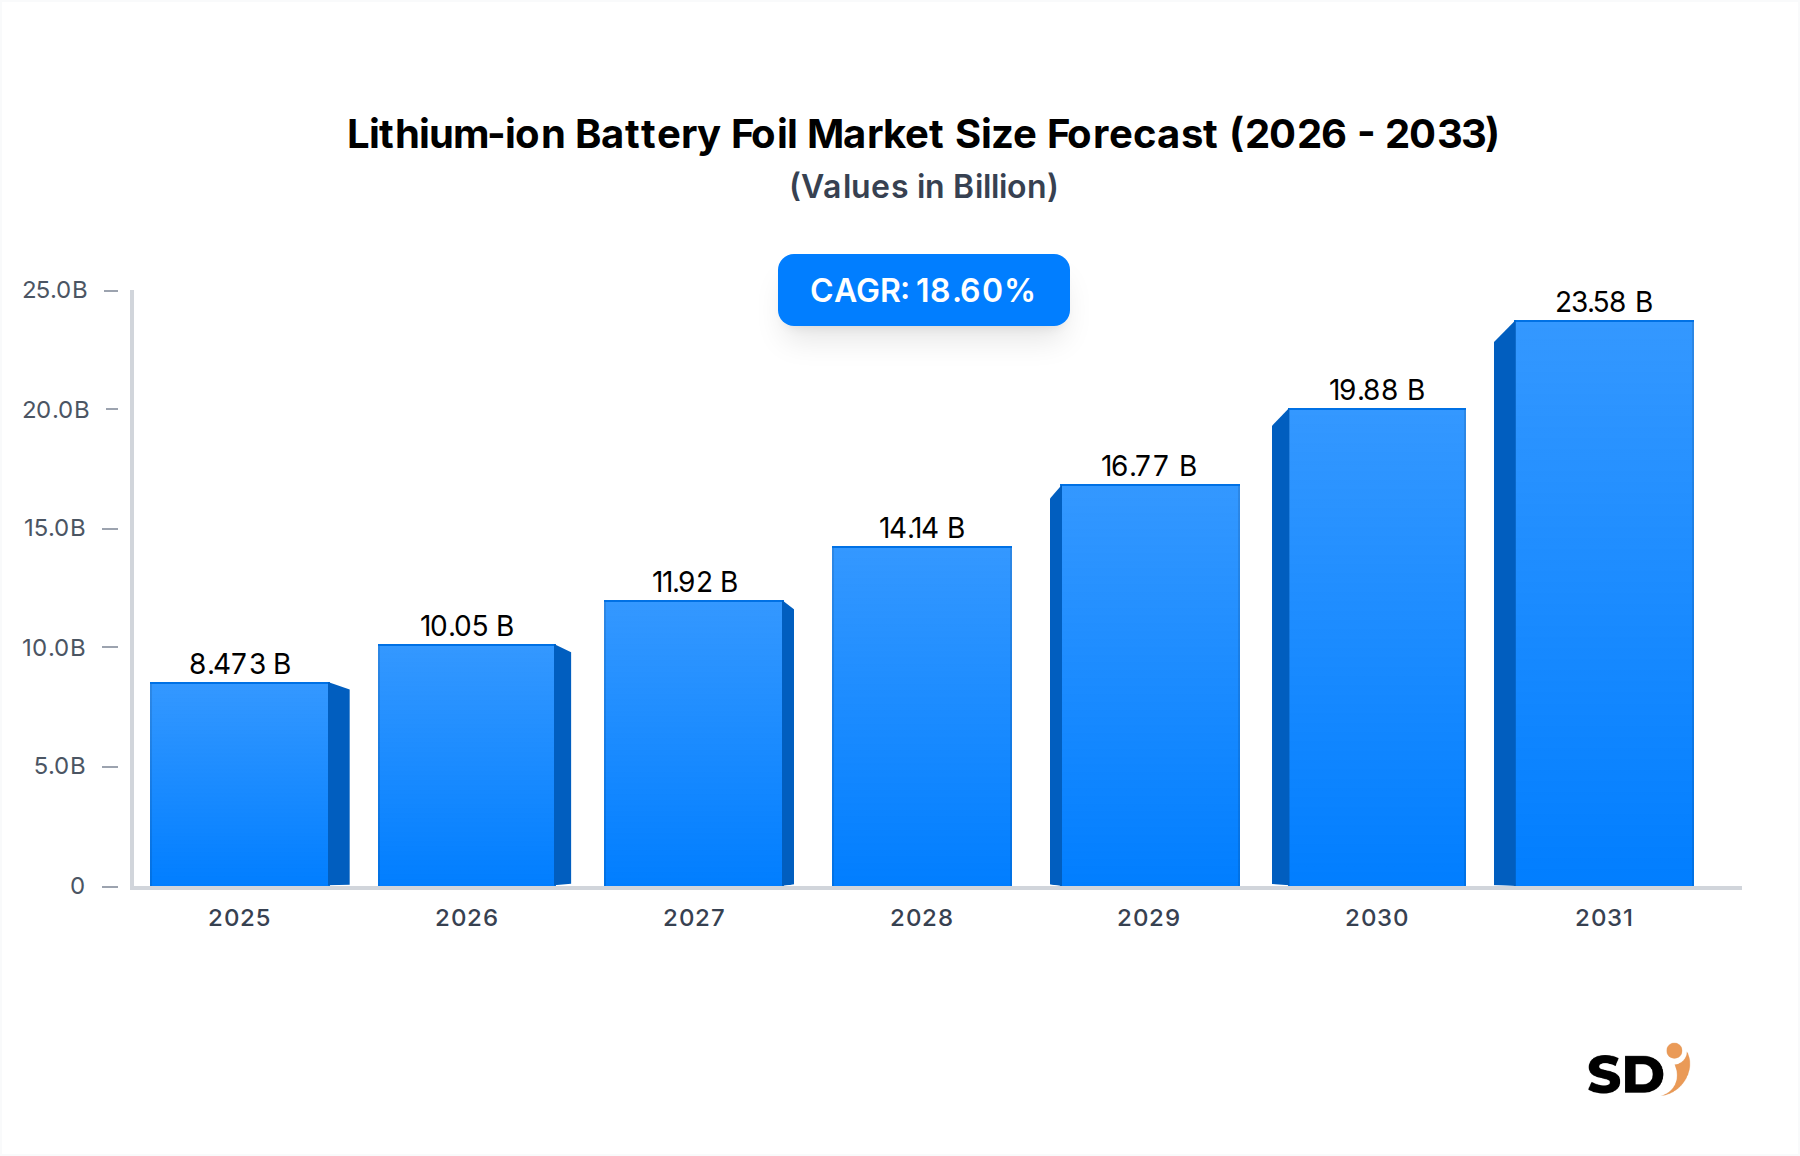
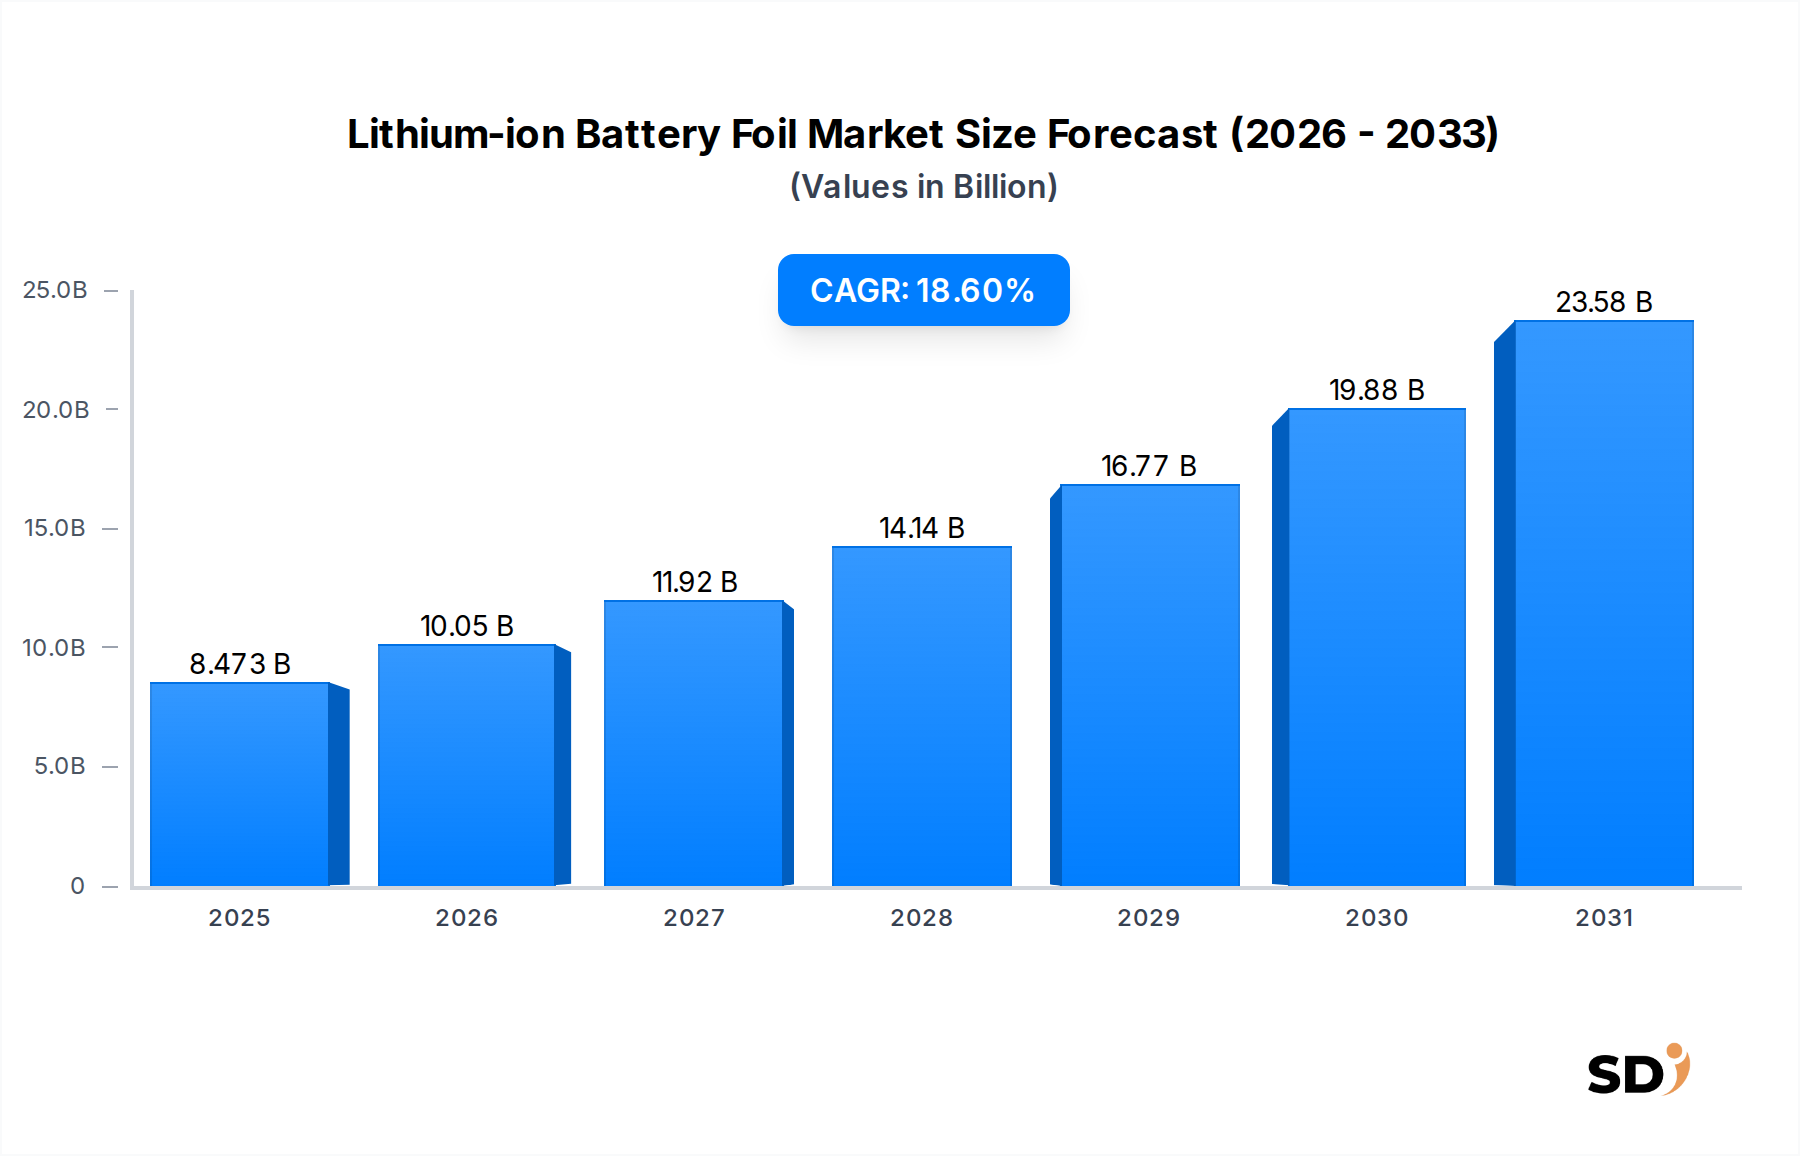
The Lithium-ion Battery Foil Market is poised for substantial expansion, driven primarily by the escalating demand from the electric vehicle (EV) sector and advancements in energy storage solutions. Our analysis indicates a robust market trajectory, underscored by critical performance metrics detailed below:
Lithium-ion Battery Foil Market Size (In Billion)
25.0B
20.0B
15.0B
10.0B
5.0B
0
8.473 B
2025
10.05 B
2026
11.92 B
2027
14.14 B
2028
16.77 B
2029
19.88 B
2030
23.58 B
2031
Market at a Glance
The global Lithium-ion Battery Foil Market is undergoing a transformative period, primarily fueled by the accelerating transition to electromobility and the increasing need for grid-scale energy storage. The market, valued at an estimated $2192.8 million in the base year, is projected to surge to $8473.4 million by 2034, exhibiting an impressive CAGR of 18.6% during the forecast period from 2026 to 2034. This growth is intrinsically linked to the performance characteristics of battery foils, which are critical components determining battery energy density, power output, safety, and lifespan. Both aluminum and copper foils serve as current collectors for the cathode and anode, respectively, with increasing pressure on manufacturers to produce thinner, lighter, and more conductive materials.
The strategic imperatives for market players revolve around enhancing production efficiency, investing in R&D for next-generation foil technologies, and securing resilient supply chains for raw materials. The Electric Vehicle Market remains the predominant consumption segment, absorbing a significant portion of foil production due to the escalating demand for high-performance lithium-ion batteries. Asia Pacific, led by China, South Korea, and Japan, continues its dominance in both battery manufacturing and foil production, establishing itself as the undisputed growth corridor. Regulatory tailwinds promoting decarbonization and significant government subsidies for EV adoption and battery production globally are acting as powerful catalysts, ensuring sustained demand across the value chain. However, challenges related to raw material price volatility, particularly within the Copper Market and Aluminum Market, and the capital-intensive nature of advanced foil manufacturing, persist as critical considerations for market stakeholders.
Segment Deep-Dive: Electric Vehicle Application Dominance in Lithium-ion Battery Foil Market
The Electric Vehicle Market stands as the unequivocal cornerstone of demand within the Lithium-ion Battery Foil Market, driving unprecedented growth and technological innovation. The imperative for higher energy density, faster charging capabilities, and extended battery life in EVs directly translates to stringent requirements for current collector foils. The rapid global shift towards electromobility, propelled by tightening emission standards, government incentives, and increasing consumer acceptance, positions the EV segment to retain its dominance throughout the forecast period. This application is not merely expanding; it is dictating the trajectory of materials science within the Lithium-ion Battery Market.
Copper Foil's Critical Role in EV Anodes
Within the EV battery architecture, copper foil is exclusively used as the current collector for the anode. Its superior electrical conductivity, ductility, and corrosion resistance make it indispensable for efficient electron flow and mechanical stability during charge-discharge cycles. The Copper Foil Market is particularly sensitive to the rapid scaling of gigafactories globally. Manufacturers are under constant pressure to develop ultra-thin foils (typically 6-8 µm, with efforts towards 4 µm or less) to maximize active material loading, thereby increasing battery energy density and extending EV range. The demand for higher purity copper (99.99% or more) and enhanced tensile strength to withstand the electrode coating process is also a critical factor.
Aluminum Foil for High-Voltage Cathodes
Similarly, aluminum foil serves as the current collector for the cathode, a segment crucial for high-voltage stability and lightweighting. The Aluminum Foil Market for Li-ion batteries benefits from aluminum's excellent conductivity and corrosion resistance at high electrochemical potentials. As battery chemistries evolve towards higher nickel content (e.g., NMC 811, NCA) to boost energy density, the demands on aluminum foil for improved corrosion resistance and mechanical integrity intensify. Innovations in surface treatment and alloy compositions are paramount to prevent delamination and ensure long-term battery performance, especially under aggressive cycling conditions in the Electric Vehicle Market.
Emerging Applications and Material Innovation
While EVs dominate, the Consumer Electronics Market (smartphones, laptops, wearables) and industrial applications (power tools, uninterruptible power supplies, grid storage) also contribute significantly, albeit with different scale and performance requirements. The ongoing research into solid-state batteries and silicon-anode batteries, which require novel current collector designs and materials, will also influence the long-term dynamics of both the Copper Foil Market and Aluminum Foil Market. The overarching trend is towards thinner, lighter, and more robust foils, often achieved through advanced electrodeposition or rolling techniques, ensuring the segment's share continues to expand through innovation rather than facing margin pressure.
The Lithium-ion Battery Foil Market's growth is propelled by a confluence of macroeconomic trends and technological advancements, while simultaneously facing significant headwinds from operational complexities and supply chain dynamics.
Key Market Drivers:
Explosive Growth in Electric Vehicle Adoption: The primary driver is the unprecedented global surge in electric vehicle (EV) sales. Government policies, such as emission mandates and consumer subsidies in major economies, are accelerating the transition away from internal combustion engines. This directly translates to escalating demand for high-performance lithium-ion batteries, where specialized foils are critical components. The expanding Electric Vehicle Market ensures sustained, high-volume requirements for both copper and aluminum foils.
Advancements in Battery Technology: Continuous innovations in Lithium-ion Battery Market chemistries, particularly towards higher energy density and faster charging, necessitate thinner, stronger, and more conductive foils. Research into advanced materials and manufacturing processes for foils that can withstand higher voltage and current densities is driving demand for premium products.
Expansion of Grid-Scale Energy Storage Systems (ESS): Beyond EVs, large-scale energy storage projects for renewable integration and grid stabilization are gaining traction. These utility-scale batteries, requiring substantial volumes of durable and cost-effective foils, represent a significant growth opportunity for the Lithium-ion Battery Market components, including foils.
Government Initiatives and Subsidies: Many nations are implementing aggressive policies to foster domestic battery manufacturing capabilities and EV production. These initiatives, including tax credits, grants, and infrastructure development, directly stimulate investment across the entire battery supply chain, creating a favorable environment for the Lithium-ion Battery Foil Market.
Growth Restraints:
Volatility in Raw Material Prices: The Copper Market and Aluminum Market are susceptible to significant price fluctuations driven by global supply-demand dynamics, geopolitical events, and speculative trading. These raw material cost instabilities directly impact the production costs of battery foils, making long-term strategic planning and consistent pricing challenging for manufacturers.
Complex and Capital-Intensive Manufacturing: Producing ultra-thin, high-purity battery foils with precise mechanical and electrical properties requires sophisticated manufacturing processes and substantial capital investment in specialized equipment. This high barrier to entry limits the number of new players and can slow down capacity expansion, potentially creating supply bottlenecks, particularly for advanced foil types.
Geopolitical and Supply Chain Risks: The concentration of raw material mining, processing, and foil manufacturing in specific regions (e.g., China for a significant portion of copper foil production) exposes the supply chain to geopolitical risks, trade disputes, and logistics disruptions, affecting global market stability.
Environmental and Energy Footprint: The production of base metals like aluminum and copper, and subsequently foils, is energy-intensive and has an environmental footprint. Increasing regulatory scrutiny over sustainable production practices and carbon emissions could add compliance costs and operational complexities for manufacturers.
The Lithium-ion Battery Foil Market is characterized by a concentrated competitive landscape, with a few major players dominating production, particularly in advanced foil grades. These companies are heavily investing in R&D and capacity expansion to keep pace with the exponential growth of the Lithium-ion Battery Market.
Fukuda: A key Japanese manufacturer known for its high-precision copper foils, serving various segments including the Electric Vehicle Market and high-performance electronics.
Mitsui Mining & Smelting: A diversified Japanese conglomerate with significant presence in copper foil production, catering to high-end battery applications and advanced packaging.
Hitachi Cable: A prominent player offering a range of copper foils for circuit boards and battery applications, focusing on high-quality and reliability standards.
Furukawa Electric: Specializes in high-performance copper foil products, often tailored for advanced Lithium-ion Battery Market applications requiring superior electrical properties.
JX Nippon Mining & Metal: A leading Japanese integrated non-ferrous metal company, providing high-purity copper foils essential for anode current collectors in advanced batteries.
Olin Brass: A significant North American producer of copper and copper alloy materials, with specialized offerings extending into high-tech applications, including foil for battery and electronics.
Circuit Foil: A European leader in electrodeposited copper foils, known for its high-performance products used in PCBs and increasingly in the Lithium-ion Battery Market.
LS Mtron: A major South Korean manufacturer with a strong focus on copper foils for battery and PCB applications, leveraging advanced technology to meet market demands.
Iljin Materials: A South Korean company recognized for its extensive production of 'Elecfoil,' a high-quality copper foil widely adopted by leading battery manufacturers, especially in the Electric Vehicle Market.
CCP (Chang Chun Petrochemical): A Taiwanese chemical company with a significant presence in electrodeposited copper foil, serving both the Consumer Electronics Market and the evolving battery sector.
NPC (Nippon Poly-Creative): Japanese manufacturer contributing to the battery materials sector with its specialized foil products.
Co-Tech: An Asian manufacturer involved in the production of various foil types, including those applicable for battery components.
LYCT (Luoyang Copper & Aluminum Processing Co., Ltd.): A major Chinese player in copper and aluminum processing, including battery foils, benefiting from the robust domestic EV market.
Jinbao Electronics: A Chinese manufacturer with capabilities in producing electronic foils that can be adapted for lithium-ion battery current collectors.
Kingboard Chemical: A diversified manufacturer based in Hong Kong, with interests in laminates and copper foil, supporting the electronics and battery industries.
NUODE (Zhongshan Nuode Battery Material Co., Ltd.): A leading Chinese producer of high-precision copper foil, critically positioned to supply the surging domestic and international Lithium-ion Battery Market.
Tongling Nonferrous Metal Group: A state-owned enterprise in China, a major producer of copper and related products, including foils for batteries and other industrial uses.
Targray: A global supplier of battery materials, including specialized foils, offering comprehensive solutions for the Lithium-ion Battery Market.
UACJ: A major Japanese aluminum manufacturer, contributing aluminum foils to various industries, including those requiring high-quality current collectors for cathodes.
Strategic Milestones & Recent Developments in Lithium-ion Battery Foil Market
The Lithium-ion Battery Foil Market has witnessed a series of significant strategic developments, primarily aimed at scaling production capacity, enhancing material properties, and securing supply chains to meet the burgeoning demand from the Electric Vehicle Market.
Q4 2023: Iljin Materials (now LOTTE Energy Materials) announced plans for a significant expansion of its copper foil production capacity in Malaysia, aiming to cater to global battery manufacturers, particularly those supplying the European and North American Electric Vehicle Market.
Q3 2023: NUODE, a prominent Chinese copper foil producer, continued to invest heavily in R&D for ultra-thin (4-micron) copper foils, vital for next-generation high-energy-density batteries, solidifying its position in the Copper Foil Market.
Q2 2023: Several major Aluminum Foil Market players reported increased R&D efforts in surface-treated and alloyed aluminum foils to improve corrosion resistance and bonding strength for high-voltage cathode materials in Lithium-ion Battery Market applications.
Q1 2023: JX Nippon Mining & Metal expanded its specialized copper foil production lines in Japan, focusing on high-purity and high-strength foils for automotive battery applications, indicating a proactive approach to the Electric Vehicle Market.
Q4 2022: Furukawa Electric announced a partnership with a leading battery cell manufacturer to co-develop advanced electrode foils optimized for extreme fast charging capabilities, showcasing cross-industry collaboration.
Q3 2022: There was a general trend among leading battery foil manufacturers to secure long-term supply agreements with raw material suppliers in the Copper Market and Aluminum Market to mitigate price volatility and ensure stable production amidst global supply chain disruptions.
Q2 2022: Fukuda invested in new production technology to improve the uniformity and reduce the thickness of its electrodeposited copper foils, aiming to enhance the energy density of batteries used in the Consumer Electronics Market and electric vehicles.
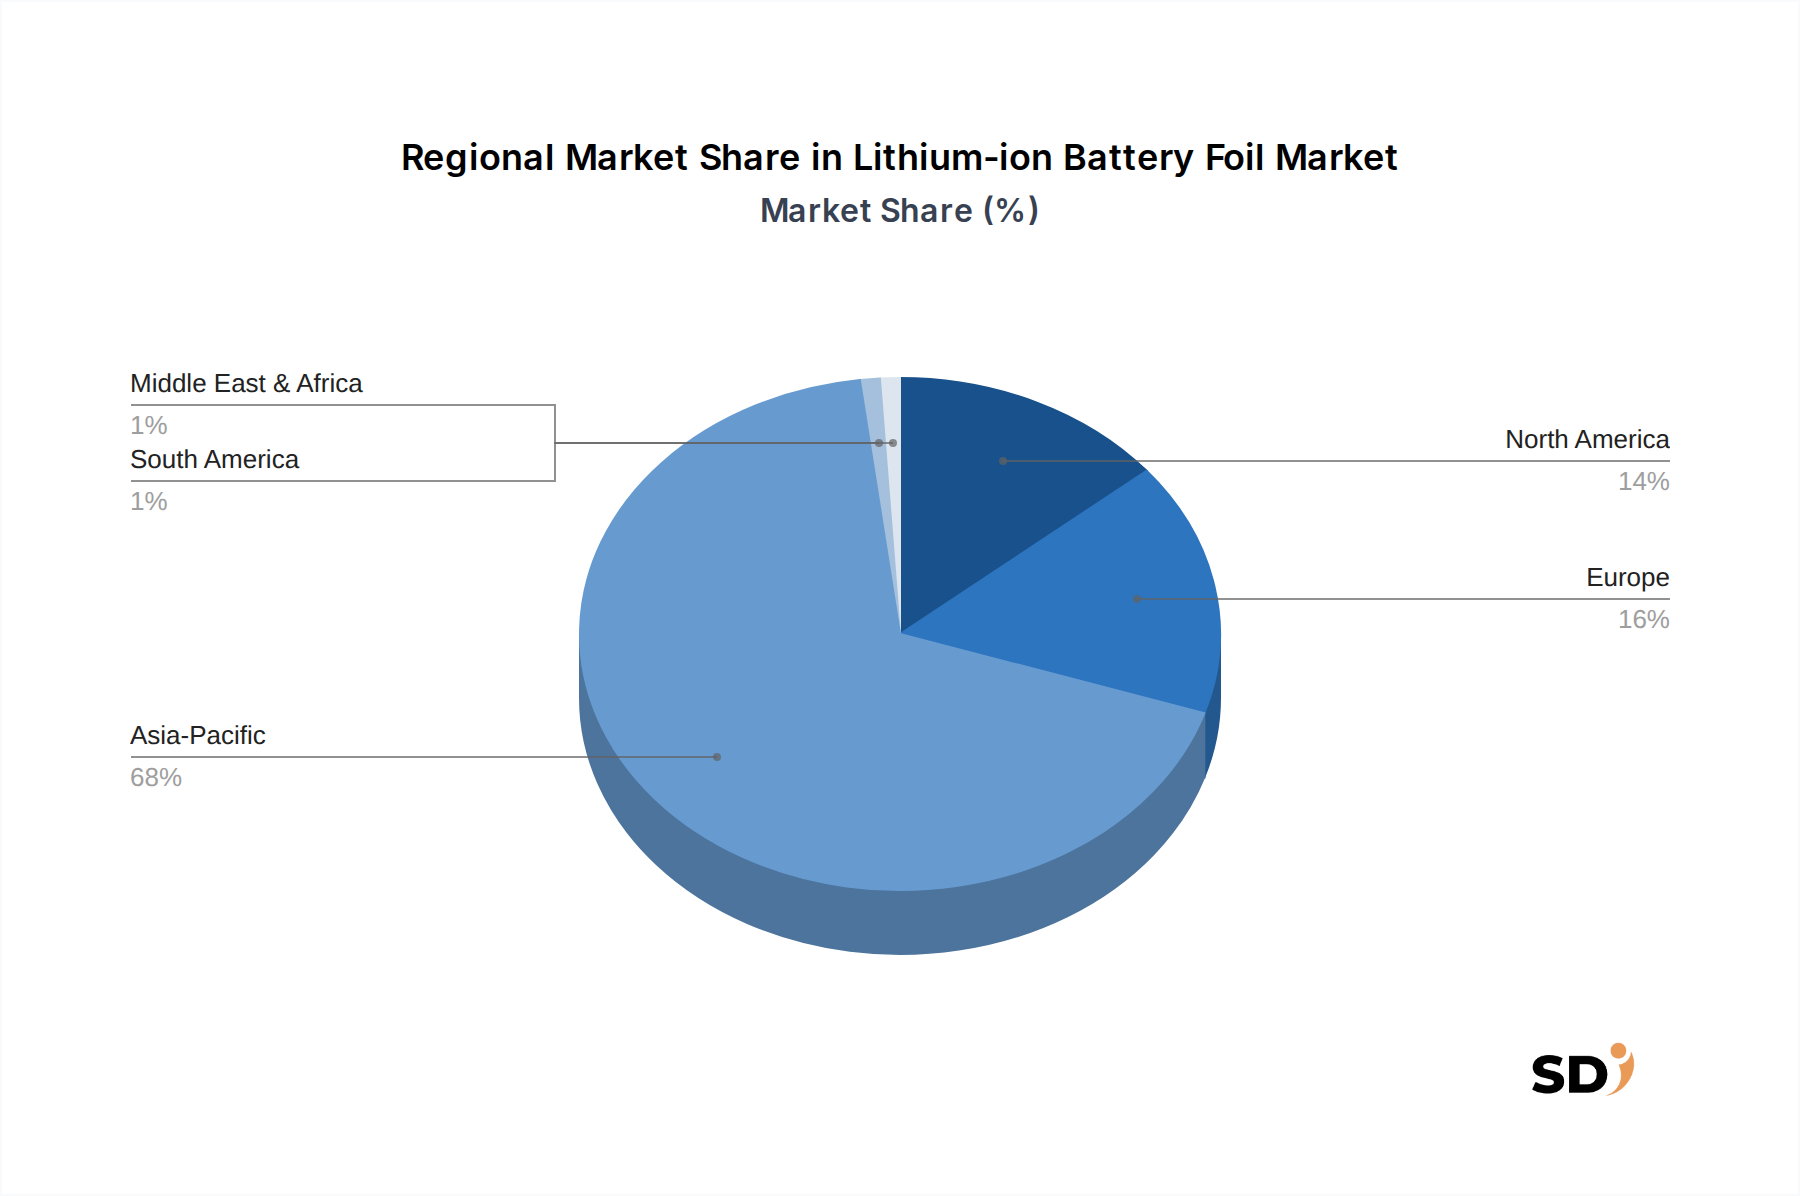
The global Lithium-ion Battery Foil Market exhibits distinct regional dynamics, influenced by local manufacturing capabilities, EV adoption rates, and regulatory frameworks. Asia Pacific remains the dominant force, while other regions are rapidly scaling up their participation.
Asia Pacific: The Undisputed Leader
Asia Pacific commands the largest share of the Lithium-ion Battery Foil Market, driven primarily by the colossal battery manufacturing ecosystems in China, South Korea, and Japan. This region is also the fastest-growing due to aggressive government support for EVs, substantial domestic demand, and the presence of major global battery cell producers (e.g., CATL, LG Energy Solution, Samsung SDI, Panasonic). China, in particular, leads in both battery production capacity and Electric Vehicle Market penetration, ensuring immense demand for both Copper Foil Market and Aluminum Foil Market products. Regional CAGR is projected to be the highest, reflecting continued investment in gigafactories and advanced material development. Policy frameworks promoting electric mobility and energy storage across the region further solidify its market position.
Europe: Rapidly Emerging Hub
Europe is experiencing robust growth, transitioning from a nascent Lithium-ion Battery Market to a significant hub for battery cell production. This growth is spurred by the EU's ambitious decarbonization targets, the "European Battery Alliance" initiatives, and substantial investments by automotive OEMs in local EV manufacturing. Countries like Germany, France, and Poland are seeing the establishment of large-scale battery factories, creating a strong demand pull for battery foils. Regulatory efforts to localize the supply chain are a primary demand driver, aiming to reduce reliance on Asian imports.
North America: Strategic Build-Up
The North American market, particularly the United States, is undergoing a strategic build-up phase. The Inflation Reduction Act (IRA) and other federal initiatives are incentivizing domestic battery and EV production, leading to considerable investments in new manufacturing plants. While historically reliant on imports, the region is now focused on establishing a robust local supply chain for battery materials, including foils. This will drive significant demand growth for the Copper Foil Market and Aluminum Foil Market within the region, positioning it as an important growth corridor in the medium to long term, though still maturing compared to Asia Pacific.
Middle East & Africa (MEA) and Latin America (LAMEA): Nascent Opportunities
These regions currently hold a comparatively smaller share of the global Lithium-ion Battery Foil Market. However, specific countries within LAMEA, such as Brazil and Argentina, show potential due to nascent EV adoption and increasing interest in local battery assembly. The MEA region, particularly the GCC countries, is exploring diversification away from fossil fuels, with potential investments in renewable energy and associated storage, which could stimulate demand for foils. While growth is slower, strategic investments in resource extraction and preliminary processing could create future opportunities, especially for raw material suppliers in the Copper Market and Aluminum Market.
Supply Chain & Raw Material Dynamics: Lithium-ion Battery Foil Market
The robustness and resilience of the Lithium-ion Battery Foil Market are inherently tied to the stability and cost-efficiency of its upstream supply chain, particularly regarding critical raw materials. The production of battery-grade foils is highly dependent on a consistent supply of high-purity copper and aluminum.
Upstream Dependencies and Sourcing Risks:
Copper Dependence: The Copper Foil Market relies heavily on the global Copper Market. Major copper producing nations include Chile, Peru, China, and the Democratic Republic of Congo. Geopolitical instabilities, labor disputes, and environmental regulations in these regions can significantly impact global copper prices and availability. Furthermore, the refining and electrodeposition processes for battery-grade copper foil require extremely high purity copper cathodes, adding another layer of specialization and limited suppliers.
Aluminum Dependence: Similarly, the Aluminum Foil Market is contingent on the Aluminum Market, with primary production concentrated in China, Russia, Canada, and India. Aluminum production is incredibly energy-intensive, making it susceptible to energy price fluctuations and regional power supply issues. Sourcing risks also involve trade policies and tariffs, which can disrupt established supply routes.
Precursor Materials and Additives: Beyond the primary metals, the production of advanced foils often involves specific additives and surface treatment chemicals from the Advanced Materials Market. Dependencies on specialized chemical suppliers for these precursors introduce additional complexity and potential bottlenecks.
Price Volatility and Historical Disruptions:
Both copper and aluminum have experienced significant price volatility in recent years. For instance, the Copper Market saw sharp price increases during the COVID-19 pandemic due to supply chain disruptions and surging demand from electrification trends. The Aluminum Market also faced supply constraints stemming from energy crises and production curtailments in major producing regions. These fluctuations directly impact the cost of battery foils, influencing manufacturers' profit margins and the ultimate cost of lithium-ion batteries. Long-term procurement contracts and hedging strategies are common but do not fully insulate manufacturers from extreme market shifts. Historically, disruptions have included mining strikes, smelter outages, and transportation bottlenecks, all reverberating through the foil supply chain.
Energy Intensity and Environmental Considerations:
The manufacturing of both primary copper and aluminum, as well as their subsequent conversion into ultra-thin foils, is highly energy-intensive. This necessitates reliable and often costly energy sources. Concerns over the carbon footprint of these processes are driving investments in more sustainable mining and production methods, including green aluminum initiatives and recycling technologies, which will incrementally alter supply chain dynamics and potentially add to material costs.
The regulatory and policy landscape significantly shapes the operational environment and strategic direction of the Lithium-ion Battery Foil Market. These frameworks cover everything from environmental compliance and safety standards to trade regulations and industry incentives, impacting manufacturing, sourcing, and market access across key geographies.
Environmental Regulations:
REACH (Registration, Evaluation, Authorisation and Restriction of Chemicals) in Europe: This regulation profoundly impacts manufacturers and importers of chemical substances, including those used in foil production (e.g., surface treatments, electrolytes). Compliance with REACH ensures chemicals are safely managed and restricts hazardous substances, potentially influencing material choices and production processes for the Copper Foil Market and Aluminum Foil Market.
Local EPA/Environmental Standards (North America, APAC): Strict local environmental protection agency (EPA) standards govern emissions, waste disposal, and water discharge from foil manufacturing facilities. These regulations often require significant capital investment in pollution control technologies and sustainable practices, particularly in regions like China and South Korea, which are major foil producers.
Safety and Quality Standards:
ISO 9001 (Quality Management): Widely adopted, ISO 9001 certification ensures consistent quality in the manufacturing processes of battery foils, which is critical for their performance and safety within Lithium-ion Battery Market applications.
ISO/TS 16949 (now IATF 16949 for Automotive): For foils destined for the Electric Vehicle Market, compliance with IATF 16949 is often mandatory. This standard specifies quality management system requirements for the automotive industry, ensuring product reliability and traceability, crucial given the safety-critical nature of EV batteries.
UN 38.3 (Transport of Lithium Batteries): While directly related to the final battery product, regulations concerning the safe transport of lithium-ion batteries indirectly influence the specifications and handling of battery components, including foils, to ensure overall product integrity and safety during logistics.
Government Policies and Incentives:
US Inflation Reduction Act (IRA): The IRA provides significant tax credits and incentives for the domestic production of EVs and battery components, including foils, in the United States. This policy aims to reshore manufacturing, reduce reliance on foreign supply chains, and bolster local demand for the Lithium-ion Battery Market materials. It is a major catalyst for new investments in North American foil manufacturing capacity.
European Green Deal & Battery Alliance: The European Union's ambitious environmental targets and the "European Battery Alliance" seek to establish a competitive and sustainable battery industry within Europe. Policies include funding for R&D, grants for gigafactory construction, and regulations promoting circularity and responsible sourcing. This creates a strong incentive for foil manufacturers to establish or expand operations in Europe.
China's Industrial Policies: China has long implemented robust industrial policies and subsidies to foster its domestic Lithium-ion Battery Market and associated supply chains, including copper and aluminum foil production. While some direct subsidies are being scaled back, strong domestic demand from the Electric Vehicle Market and strategic national development plans continue to support local foil manufacturers.
Projected Compliance Impacts:
Increasing regulatory scrutiny on supply chain transparency, ethical sourcing, and environmental impact (e.g., carbon footprint of aluminum/copper production) is expected to drive up compliance costs. Manufacturers will need to invest in more sustainable production technologies, enhance traceability systems, and potentially diversify their raw material sourcing to meet evolving regional requirements. These policy shifts are fundamentally reshaping the competitive landscape and encouraging localized production, particularly in North America and Europe, to secure critical materials for the burgeoning Electric Vehicle Market.
Lithium-ion Battery Foil Segmentation
1. Application
1.1. Car
1.2. Consumer electronics
1.3. Industry
1.4. Other
2. Types
2.1. Aluminum Foil
2.2. Copper Foil
2.3. Other
Lithium-ion Battery Foil Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Lithium-ion Battery Foil REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 18.6% from 2020-2034
Segmentation
By Application
Car
Consumer electronics
Industry
Other
By Types
Aluminum Foil
Copper Foil
Other
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Application
5.1.1. Car
5.1.2. Consumer electronics
5.1.3. Industry
5.1.4. Other
5.2. Market Analysis, Insights and Forecast - by Types
5.2.1. Aluminum Foil
5.2.2. Copper Foil
5.2.3. Other
5.3. Market Analysis, Insights and Forecast - by Region
5.3.1. North America
5.3.2. South America
5.3.3. Europe
5.3.4. Middle East & Africa
5.3.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Application
6.1.1. Car
6.1.2. Consumer electronics
6.1.3. Industry
6.1.4. Other
6.2. Market Analysis, Insights and Forecast - by Types
6.2.1. Aluminum Foil
6.2.2. Copper Foil
6.2.3. Other
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Application
7.1.1. Car
7.1.2. Consumer electronics
7.1.3. Industry
7.1.4. Other
7.2. Market Analysis, Insights and Forecast - by Types
7.2.1. Aluminum Foil
7.2.2. Copper Foil
7.2.3. Other
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Application
8.1.1. Car
8.1.2. Consumer electronics
8.1.3. Industry
8.1.4. Other
8.2. Market Analysis, Insights and Forecast - by Types
8.2.1. Aluminum Foil
8.2.2. Copper Foil
8.2.3. Other
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Application
9.1.1. Car
9.1.2. Consumer electronics
9.1.3. Industry
9.1.4. Other
9.2. Market Analysis, Insights and Forecast - by Types
9.2.1. Aluminum Foil
9.2.2. Copper Foil
9.2.3. Other
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Application
10.1.1. Car
10.1.2. Consumer electronics
10.1.3. Industry
10.1.4. Other
10.2. Market Analysis, Insights and Forecast - by Types
10.2.1. Aluminum Foil
10.2.2. Copper Foil
10.2.3. Other
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Fukuda
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Mitsui Mining & Smelting
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Hitachi Cable
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Furukawa Electric
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. JX Nippon Mining & Metal
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Olin Brass
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Circuit Foil
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. LS Mtron
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Iljin Materials
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. CCP
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. NPC
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. Co-Tech
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. LYCT
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. Jinbao Electronics
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.1.15. Kingboard Chemical
11.1.15.1. Company Overview
11.1.15.2. Products
11.1.15.3. Company Financials
11.1.15.4. SWOT Analysis
11.1.16. NUODE
11.1.16.1. Company Overview
11.1.16.2. Products
11.1.16.3. Company Financials
11.1.16.4. SWOT Analysis
11.1.17. Tongling Nonferrous Metal Group
11.1.17.1. Company Overview
11.1.17.2. Products
11.1.17.3. Company Financials
11.1.17.4. SWOT Analysis
11.1.18. Targray
11.1.18.1. Company Overview
11.1.18.2. Products
11.1.18.3. Company Financials
11.1.18.4. SWOT Analysis
11.1.19. UACJ
11.1.19.1. Company Overview
11.1.19.2. Products
11.1.19.3. Company Financials
11.1.19.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Lithium-ion Battery Foil Revenue Breakdown (million, %) by Region 2026 & 2034
Figure 2: North America Lithium-ion Battery Foil Revenue (million), by Application 2026 & 2034
Figure 3: North America Lithium-ion Battery Foil Revenue Share (%), by Application 2026 & 2034
Figure 4: North America Lithium-ion Battery Foil Revenue (million), by Types 2026 & 2034
Figure 5: North America Lithium-ion Battery Foil Revenue Share (%), by Types 2026 & 2034
Figure 6: North America Lithium-ion Battery Foil Revenue (million), by Country 2026 & 2034
Figure 7: North America Lithium-ion Battery Foil Revenue Share (%), by Country 2026 & 2034
Figure 8: South America Lithium-ion Battery Foil Revenue (million), by Application 2026 & 2034
Figure 9: South America Lithium-ion Battery Foil Revenue Share (%), by Application 2026 & 2034
Figure 10: South America Lithium-ion Battery Foil Revenue (million), by Types 2026 & 2034
Figure 11: South America Lithium-ion Battery Foil Revenue Share (%), by Types 2026 & 2034
Figure 12: South America Lithium-ion Battery Foil Revenue (million), by Country 2026 & 2034
Figure 13: South America Lithium-ion Battery Foil Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Lithium-ion Battery Foil Revenue (million), by Application 2026 & 2034
Figure 15: Europe Lithium-ion Battery Foil Revenue Share (%), by Application 2026 & 2034
Figure 16: Europe Lithium-ion Battery Foil Revenue (million), by Types 2026 & 2034
Figure 17: Europe Lithium-ion Battery Foil Revenue Share (%), by Types 2026 & 2034
Figure 18: Europe Lithium-ion Battery Foil Revenue (million), by Country 2026 & 2034
Figure 19: Europe Lithium-ion Battery Foil Revenue Share (%), by Country 2026 & 2034
Figure 20: Middle East & Africa Lithium-ion Battery Foil Revenue (million), by Application 2026 & 2034
Figure 21: Middle East & Africa Lithium-ion Battery Foil Revenue Share (%), by Application 2026 & 2034
Figure 22: Middle East & Africa Lithium-ion Battery Foil Revenue (million), by Types 2026 & 2034
Figure 23: Middle East & Africa Lithium-ion Battery Foil Revenue Share (%), by Types 2026 & 2034
Figure 24: Middle East & Africa Lithium-ion Battery Foil Revenue (million), by Country 2026 & 2034
Figure 25: Middle East & Africa Lithium-ion Battery Foil Revenue Share (%), by Country 2026 & 2034
Figure 26: Asia Pacific Lithium-ion Battery Foil Revenue (million), by Application 2026 & 2034
Figure 27: Asia Pacific Lithium-ion Battery Foil Revenue Share (%), by Application 2026 & 2034
Figure 28: Asia Pacific Lithium-ion Battery Foil Revenue (million), by Types 2026 & 2034
Figure 29: Asia Pacific Lithium-ion Battery Foil Revenue Share (%), by Types 2026 & 2034
Figure 30: Asia Pacific Lithium-ion Battery Foil Revenue (million), by Country 2026 & 2034
Figure 31: Asia Pacific Lithium-ion Battery Foil Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Lithium-ion Battery Foil Revenue million Forecast, by Application 2020 & 2034
Table 2: Lithium-ion Battery Foil Revenue million Forecast, by Types 2020 & 2034
Table 3: Lithium-ion Battery Foil Revenue million Forecast, by Region 2020 & 2034
Table 4: North America Lithium-ion Battery Foil Revenue million Forecast, by Application 2020 & 2034
Table 5: North America Lithium-ion Battery Foil Revenue million Forecast, by Types 2020 & 2034
Table 6: North America Lithium-ion Battery Foil Revenue million Forecast, by Country 2020 & 2034
Table 7: United States Lithium-ion Battery Foil Revenue (million) Forecast, by Application 2020 & 2034
Table 46: Rest of Asia Pacific Lithium-ion Battery Foil Revenue (million) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Our research methodology places a strong emphasis on primary research, constituting 70-80% of our total research effort. This robust approach ensures the most current and validated insights directly from industry stakeholders. We conduct extensive qualitative and quantitative interviews across the value chain of the Lithium-ion Battery Foil market, spanning key geographical regions including North America, South America, Europe, Middle East & Africa, and Asia Pacific. Our primary interviews are meticulously structured to gather granular data on market trends, competitive landscape, technological advancements, pricing dynamics, supply chain intricacies, and regulatory impacts.
Key participants in our primary research include:
Company Types:
Lithium-ion Battery Cell Manufacturers (e.g., CATL, LG Energy Solution, Panasonic)
Specialized Battery Material Suppliers (e.g., anode, cathode, electrolyte component providers)
Stakeholders Interviewed:
VP of Procurement & Supply Chain
Director of Battery R&D and Advanced Materials
Head of Strategic Sourcing & Vendor Management
Product Manager - Battery Components
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
VP of Procurement & Supply Chain
30%
Director of Battery R&D
25%
Head of Strategic Sourcing
25%
Product Manager - Battery Components
20%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Lithium-ion Battery Cell Manufacturers
25%
Battery Foil Manufacturers
25%
EV Manufacturers
20%
Consumer Electronics OEMs
15%
Specialized Battery Material Suppliers
15%
Secondary Research & Industry Benchmarking
Secondary research forms the remaining 20-30% of our methodology, serving as a foundational and corroborative layer to our primary findings. This stage involves an exhaustive review of published data from credible sources to establish a comprehensive understanding of the market's historical trajectory, current status, and future projections. Our rigorous approach ensures the exclusion of data from other market research websites.
Key secondary data sources include:
Financial & Corporate Databases: Bloomberg, Factiva, Hoovers, PitchBook for company financials, investment trends, and strategic developments.
Government Publications & Reports: Official documents from national and international government agencies (.gov) related to energy policy, automotive regulations, and material science.
Trade Associations & Industry Bodies: Publications and statistics from recognized industry associations (.org) that offer insights into industry standards, production volumes, and consumption trends. Examples include:
Company Annual Reports & Investor Presentations: Publicly available information from key market players to understand their strategies, financial performance, and market outlook.
Demand Modeling & Market Estimation
Our market sizing and forecasting methodologies leverage both top-down and bottom-up approaches, coupled with multi-level data triangulation, to ensure robustness and accuracy. The market is segmented by application, type, and region for detailed analysis.
Bottom-Up Approach: This method involves estimating market size from the ground up, aggregating demand from various end-use applications and segments. For the Lithium-ion Battery Foil market, this includes:
Total MWh capacity of lithium-ion batteries produced (by application - Car, Consumer Electronics, Industry - and region) multiplied by average foil content (kg/MWh or USD/MWh).
Number of Electric Vehicle (EV) unit sales by vehicle type and region, multiplied by the average battery pack size (kWh) per vehicle, and subsequently by the average foil material content or cost per kWh.
Average Selling Price (ASP) of battery foil per square meter or per metric ton, considering variations across aluminum and copper foil types and thicknesses.
Application-specific foil demand derived from production forecasts for key devices (e.g., smartphones, laptops) and stationary energy storage systems, incorporating their respective battery and foil requirements.
Top-Down Approach: This involves validating the bottom-up estimates by scrutinizing macro-economic indicators, overall industrial growth rates, and total addressable market (TAM) analysis for battery materials at a regional and global level.
Multi-Level Data Triangulation: Data from primary and secondary sources are rigorously cross-referenced and validated across multiple levels – industry experts, company financials, market reports, and association data – to resolve discrepancies and arrive at conclusive market figures.
Data Accuracy & Quality Check
Our commitment to data integrity is paramount. We guarantee an estimated data accuracy level of 85-90% for our market figures and forecasts. This high level of precision is achieved through:
Continuous Validation: All data points, assumptions, and models are subject to continuous validation through expert interviews and ongoing secondary research.
Expert Panel Review: Our findings are regularly reviewed by an internal panel of senior analysts and external industry experts to challenge methodologies and refine market insights.
Real-time Updates: Every report is updated with the latest market developments, technological breakthroughs, and regulatory changes up to the date of purchase, ensuring our clients receive the most current and relevant market intelligence.
Frequently Asked Questions
1. What are the primary challenges in the Lithium-ion Battery Foil market?
The market faces challenges related to raw material price volatility, particularly for copper and aluminum. Supply chain stability, exacerbated by geopolitical factors, also presents a restraint on consistent production and delivery for manufacturers like JX Nippon Mining & Metal and Tongling Nonferrous Metal Group.
2. How has the Lithium-ion Battery Foil market recovered post-pandemic, and what are the long-term shifts?
Post-pandemic recovery is driven by robust demand from electric vehicle (EV) and consumer electronics sectors. This accelerated the structural shift towards higher-performance foils, contributing to the market's projected 18.6% CAGR between 2026 and 2034.
3. Which regions dominate export-import dynamics in Lithium-ion Battery Foil?
Asia-Pacific, particularly China, South Korea, and Japan, holds significant export dominance due to established manufacturing bases for companies like Iljin Materials and NUODE. North America and Europe are major importers, fueling domestic gigafactory expansions and battery production capabilities.
4. Who are the leading companies in the Lithium-ion Battery Foil competitive landscape?
Key players include Fukuda, Mitsui Mining & Smelting, Hitachi Cable, Furukawa Electric, JX Nippon Mining & Metal, Olin Brass, and Circuit Foil. Asian manufacturers like Iljin Materials and NUODE hold substantial market presence, driving innovation in both copper and aluminum foil segments.
5. What disruptive technologies or substitutes impact Lithium-ion Battery Foil?
Advances in ultra-thin foil production and improved adhesion technologies are enhancing existing lithium-ion battery foil performance. While no direct substitutes for current foil types are widely commercialized, research into solid-state batteries could eventually alter traditional foil demand profiles.
6. How does the regulatory environment affect the Lithium-ion Battery Foil market?
Regulations on battery safety, material sourcing, and environmental compliance, particularly in Europe and North America, directly impact manufacturing processes and product specifications. This drives demand for high-quality, sustainably produced foils from suppliers such as Targray and UACJ, influencing trade policies.