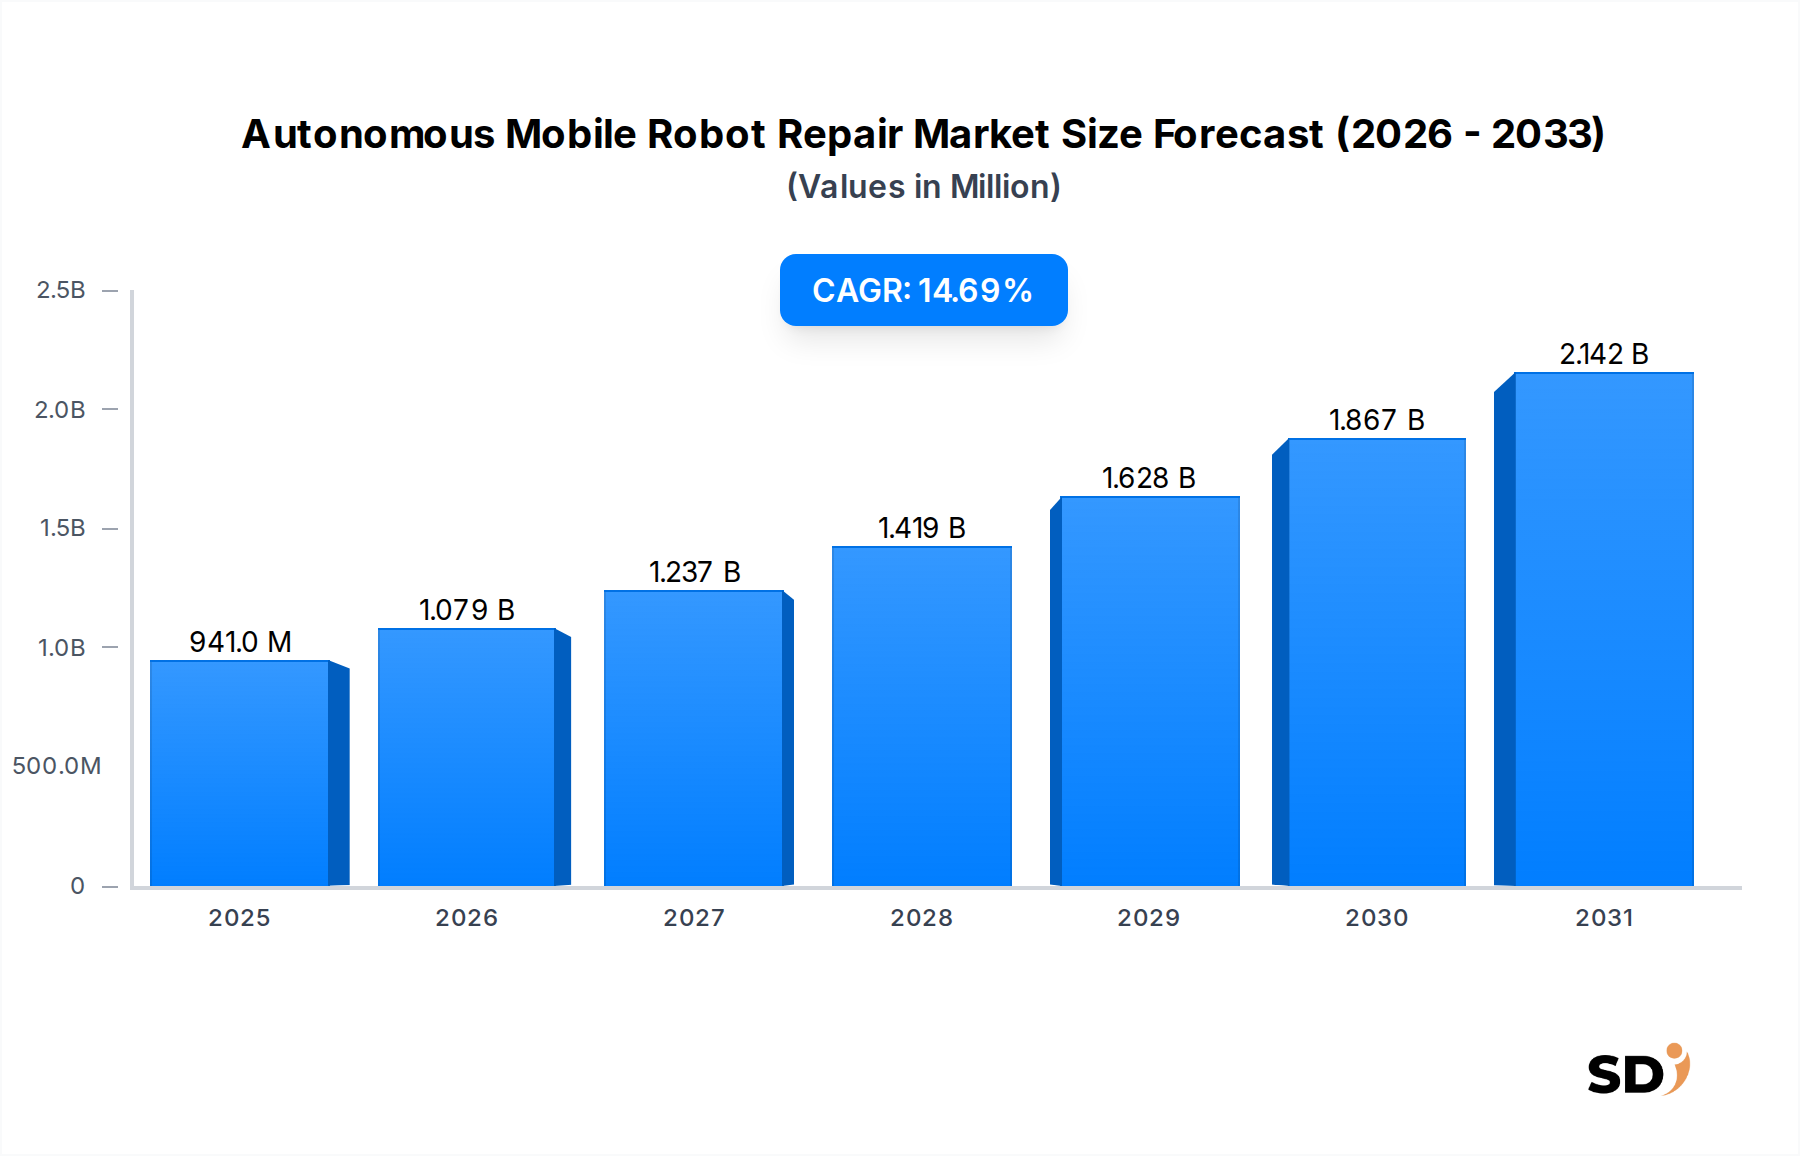
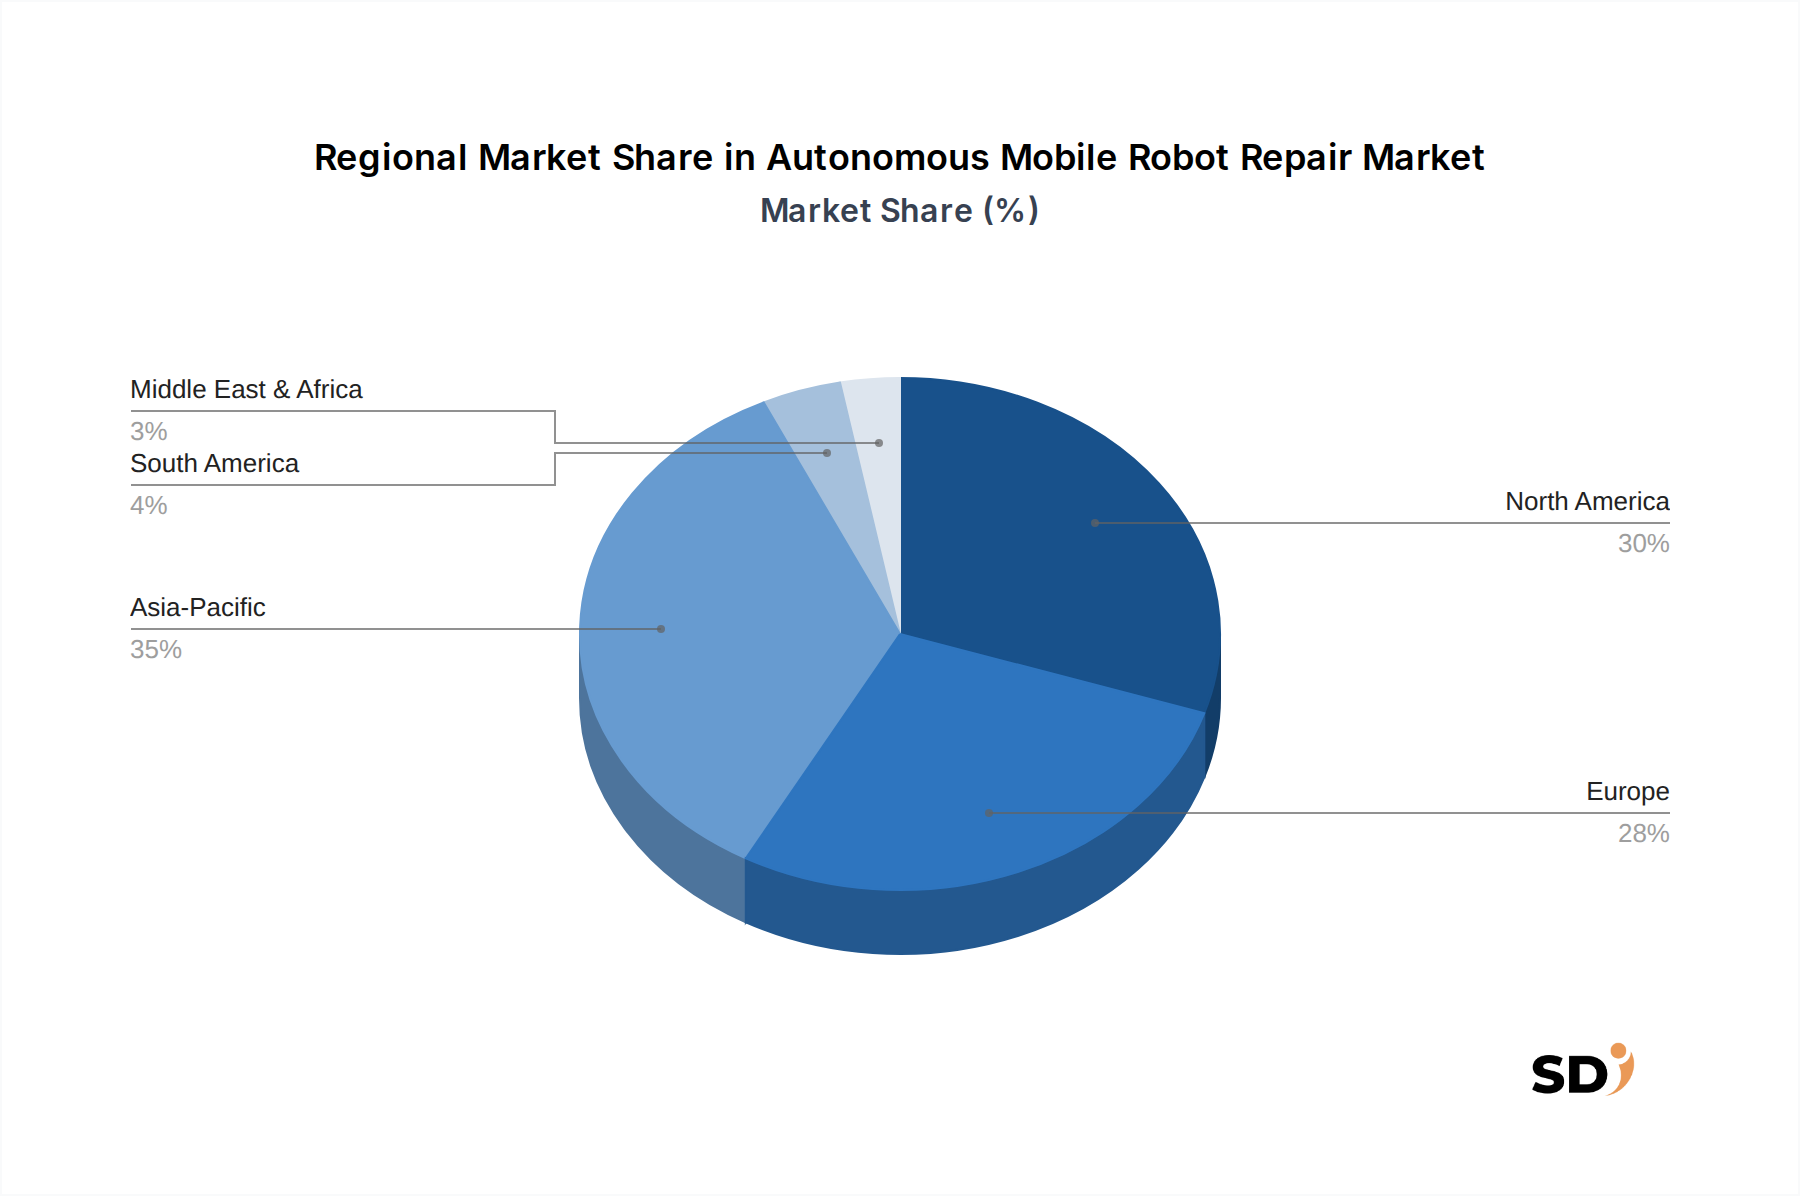
The pricing dynamics in the Autonomous Mobile Robot Repair Market are multifaceted, shaped by the service type, robot complexity, service provider model, and regional economic factors. Average selling prices for repair services are influenced by the blend of traditional time-and-materials charges, fixed-price contracts, and increasingly, subscription-based service level agreements (SLAs) that offer proactive maintenance and guaranteed uptime.
Traditional time-and-materials (T&M) pricing remains prevalent for ad-hoc, corrective repairs, with costs primarily driven by technician labor rates (which can vary significantly based on expertise in Robot Operating System Market diagnostics or mechanical repair), travel expenses, and the cost of replacement parts. For specialized components, such as those from the Sensor Technology Market or proprietary navigation modules, original equipment manufacturers (OEMs) often command higher prices due to intellectual property and limited supply alternatives. This can create margin pressure for independent service providers who might struggle to source parts competitively.
Fixed-price contracts and SLAs are gaining traction, especially for larger enterprises or those with extensive AMR fleets. These models offer predictability for customers and incentivize service providers to perform efficient preventive maintenance to avoid costly emergency repairs. Margins on these contracts are highly dependent on the service provider's ability to accurately forecast failure rates, optimize service routes, and leverage remote diagnostics to minimize on-site visits. The rise of the Predictive Maintenance Services Market is allowing service providers to offer more value-driven, outcome-based pricing models.
Key cost levers for repair service providers include the cost of skilled labor, which is a significant factor given the specialized knowledge required for AMR systems. The availability and training of technicians directly impact service delivery costs. Spare parts inventory management is another critical cost component; balancing the need for immediate availability with inventory holding costs is a constant challenge. Furthermore, the cost of software licenses and updates for diagnostics tools and proprietary robot operating systems can add to the overhead.
Margin pressure in the market is evident from several fronts. Intense competition from a growing number of authorized and independent service providers can drive down prices for basic maintenance tasks. Commoditization of simpler repairs forces providers to differentiate through advanced capabilities like predictive analytics or specialized support for niche AMR types. However, highly specialized repairs for complex, mission-critical robots, or services requiring unique intellectual property, often command higher margins. Warranty periods, typically ranging from one to three years, also impact revenue streams, as OEMs bear repair costs during this period. As AMRs become more ubiquitous, optimizing the service value chain and integrating advanced technologies for efficient fault resolution will be crucial for maintaining healthy profit margins.