Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
Aerospace and Defense Electronic Manufacturing Services by Service Type (Electronic Manufacturing, Engineering Services, Logistics Services, Test Development and Implementation, Others), by Application (Avionics Systems, Radar & Surveillance Systems, Communication Systems, Navigation Systems, Others), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Jul 2, 2026|Base Year : 2025|Pages : 92
Key Insights into the Aerospace and Defense Electronic Manufacturing Services Market
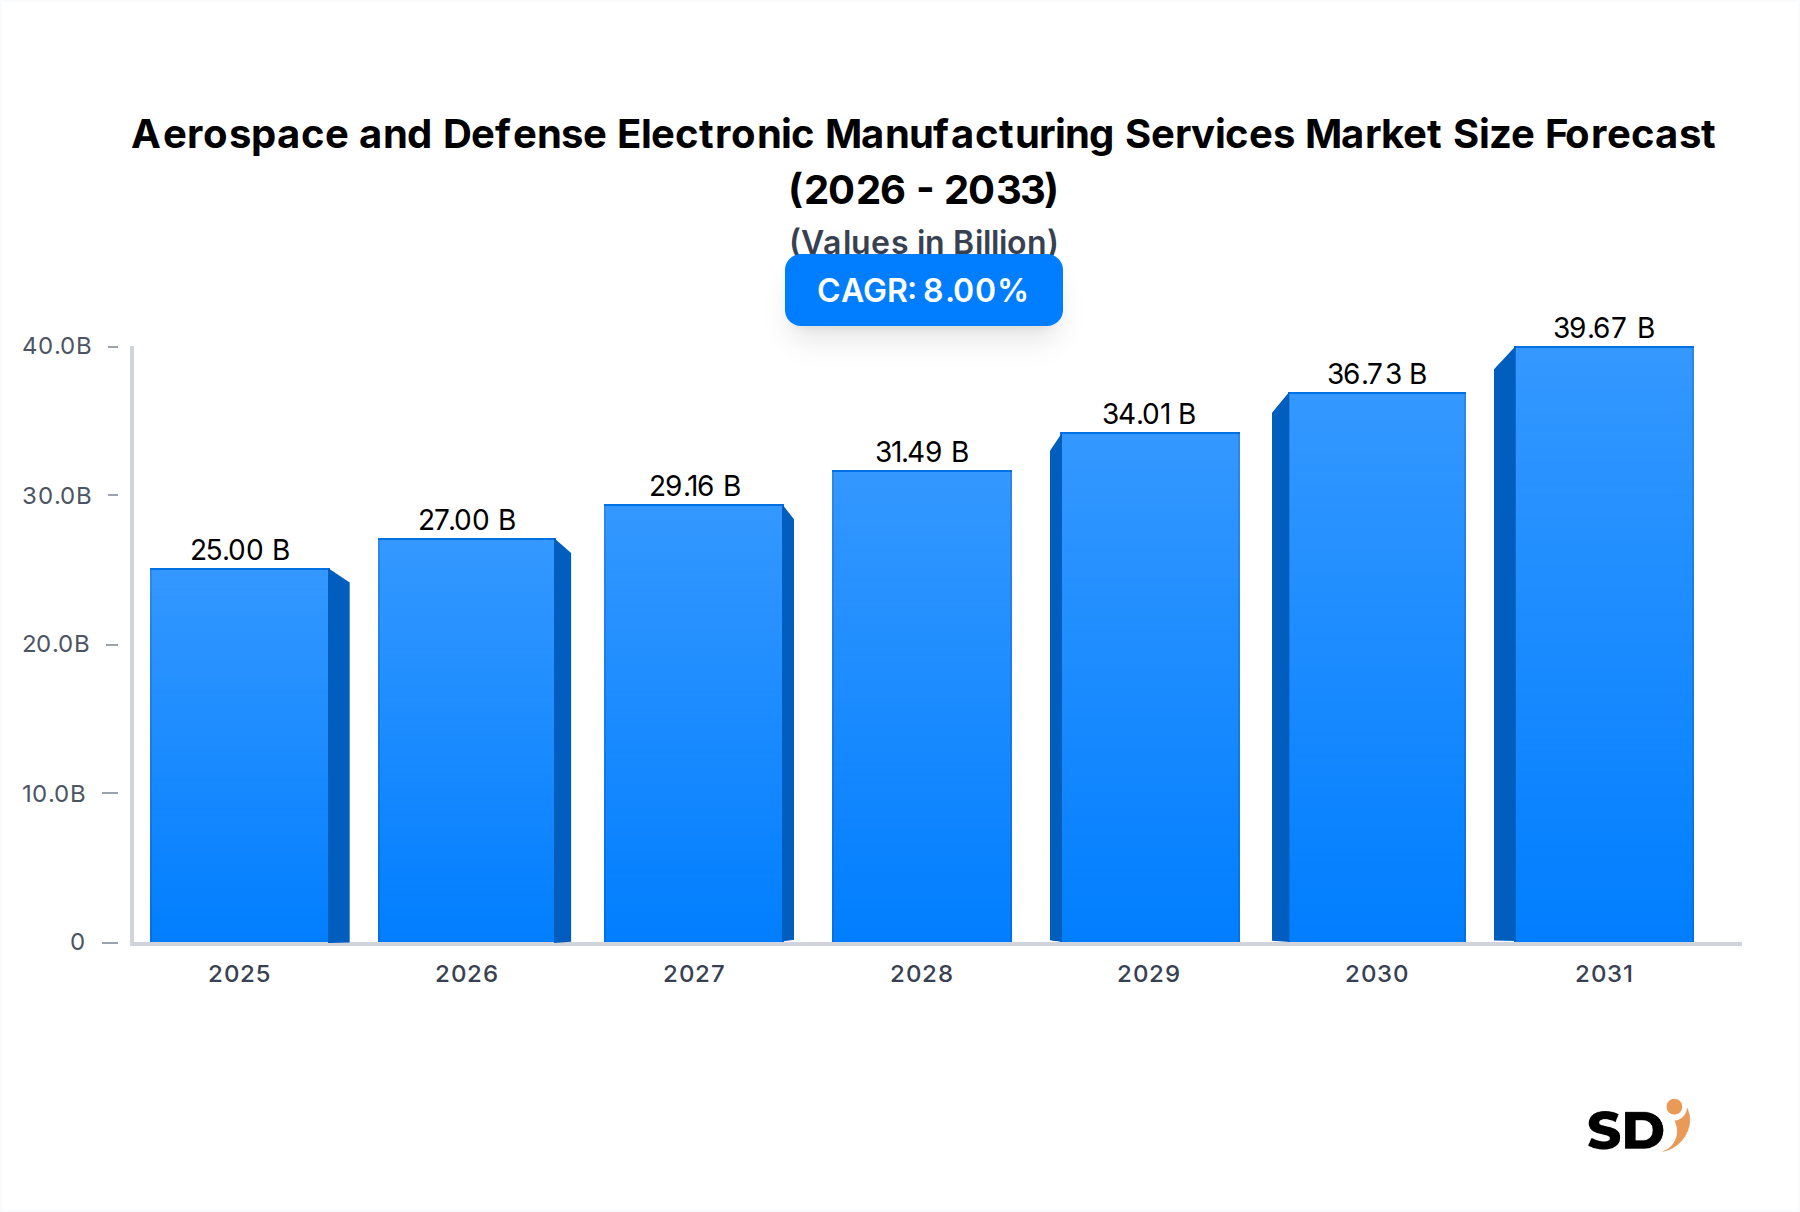
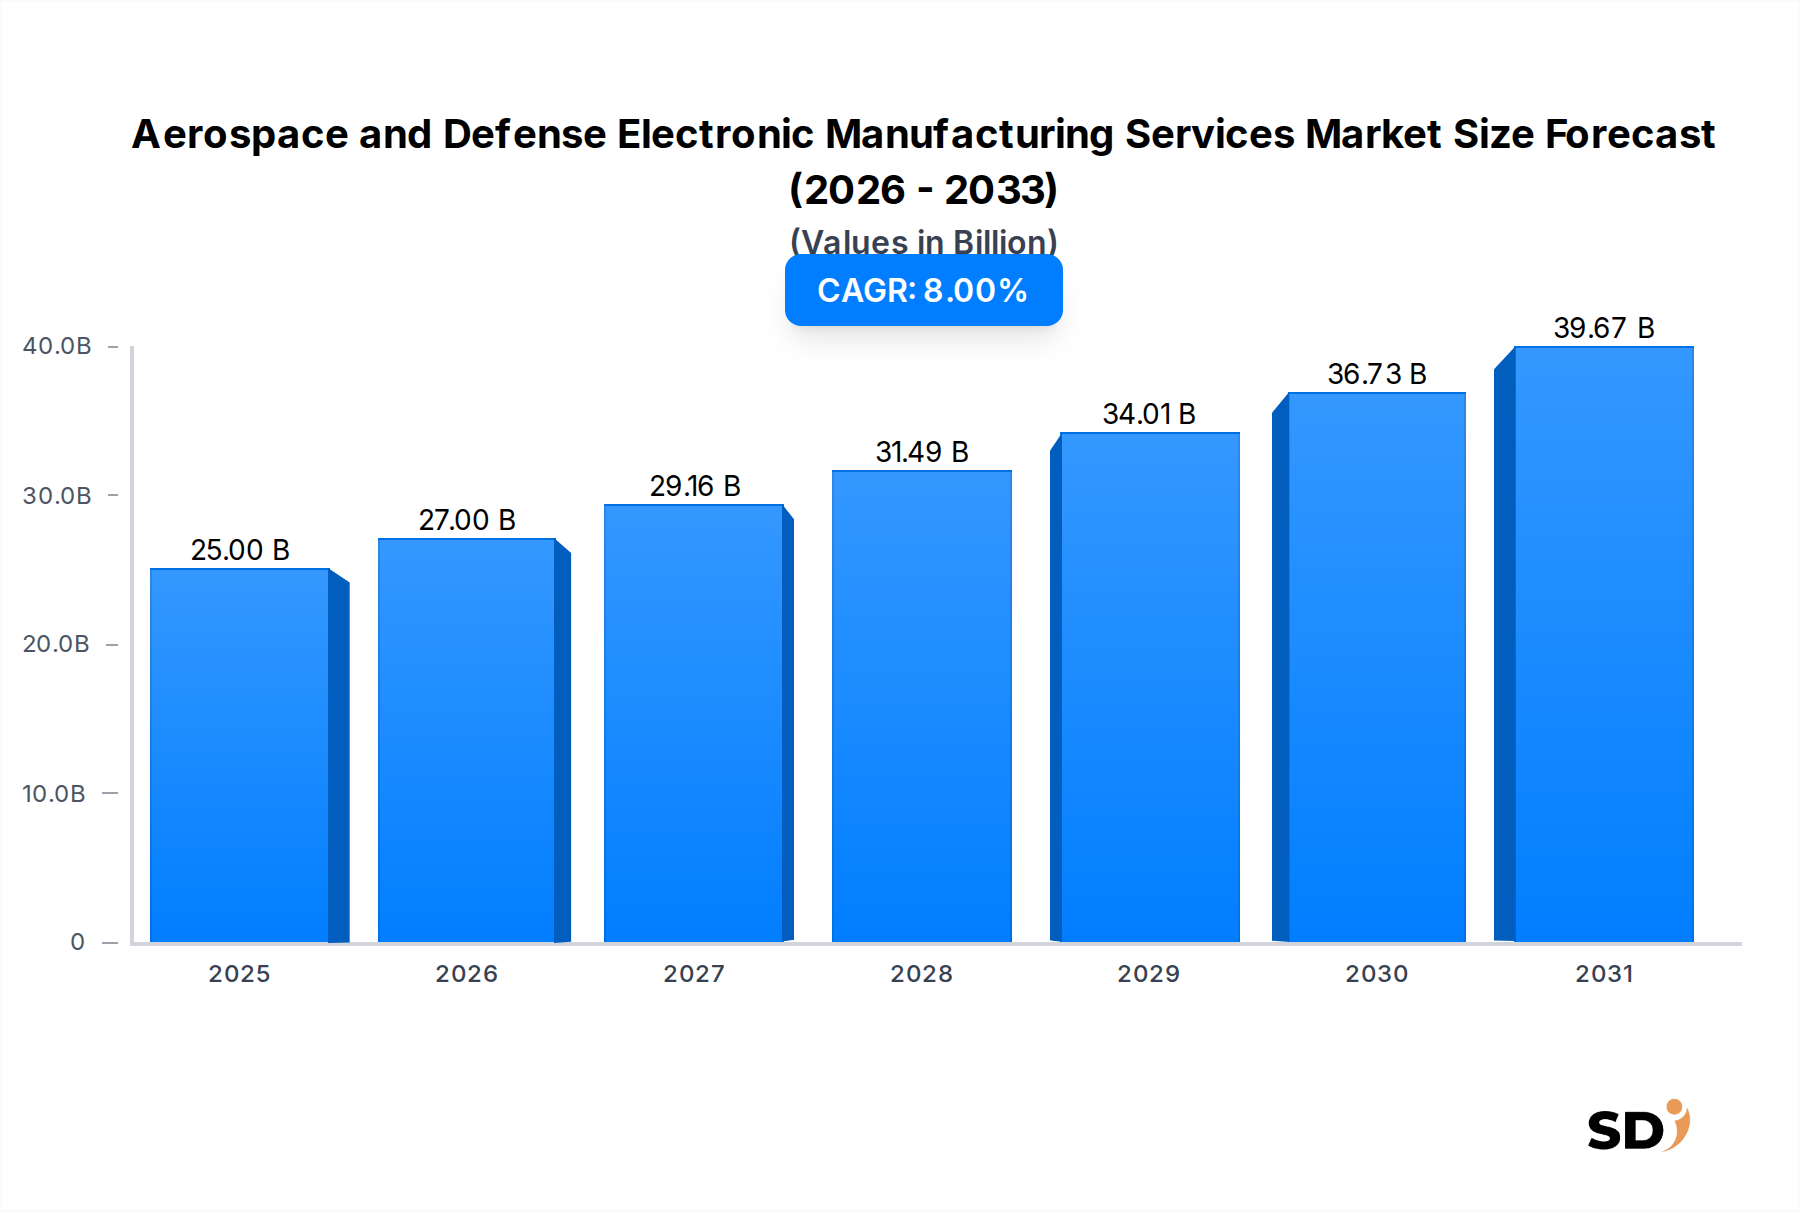
The Global Aerospace and Defense Electronic Manufacturing Services Market, valued at an estimated $81,830 million in 2026, is poised for robust expansion, projecting a climb to $120,894 million by 2034, exhibiting a Compound Annual Growth Rate (CAGR) of 5% over the forecast period. This growth trajectory is fundamentally driven by the escalating demand for advanced electronic systems across both military and commercial aerospace platforms. The Defense Industry Market is experiencing a continuous modernization cycle, fueled by geopolitical tensions and the strategic imperative for technological superiority, which directly translates into increased procurement of sophisticated electronic warfare systems, communication suites, and navigation modules. Furthermore, the commercial aerospace sector's recovery and expansion necessitate high-reliability electronic assemblies for next-generation aircraft, including advanced Avionics Systems Market. Key demand drivers include substantial investments in defense modernization programs globally, particularly the upgrade of aging Military Aircraft Market fleets and the development of new unmanned aerial vehicles (UAVs) and space systems. The integration of cutting-edge technologies such as artificial intelligence, machine learning, and advanced sensor fusion is propelling the need for specialized electronic manufacturing services capable of producing highly complex and miniaturized components with stringent quality and reliability standards. Macro tailwinds, such as increased government defense spending and a concerted shift towards outsourcing specialized manufacturing to achieve cost efficiencies and access niche expertise, further bolster market expansion. The ongoing miniaturization trend in electronic systems, coupled with the imperative for enhanced performance in extreme operational environments, creates a sustained demand for technologically advanced and highly reliable manufacturing processes. The market's forward-looking outlook suggests continued innovation in areas like secure communication, precision guidance, and enhanced surveillance capabilities, driving a sustained need for specialized electronic manufacturing services.
Aerospace and Defense Electronic Manufacturing Services Market Size (In Billion)
150.0B
100.0B
50.0B
0
81.83 B
2025
85.92 B
2026
90.22 B
2027
94.73 B
2028
99.47 B
2029
104.4 B
2030
109.7 B
2031
Electronic Manufacturing Services Segment in Aerospace and Defense Electronic Manufacturing Services Market
Within the broader Aerospace and Defense Electronic Manufacturing Services Market, the "Electronic Manufacturing" service type segment stands as the unequivocal dominant category by revenue share, largely dictating the market's dynamics. This segment encompasses a comprehensive suite of activities, ranging from printed circuit board (PCB) assembly and box-build assembly to complex system integration and testing for various aerospace and defense applications. Its dominance is attributed to the inherent capital intensiveness and specialized expertise required for producing high-reliability, mission-critical electronic components and systems that must adhere to stringent industry standards such as AS9100 and NADCAP. The sheer volume and complexity of electronic components embedded in modern aerospace and defense platforms, including advanced Radar Systems Market and sophisticated Communication Systems Market, necessitate robust electronic manufacturing capabilities. Key players in this segment, such as Jabil Circuit and Ducommun, leverage their extensive manufacturing footprints, technological prowess, and supply chain management capabilities to meet the demanding requirements of aerospace and defense original equipment manufacturers (OEMs). These requirements often include specialized processes like conformal coating, potting, and encapsulation for environmental protection, as well as rigorous testing protocols (e.g., burn-in, vibration, thermal cycling) to ensure operational integrity in extreme conditions. The dominance of the electronic manufacturing segment is further solidified by the trend towards outsourcing, wherein OEMs increasingly rely on specialized EMS providers to manage the complexities of electronic production, allowing them to focus on core competencies like design and final system integration. This strategic outsourcing approach helps mitigate manufacturing risks, reduce operational costs, and accelerate time-to-market for new platforms. The segment's share is expected to grow further, driven by the continuous advancement in electronic warfare systems, navigation technologies, and satellite communication equipment, all of which require highly specialized and precise electronic manufacturing. Furthermore, the increasing adoption of multi-chip modules (MCMs) and system-in-package (SiP) technologies for miniaturization and performance enhancement also contributes to the sophistication and value generated by the electronic manufacturing services segment. The requirement for secure manufacturing processes and traceable supply chains in the defense sector further entrenches the value of established electronic manufacturing service providers, making it a highly consolidating segment with barriers to entry for new players.
Technological Advancements & Digitalization as Key Market Drivers in Aerospace and Defense Electronic Manufacturing Services Market
One of the paramount drivers propelling the Aerospace and Defense Electronic Manufacturing Services Market is the relentless pace of technological advancements and the widespread adoption of digitalization across the industry. The integration of complex Electronic Components Market for enhanced performance is a critical factor. For instance, the transition from analog to digital systems in avionics and defense platforms necessitates highly sophisticated manufacturing capabilities. The defense sector's emphasis on network-centric warfare, which requires seamless data exchange and robust communication systems, drives demand for advanced RF and microwave electronic assemblies. According to industry reports, defense spending on C4ISR (Command, Control, Communications, Computers, Intelligence, Surveillance, and Reconnaissance) systems, which are heavily reliant on advanced electronics, has seen consistent year-over-year increases, indicating a strong underlying demand. For instance, global defense spending is projected to exceed $2.5 trillion by 2028, with a significant portion allocated to electronic warfare and intelligence gathering systems, creating a direct demand for specialized electronic manufacturing services. Similarly, the increasing sophistication of Avionics Systems Market in both commercial and military aircraft, featuring integrated modular avionics (IMA) and fly-by-wire controls, demands extremely high-reliability electronic sub-assemblies. The push for miniaturization and higher power efficiency in electronic systems for space applications and unmanned systems also represents a significant driver. Furthermore, the emergence of technologies like the Internet of Things (IoT) and artificial intelligence (AI) in aerospace applications requires EMS providers to adapt their processes for high-density interconnect (HDI) PCBs and advanced packaging solutions. For example, the market for AI in defense applications is expected to grow at a CAGR exceeding 20% through 2030, directly influencing the types of electronic assemblies required. The pervasive need for secure and resilient electronic systems to counter cyber threats also drives significant investment in specialized manufacturing processes and materials, contributing to the market's expansion.
Competitive Ecosystem of Aerospace and Defense Electronic Manufacturing Services Market
The Aerospace and Defense Electronic Manufacturing Services Market is characterized by a mix of established global players and specialized regional firms, all vying for contracts requiring high precision, reliability, and adherence to stringent industry standards.
Absolute EMS: A specialized provider known for its high-mix, low-to-mid volume manufacturing solutions, focusing on complex PCB assemblies and box-builds for critical applications across various industries, including aerospace and defense.
NEO Tech Inc: Offers a broad range of engineering and manufacturing services for high-reliability markets, specializing in design for manufacturability (DFM), advanced test solutions, and complete product lifecycle management for defense and aerospace clients.
Sonic Manufacturing Technologies: A prominent electronics contract manufacturer recognized for rapid prototyping and quick-turn production of complex PCB assemblies, catering to the demanding timelines and quality requirements of the aerospace and defense sectors.
Jabil Circuit: A global manufacturing solutions provider offering comprehensive services from design to production and repair, with significant capabilities in complex electronics manufacturing and supply chain management for the defense and aerospace industries.
Asteelflash: A leading global EMS company known for its diversified manufacturing footprint and ability to provide end-to-end solutions, including design, engineering, and high-volume production for mission-critical electronic systems.
Ducommun: Specializes in providing engineering and manufacturing services for high-performance products and sub-systems across various markets, including aerospace, defense, and industrial, with expertise in electronics, structures, and interconnect solutions.
Neways Electronics: Focuses on the development, production, and repair of electronic components and systems for professional markets, offering integrated solutions across the entire product lifecycle with a strong emphasis on innovation and quality.
eolane: An international industrial group providing comprehensive electronic and industrial solutions, from R&D and design to manufacturing, maintenance, and end-of-life services, supporting various sectors including aerospace and defense with tailored offerings.
Recent Developments & Milestones in Aerospace and Defense Electronic Manufacturing Services Market
June 2023: Several EMS providers announced significant investments in Additive Manufacturing Market capabilities, particularly for prototyping and low-volume production of specialized electronic components and enclosures, aiming to reduce lead times and enhance design flexibility for aerospace clients.
April 2023: Major defense contractors awarded multi-year contracts to leading EMS firms for the production of next-generation Radar Systems Market and electronic warfare modules, highlighting a trend towards long-term strategic partnerships to secure manufacturing capacities.
February 2023: A key industry report noted an increasing trend among aerospace and defense OEMs to outsource entire sub-system assembly to EMS providers, driven by the need to optimize internal resources and leverage specialized external expertise in complex electronic integration.
November 2022: Regulatory bodies in North America and Europe introduced updated cybersecurity guidelines for the defense supply chain, compelling EMS providers to invest in robust cybersecurity infrastructure and secure manufacturing protocols to protect sensitive intellectual property.
September 2022: Several EMS companies expanded their regional footprints, particularly in Asia Pacific, to capitalize on growing defense budgets and offset requirements in emerging markets, establishing new facilities for Electronic Components Market assembly.
July 2022: Technological advancements in Semiconductor Market packaging, such as 3D integration and wafer-level packaging, were increasingly adopted by specialized EMS firms to enable higher density and miniaturization of electronic systems for space and airborne applications.
Regional Market Breakdown for Aerospace and Defense Electronic Manufacturing Services Market
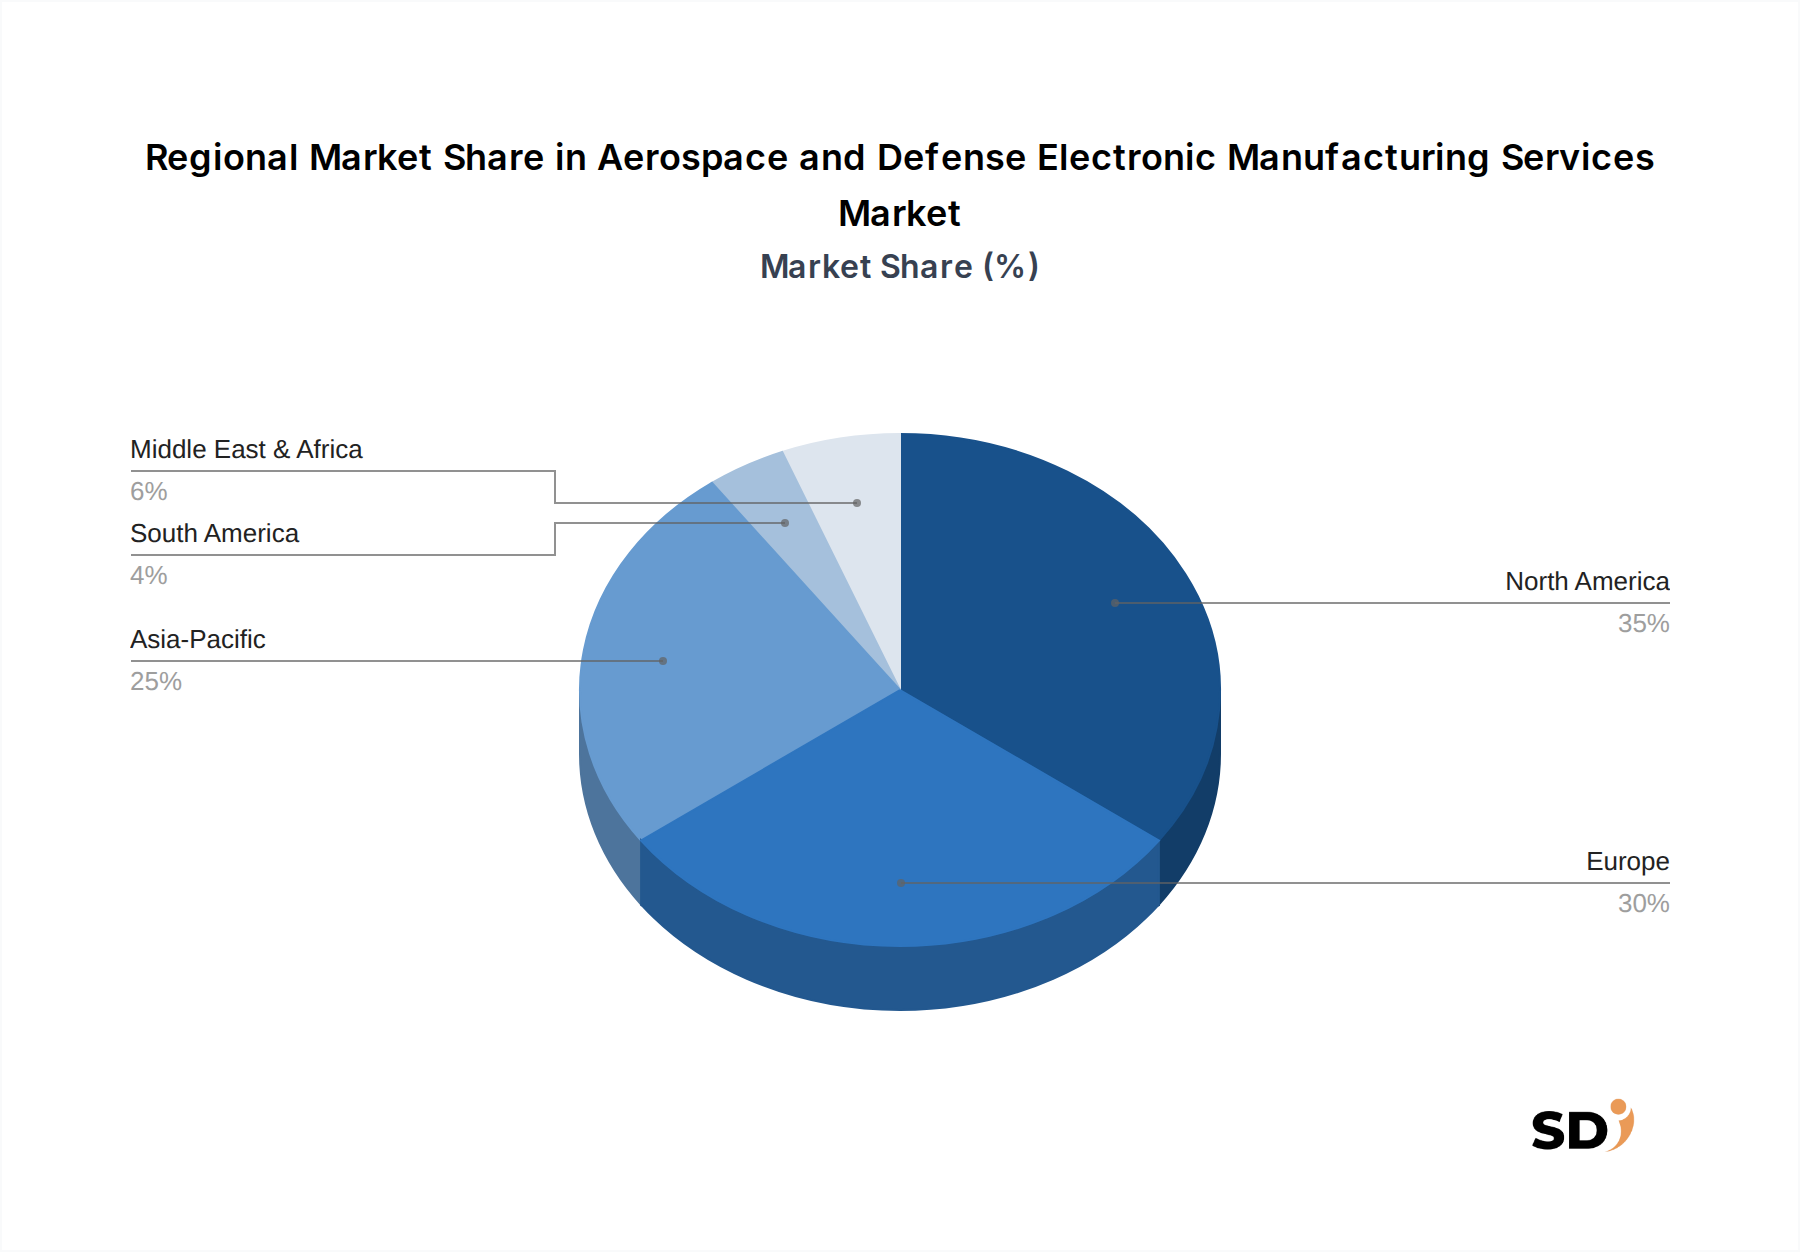
The global Aerospace and Defense Electronic Manufacturing Services Market exhibits distinct regional dynamics driven by varying defense expenditures, technological landscapes, and manufacturing capabilities. North America currently holds the largest revenue share, primarily driven by substantial defense budgets in the United States and Canada, coupled with a robust presence of major aerospace and defense OEMs. The region is characterized by high demand for advanced Avionics Systems Market, electronic warfare, and secure communication platforms. Its CAGR is estimated to be around 4.8%, reflecting a mature but continuously innovating market. Europe follows with a significant market share, supported by defense modernization programs among key nations like the UK, Germany, and France. The region's emphasis on collaborative defense initiatives and technological sovereignty fuels demand for high-reliability electronic manufacturing. Europe's CAGR is projected at approximately 4.5%, reflecting steady investment in upgrading existing capabilities and developing new platforms.
The Asia Pacific region is anticipated to be the fastest-growing market, with an estimated CAGR of 6.2%. This accelerated growth is primarily attributed to increasing defense spending by countries such as China, India, and South Korea, which are rapidly expanding and modernizing their military capabilities. The demand for domestically manufactured Military Aircraft Market and advanced defense electronics is a key driver, often accompanied by technology transfer and offset requirements that benefit local EMS providers. Furthermore, the region is emerging as a significant hub for commercial aerospace manufacturing, further contributing to the growth of electronic manufacturing services. The Middle East & Africa region also presents notable growth opportunities, with a projected CAGR of 5.5%. This growth is fueled by geopolitical instability and a strong desire for national security, leading to significant investments in defense technologies, including surveillance, radar, and communication systems. Countries in the GCC region, Israel, and Turkey are key demand centers, often seeking sophisticated electronic manufacturing services to support their expanding defense industries.
Supply Chain & Raw Material Dynamics for Aerospace and Defense Electronic Manufacturing Services Market
The supply chain for the Aerospace and Defense Electronic Manufacturing Services Market is inherently complex, characterized by stringent quality requirements, long qualification cycles, and a dependence on a highly specialized global network of suppliers. Upstream dependencies include critical Electronic Components Market, such as integrated circuits, microcontrollers, memory chips, and passive components, often sourced from a limited number of specialized manufacturers. The Semiconductor Market forms the bedrock of modern electronics, and any disruptions in its supply directly impact EMS providers. Sourcing risks are pronounced due to geopolitical factors, trade policies, and the concentration of advanced manufacturing capabilities in specific regions. For instance, the global Semiconductor Market shortages witnessed in recent years severely impacted production timelines across various industries, including aerospace and defense, leading to extended lead times and increased costs for critical components like FPGAs and specialized processors. Price volatility of key inputs, particularly rare earth elements used in high-performance magnets for sensors and motors, and specialized alloys for connectors and enclosures, can significantly affect manufacturing costs. For example, rare earth prices have shown fluctuations, with some elements experiencing spikes of up to 50% in specific periods due to supply chain constraints or export restrictions. Lead times for crucial components can extend from weeks to months, making robust inventory management and strategic sourcing paramount. Historically, supply chain disruptions, whether from natural disasters, geopolitical events, or pandemics, have led to production delays, cost overruns, and the need for expensive redesigns or requalifications of alternative components. The market relies heavily on a just-in-time approach for many commercial applications, but the defense sector often prioritizes security of supply and long-term availability, sometimes necessitating costly dual-sourcing strategies or stockpiling of critical parts.
Sustainability & ESG Pressures on Aerospace and Defense Electronic Manufacturing Services Market
The Aerospace and Defense Electronic Manufacturing Services Market is increasingly confronting significant sustainability and ESG (Environmental, Social, and Governance) pressures, reshaping product development and procurement strategies. Environmental regulations, though often with specific exemptions for defense applications, are pushing for the reduction of hazardous materials in electronic assemblies. While direct RoHS and REACH compliance may not always apply, the industry is witnessing a voluntary shift towards lead-free soldering and reduced use of certain restricted substances, driven by broader corporate sustainability goals and customer demands. Carbon targets and decarbonization initiatives are prompting EMS providers to optimize their manufacturing processes for energy efficiency and to transition towards renewable energy sources for their operations. For instance, companies are investing in more efficient cleanroom technologies and reducing waste generation in their PCB fabrication and assembly lines. The circular economy mandate is influencing product design, encouraging modularity and reparability to extend product lifecycles and facilitate recycling of valuable materials at end-of-life. This involves designing for disassembly and utilizing recycled content where feasible, particularly for non-mission-critical enclosures and components. ESG investor criteria are playing an increasingly prominent role, with institutional investors scrutinizing companies' environmental footprint, labor practices, and ethical sourcing policies. This pressure from the financial community is driving greater transparency in supply chains and encouraging robust corporate social responsibility programs. For EMS providers, this translates into a heightened focus on ethical sourcing of raw materials, ensuring fair labor practices throughout their operations and supply chain, and implementing rigorous environmental management systems (EMS) to minimize ecological impact. Compliance with anti-corruption standards and fostering a diverse and inclusive workforce are also critical aspects of managing ESG risks and enhancing long-term value in the Aerospace and Defense Electronic Manufacturing Services Market.
Aerospace and Defense Electronic Manufacturing Services Segmentation
1. Service Type
1.1. Electronic Manufacturing
1.2. Engineering Services
1.3. Logistics Services
1.4. Test Development and Implementation
1.5. Others
2. Application
2.1. Avionics Systems
2.2. Radar & Surveillance Systems
2.3. Communication Systems
2.4. Navigation Systems
2.5. Others
Aerospace and Defense Electronic Manufacturing Services Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Aerospace and Defense Electronic Manufacturing Services REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 5% from 2020-2034
Segmentation
By Service Type
Electronic Manufacturing
Engineering Services
Logistics Services
Test Development and Implementation
Others
By Application
Avionics Systems
Radar & Surveillance Systems
Communication Systems
Navigation Systems
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Service Type
5.1.1. Electronic Manufacturing
5.1.2. Engineering Services
5.1.3. Logistics Services
5.1.4. Test Development and Implementation
5.1.5. Others
5.2. Market Analysis, Insights and Forecast - by Application
5.2.1. Avionics Systems
5.2.2. Radar & Surveillance Systems
5.2.3. Communication Systems
5.2.4. Navigation Systems
5.2.5. Others
5.3. Market Analysis, Insights and Forecast - by Region
5.3.1. North America
5.3.2. South America
5.3.3. Europe
5.3.4. Middle East & Africa
5.3.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Service Type
6.1.1. Electronic Manufacturing
6.1.2. Engineering Services
6.1.3. Logistics Services
6.1.4. Test Development and Implementation
6.1.5. Others
6.2. Market Analysis, Insights and Forecast - by Application
6.2.1. Avionics Systems
6.2.2. Radar & Surveillance Systems
6.2.3. Communication Systems
6.2.4. Navigation Systems
6.2.5. Others
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Service Type
7.1.1. Electronic Manufacturing
7.1.2. Engineering Services
7.1.3. Logistics Services
7.1.4. Test Development and Implementation
7.1.5. Others
7.2. Market Analysis, Insights and Forecast - by Application
7.2.1. Avionics Systems
7.2.2. Radar & Surveillance Systems
7.2.3. Communication Systems
7.2.4. Navigation Systems
7.2.5. Others
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Service Type
8.1.1. Electronic Manufacturing
8.1.2. Engineering Services
8.1.3. Logistics Services
8.1.4. Test Development and Implementation
8.1.5. Others
8.2. Market Analysis, Insights and Forecast - by Application
8.2.1. Avionics Systems
8.2.2. Radar & Surveillance Systems
8.2.3. Communication Systems
8.2.4. Navigation Systems
8.2.5. Others
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Service Type
9.1.1. Electronic Manufacturing
9.1.2. Engineering Services
9.1.3. Logistics Services
9.1.4. Test Development and Implementation
9.1.5. Others
9.2. Market Analysis, Insights and Forecast - by Application
9.2.1. Avionics Systems
9.2.2. Radar & Surveillance Systems
9.2.3. Communication Systems
9.2.4. Navigation Systems
9.2.5. Others
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Service Type
10.1.1. Electronic Manufacturing
10.1.2. Engineering Services
10.1.3. Logistics Services
10.1.4. Test Development and Implementation
10.1.5. Others
10.2. Market Analysis, Insights and Forecast - by Application
10.2.1. Avionics Systems
10.2.2. Radar & Surveillance Systems
10.2.3. Communication Systems
10.2.4. Navigation Systems
10.2.5. Others
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Absolute EMS
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. NEO Tech Inc
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Sonic Manufacturing Technologies
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Jabil Circuit
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Asteelflash
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Ducommun
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Neways Electronics
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. eolane
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Aerospace and Defense Electronic Manufacturing Services Revenue Breakdown (million, %) by Region 2026 & 2034
Figure 2: North America Aerospace and Defense Electronic Manufacturing Services Revenue (million), by Service Type 2026 & 2034
Figure 3: North America Aerospace and Defense Electronic Manufacturing Services Revenue Share (%), by Service Type 2026 & 2034
Figure 4: North America Aerospace and Defense Electronic Manufacturing Services Revenue (million), by Application 2026 & 2034
Figure 5: North America Aerospace and Defense Electronic Manufacturing Services Revenue Share (%), by Application 2026 & 2034
Figure 6: North America Aerospace and Defense Electronic Manufacturing Services Revenue (million), by Country 2026 & 2034
Figure 7: North America Aerospace and Defense Electronic Manufacturing Services Revenue Share (%), by Country 2026 & 2034
Figure 8: South America Aerospace and Defense Electronic Manufacturing Services Revenue (million), by Service Type 2026 & 2034
Figure 9: South America Aerospace and Defense Electronic Manufacturing Services Revenue Share (%), by Service Type 2026 & 2034
Figure 10: South America Aerospace and Defense Electronic Manufacturing Services Revenue (million), by Application 2026 & 2034
Figure 11: South America Aerospace and Defense Electronic Manufacturing Services Revenue Share (%), by Application 2026 & 2034
Figure 12: South America Aerospace and Defense Electronic Manufacturing Services Revenue (million), by Country 2026 & 2034
Figure 13: South America Aerospace and Defense Electronic Manufacturing Services Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Aerospace and Defense Electronic Manufacturing Services Revenue (million), by Service Type 2026 & 2034
Figure 15: Europe Aerospace and Defense Electronic Manufacturing Services Revenue Share (%), by Service Type 2026 & 2034
Figure 16: Europe Aerospace and Defense Electronic Manufacturing Services Revenue (million), by Application 2026 & 2034
Figure 17: Europe Aerospace and Defense Electronic Manufacturing Services Revenue Share (%), by Application 2026 & 2034
Figure 18: Europe Aerospace and Defense Electronic Manufacturing Services Revenue (million), by Country 2026 & 2034
Figure 19: Europe Aerospace and Defense Electronic Manufacturing Services Revenue Share (%), by Country 2026 & 2034
Figure 20: Middle East & Africa Aerospace and Defense Electronic Manufacturing Services Revenue (million), by Service Type 2026 & 2034
Figure 21: Middle East & Africa Aerospace and Defense Electronic Manufacturing Services Revenue Share (%), by Service Type 2026 & 2034
Figure 22: Middle East & Africa Aerospace and Defense Electronic Manufacturing Services Revenue (million), by Application 2026 & 2034
Figure 23: Middle East & Africa Aerospace and Defense Electronic Manufacturing Services Revenue Share (%), by Application 2026 & 2034
Figure 24: Middle East & Africa Aerospace and Defense Electronic Manufacturing Services Revenue (million), by Country 2026 & 2034
Figure 25: Middle East & Africa Aerospace and Defense Electronic Manufacturing Services Revenue Share (%), by Country 2026 & 2034
Figure 26: Asia Pacific Aerospace and Defense Electronic Manufacturing Services Revenue (million), by Service Type 2026 & 2034
Figure 27: Asia Pacific Aerospace and Defense Electronic Manufacturing Services Revenue Share (%), by Service Type 2026 & 2034
Figure 28: Asia Pacific Aerospace and Defense Electronic Manufacturing Services Revenue (million), by Application 2026 & 2034
Figure 29: Asia Pacific Aerospace and Defense Electronic Manufacturing Services Revenue Share (%), by Application 2026 & 2034
Figure 30: Asia Pacific Aerospace and Defense Electronic Manufacturing Services Revenue (million), by Country 2026 & 2034
Figure 31: Asia Pacific Aerospace and Defense Electronic Manufacturing Services Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Aerospace and Defense Electronic Manufacturing Services Revenue million Forecast, by Service Type 2020 & 2034
Table 2: Aerospace and Defense Electronic Manufacturing Services Revenue million Forecast, by Application 2020 & 2034
Table 3: Aerospace and Defense Electronic Manufacturing Services Revenue million Forecast, by Region 2020 & 2034
Table 4: North America Aerospace and Defense Electronic Manufacturing Services Revenue million Forecast, by Service Type 2020 & 2034
Table 5: North America Aerospace and Defense Electronic Manufacturing Services Revenue million Forecast, by Application 2020 & 2034
Table 6: North America Aerospace and Defense Electronic Manufacturing Services Revenue million Forecast, by Country 2020 & 2034
Table 7: United States Aerospace and Defense Electronic Manufacturing Services Revenue (million) Forecast, by Application 2020 & 2034
Table 8: Canada Aerospace and Defense Electronic Manufacturing Services Revenue (million) Forecast, by Application 2020 & 2034
Table 9: Mexico Aerospace and Defense Electronic Manufacturing Services Revenue (million) Forecast, by Application 2020 & 2034
Table 10: South America Aerospace and Defense Electronic Manufacturing Services Revenue million Forecast, by Service Type 2020 & 2034
Table 11: South America Aerospace and Defense Electronic Manufacturing Services Revenue million Forecast, by Application 2020 & 2034
Table 12: South America Aerospace and Defense Electronic Manufacturing Services Revenue million Forecast, by Country 2020 & 2034
Table 13: Brazil Aerospace and Defense Electronic Manufacturing Services Revenue (million) Forecast, by Application 2020 & 2034
Table 14: Argentina Aerospace and Defense Electronic Manufacturing Services Revenue (million) Forecast, by Application 2020 & 2034
Table 15: Rest of South America Aerospace and Defense Electronic Manufacturing Services Revenue (million) Forecast, by Application 2020 & 2034
Table 16: Europe Aerospace and Defense Electronic Manufacturing Services Revenue million Forecast, by Service Type 2020 & 2034
Table 17: Europe Aerospace and Defense Electronic Manufacturing Services Revenue million Forecast, by Application 2020 & 2034
Table 18: Europe Aerospace and Defense Electronic Manufacturing Services Revenue million Forecast, by Country 2020 & 2034
Table 19: United Kingdom Aerospace and Defense Electronic Manufacturing Services Revenue (million) Forecast, by Application 2020 & 2034
Table 20: Germany Aerospace and Defense Electronic Manufacturing Services Revenue (million) Forecast, by Application 2020 & 2034
Table 21: France Aerospace and Defense Electronic Manufacturing Services Revenue (million) Forecast, by Application 2020 & 2034
Table 22: Italy Aerospace and Defense Electronic Manufacturing Services Revenue (million) Forecast, by Application 2020 & 2034
Table 23: Spain Aerospace and Defense Electronic Manufacturing Services Revenue (million) Forecast, by Application 2020 & 2034
Table 24: Russia Aerospace and Defense Electronic Manufacturing Services Revenue (million) Forecast, by Application 2020 & 2034
Table 25: Benelux Aerospace and Defense Electronic Manufacturing Services Revenue (million) Forecast, by Application 2020 & 2034
Table 26: Nordics Aerospace and Defense Electronic Manufacturing Services Revenue (million) Forecast, by Application 2020 & 2034
Table 27: Rest of Europe Aerospace and Defense Electronic Manufacturing Services Revenue (million) Forecast, by Application 2020 & 2034
Table 28: Middle East & Africa Aerospace and Defense Electronic Manufacturing Services Revenue million Forecast, by Service Type 2020 & 2034
Table 29: Middle East & Africa Aerospace and Defense Electronic Manufacturing Services Revenue million Forecast, by Application 2020 & 2034
Table 30: Middle East & Africa Aerospace and Defense Electronic Manufacturing Services Revenue million Forecast, by Country 2020 & 2034
Table 31: Turkey Aerospace and Defense Electronic Manufacturing Services Revenue (million) Forecast, by Application 2020 & 2034
Table 32: Israel Aerospace and Defense Electronic Manufacturing Services Revenue (million) Forecast, by Application 2020 & 2034
Table 33: GCC Aerospace and Defense Electronic Manufacturing Services Revenue (million) Forecast, by Application 2020 & 2034
Table 34: North Africa Aerospace and Defense Electronic Manufacturing Services Revenue (million) Forecast, by Application 2020 & 2034
Table 35: South Africa Aerospace and Defense Electronic Manufacturing Services Revenue (million) Forecast, by Application 2020 & 2034
Table 36: Rest of Middle East & Africa Aerospace and Defense Electronic Manufacturing Services Revenue (million) Forecast, by Application 2020 & 2034
Table 37: Asia Pacific Aerospace and Defense Electronic Manufacturing Services Revenue million Forecast, by Service Type 2020 & 2034
Table 38: Asia Pacific Aerospace and Defense Electronic Manufacturing Services Revenue million Forecast, by Application 2020 & 2034
Table 39: Asia Pacific Aerospace and Defense Electronic Manufacturing Services Revenue million Forecast, by Country 2020 & 2034
Table 40: China Aerospace and Defense Electronic Manufacturing Services Revenue (million) Forecast, by Application 2020 & 2034
Table 41: India Aerospace and Defense Electronic Manufacturing Services Revenue (million) Forecast, by Application 2020 & 2034
Table 42: Japan Aerospace and Defense Electronic Manufacturing Services Revenue (million) Forecast, by Application 2020 & 2034
Table 43: South Korea Aerospace and Defense Electronic Manufacturing Services Revenue (million) Forecast, by Application 2020 & 2034
Table 44: ASEAN Aerospace and Defense Electronic Manufacturing Services Revenue (million) Forecast, by Application 2020 & 2034
Table 45: Oceania Aerospace and Defense Electronic Manufacturing Services Revenue (million) Forecast, by Application 2020 & 2034
Table 46: Rest of Asia Pacific Aerospace and Defense Electronic Manufacturing Services Revenue (million) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
The foundation of our market analysis for "Aerospace and Defense Electronic Manufacturing Services" rests heavily on primary research, constituting 75% of our overall research effort. This robust approach is crucial for gathering direct, qualitative, and highly specific insights into market dynamics, technological advancements, competitive landscapes, and future outlooks that are not readily available through secondary sources. Our primary research strategy involves in-depth, structured interviews conducted through a blend of telephonic discussions, virtual meetings, and on-site visits where feasible.
Our interview panel is meticulously selected to ensure comprehensive coverage across the market's value chain and geographical segments outlined in the report scope. Key participants include a diverse range of industry experts and stakeholders, specifically targeting:
Aerospace & Defense Original Equipment Manufacturer (OEM) Integrators
Sub-system & Component Manufacturers for A&D Applications
Contract Logistics & Maintenance, Repair, and Overhaul (MRO) Service Providers
Defense Prime Contractors and Government Procurement Officials
Job Designations:
VP, Global Supply Chain & Procurement (Aerospace & Defense OEM)
Director, Business Development & Sales (Aerospace & Defense EMS)
Chief Engineer / Head of R&D (Avionics/Radar Systems Manufacturer)
Program Manager, Defense Systems Integration
These interviews provide invaluable first-hand perspectives on market trends, demand drivers, challenges, emerging opportunities, and competitive strategies, enabling us to validate and enrich the quantitative data derived from secondary research.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
VP, Global Supply Chain & Procurement (Aerospace & Defense OEM)
33%
Director, Business Development & Sales (Aerospace & Defense EMS)
33%
Chief Engineer / Head of R&D (Avionics/Radar Systems Manufacturer)
Aerospace & Defense Original Equipment Manufacturer (OEM) Integrators
32%
Sub-system & Component Manufacturers for A&D Applications
18%
Contract Logistics & Maintenance, Repair, and Overhaul (MRO) Service Providers
12%
Secondary Research & Industry Benchmarking
Secondary research accounts for the remaining 25% of our research methodology, serving to establish a strong quantitative baseline, corroborate primary findings, and provide macro-level economic and industry context. This phase involves extensive data mining and analysis from a wide array of credible and authoritative sources. Our firm strictly avoids data from other market research websites to ensure originality and unbiased insights.
Key secondary research sources leveraged for this report include:
Financial Databases: Bloomberg, Factiva, Hoovers, and PitchBook for company financials, market valuations, merger & acquisition activities, and investment trends within the aerospace and defense sectors.
Government Publications & Databases: Official statistics and reports from defense ministries (e.g., U.S. Department of Defense, European Ministry of Defence), national aviation authorities, and government economic agencies (.gov sources).
Industry Associations & Regulatory Bodies: Data, reports, and whitepapers from globally recognized entities such as the Aerospace Industries Association (AIA) [https://www.aia-aerospace.org/], IPC - Association Connecting Electronics Industries [https://www.ipc.org/], and the European Defence Agency (EDA) [https://eda.europa.eu/], among others. These sources provide crucial insights into industry standards, technological roadmaps, and regulatory frameworks.
Company Annual Reports & Investor Presentations: Publicly available documents from key market players offering detailed operational and financial performance data.
Academic Journals & Technical Publications: Peer-reviewed articles and research papers discussing technological advancements in aerospace and defense electronics.
Our commitment ensures that every report is updated up to the date of purchase, reflecting the latest market information and developments from these robust secondary sources.
Demand Modeling & Market Estimation
Our market estimation methodology employs a rigorous combination of top-down and bottom-up approaches, subsequently triangulated for maximum accuracy. This multi-level data triangulation involves comparing and cross-referencing data points from primary interviews, secondary research, and our internal proprietary models to ensure consistency and reliability.
Bottom-Up Approach: This method involves segmenting the total market into its smallest constituent parts, estimating each segment, and then aggregating them to derive the overall market size. For the "Aerospace and Defense Electronic Manufacturing Services" market, this includes:
Specific Metrics/Variables:
Production volumes of key aerospace & defense electronic systems (e.g., number of new aircraft deliveries, satellite launches, radar system deployments).
Average Electronic Manufacturing Services (EMS) value per unit for various system types and complexity levels (e.g., per avionics module, per communication system unit).
Annual defense expenditure and R&D budgets allocated specifically to electronic system upgrades, new procurements, and modernization programs.
Outsourcing rates and trends for electronic manufacturing, engineering services, and logistics within the global aerospace and defense industry.
Top-Down Approach: This approach starts with the total available market and progressively breaks it down into smaller segments using macroeconomic indicators, industry growth rates, and market share analyses. This provides a sanity check and validates the bottom-up estimates.
Market forecasting from 2026-2034 is conducted using advanced statistical techniques, including regression analysis, time series analysis, and scenario-based modeling, accounting for economic factors, geopolitical influences, technological shifts, and regulatory changes.
Data Accuracy & Quality Check
Our firm guarantees an estimated data accuracy level of 85-90% for all market size and forecast figures presented in this report. This high level of accuracy is achieved through a multi-faceted quality assurance process:
Data Triangulation: As detailed above, insights from primary and secondary research are rigorously cross-referenced and validated against each other to identify and reconcile discrepancies.
Expert Validation: Findings and projections are reviewed by a panel of internal subject matter experts and, where appropriate, by external industry consultants to ensure logical consistency and real-world applicability.
Peer Review: All data models, assumptions, and conclusions undergo a thorough peer review process by senior analysts within our organization.
Robust Data Cleaning & Processing: Raw data is meticulously cleaned, processed, and analyzed using statistical software to minimize errors and biases. Every report is systematically updated to reflect the latest market conditions and intelligence up to the date of purchase, ensuring our clients receive the most current and actionable insights available.
Frequently Asked Questions
1. What is the projected market size and growth rate for Aerospace and Defense EMS?
The global Aerospace and Defense Electronic Manufacturing Services market was valued at $81,830 million. It is projected to grow at a Compound Annual Growth Rate (CAGR) of 5% through 2033, driven by continuous demand for advanced electronics.
2. Which companies are key players in the Aerospace and Defense Electronic Manufacturing Services market?
Leading companies in this market include Jabil Circuit, Absolute EMS, NEO Tech Inc, and Ducommun. These firms compete on technological capabilities, specialized service offerings, and global operational footprints to secure market share.
3. Why is the Aerospace and Defense Electronic Manufacturing Services market experiencing growth?
Growth is primarily driven by global defense modernization initiatives and the increasing integration of advanced electronic systems in aerospace platforms. Demand catalysts include higher adoption of sophisticated avionics, radar, and communication technologies.
4. How are new technologies impacting the Aerospace and Defense EMS sector?
Though specific disruptive technologies are not detailed, the Aerospace and Defense Electronic Manufacturing Services sector is influenced by evolving requirements for advanced electronics. This includes miniaturization, enhanced reliability, and integration of complex digital systems across various applications.
5. What end-user applications drive demand for Aerospace and Defense EMS?
Demand for Aerospace and Defense EMS is driven by critical end-user applications such as Avionics Systems, Radar & Surveillance Systems, Communication Systems, and Navigation Systems. These applications require specialized Electronic Manufacturing and Engineering Services for optimal performance.
6. What challenges are prevalent in the Aerospace and Defense EMS market?
While specific restraints are not detailed, the Aerospace and Defense Electronic Manufacturing Services market typically navigates challenges related to strict quality standards, security protocols, and lengthy product development cycles. These factors necessitate specialized expertise in Electronic Manufacturing and Engineering Services.