Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
HVAC Adhesives & Sealants Market: $77.08B by 2025, 6% CAGR
HVAC Adhesives and Sealants
HVAC Adhesives & Sealants Market: $77.08B by 2025, 6% CAGR
HVAC Adhesives and Sealants by Application (Condenser, Water Heating and Boiler Units, Others), by Types (Hybrid Adhesive, Neutral Cure Silicone Sealant), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Jul 25, 2026|Base Year : 2025|Pages : 85
Key Insights & Executive Summary: HVAC Adhesives and Sealants Market
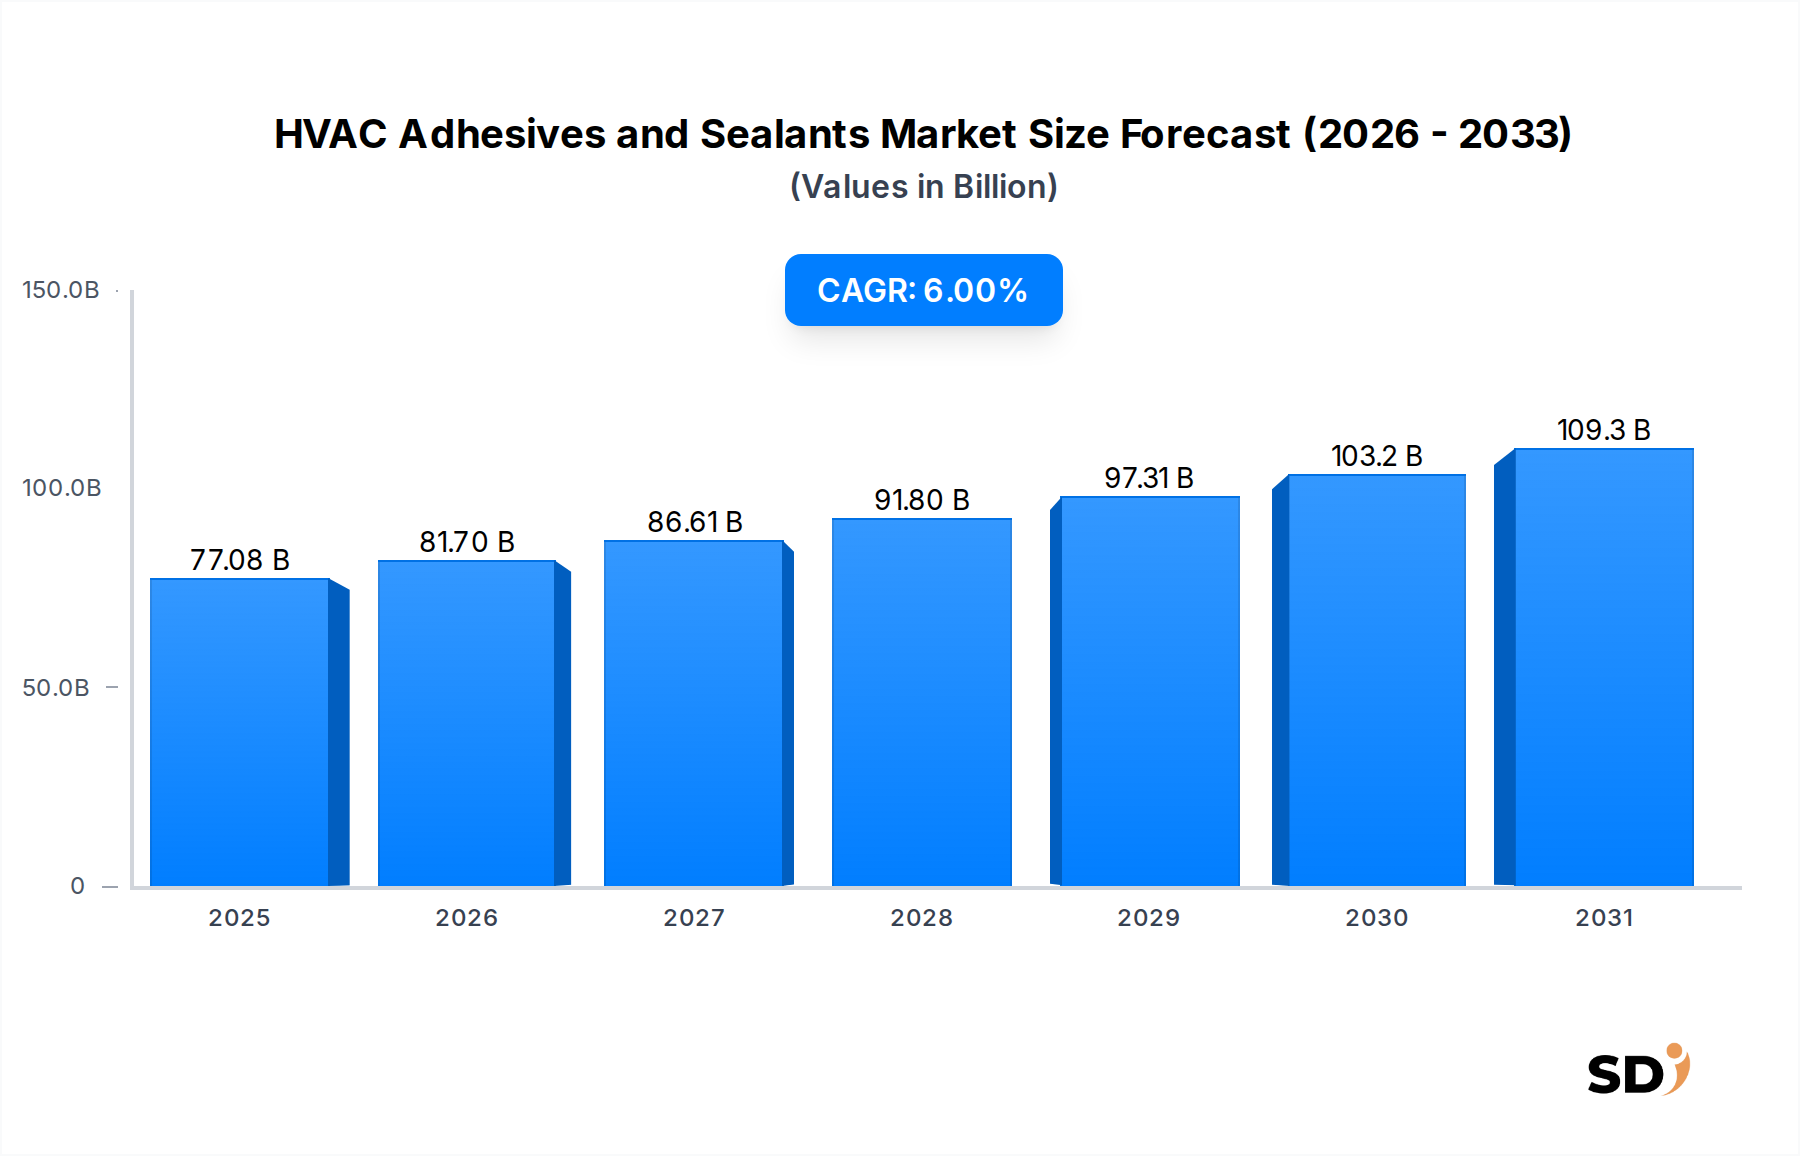
HVAC Adhesives and Sealants Market Size (In Billion)
150.0B
100.0B
50.0B
0
77.08 B
2025
81.70 B
2026
86.61 B
2027
91.80 B
2028
97.31 B
2029
103.2 B
2030
109.3 B
2031
Market at a Glance
The global HVAC Adhesives and Sealants Market is poised for robust expansion, projected to reach approximately $137.99 billion by 2035, growing from $77.08 billion in 2025 at a compound annual growth rate (CAGR) of 6%. This significant growth is underpinned by escalating demand for energy-efficient building solutions, rapid urbanization in emerging economies, and increasingly stringent environmental regulations governing indoor air quality (IAQ) and emissions. Adhesives and sealants are critical components in HVAC systems, ensuring optimal thermal performance, structural integrity, noise reduction, and protection against moisture and contaminants. The market's momentum is directly tied to the robust expansion of the Construction Adhesives Market, particularly within commercial and residential infrastructure projects globally.
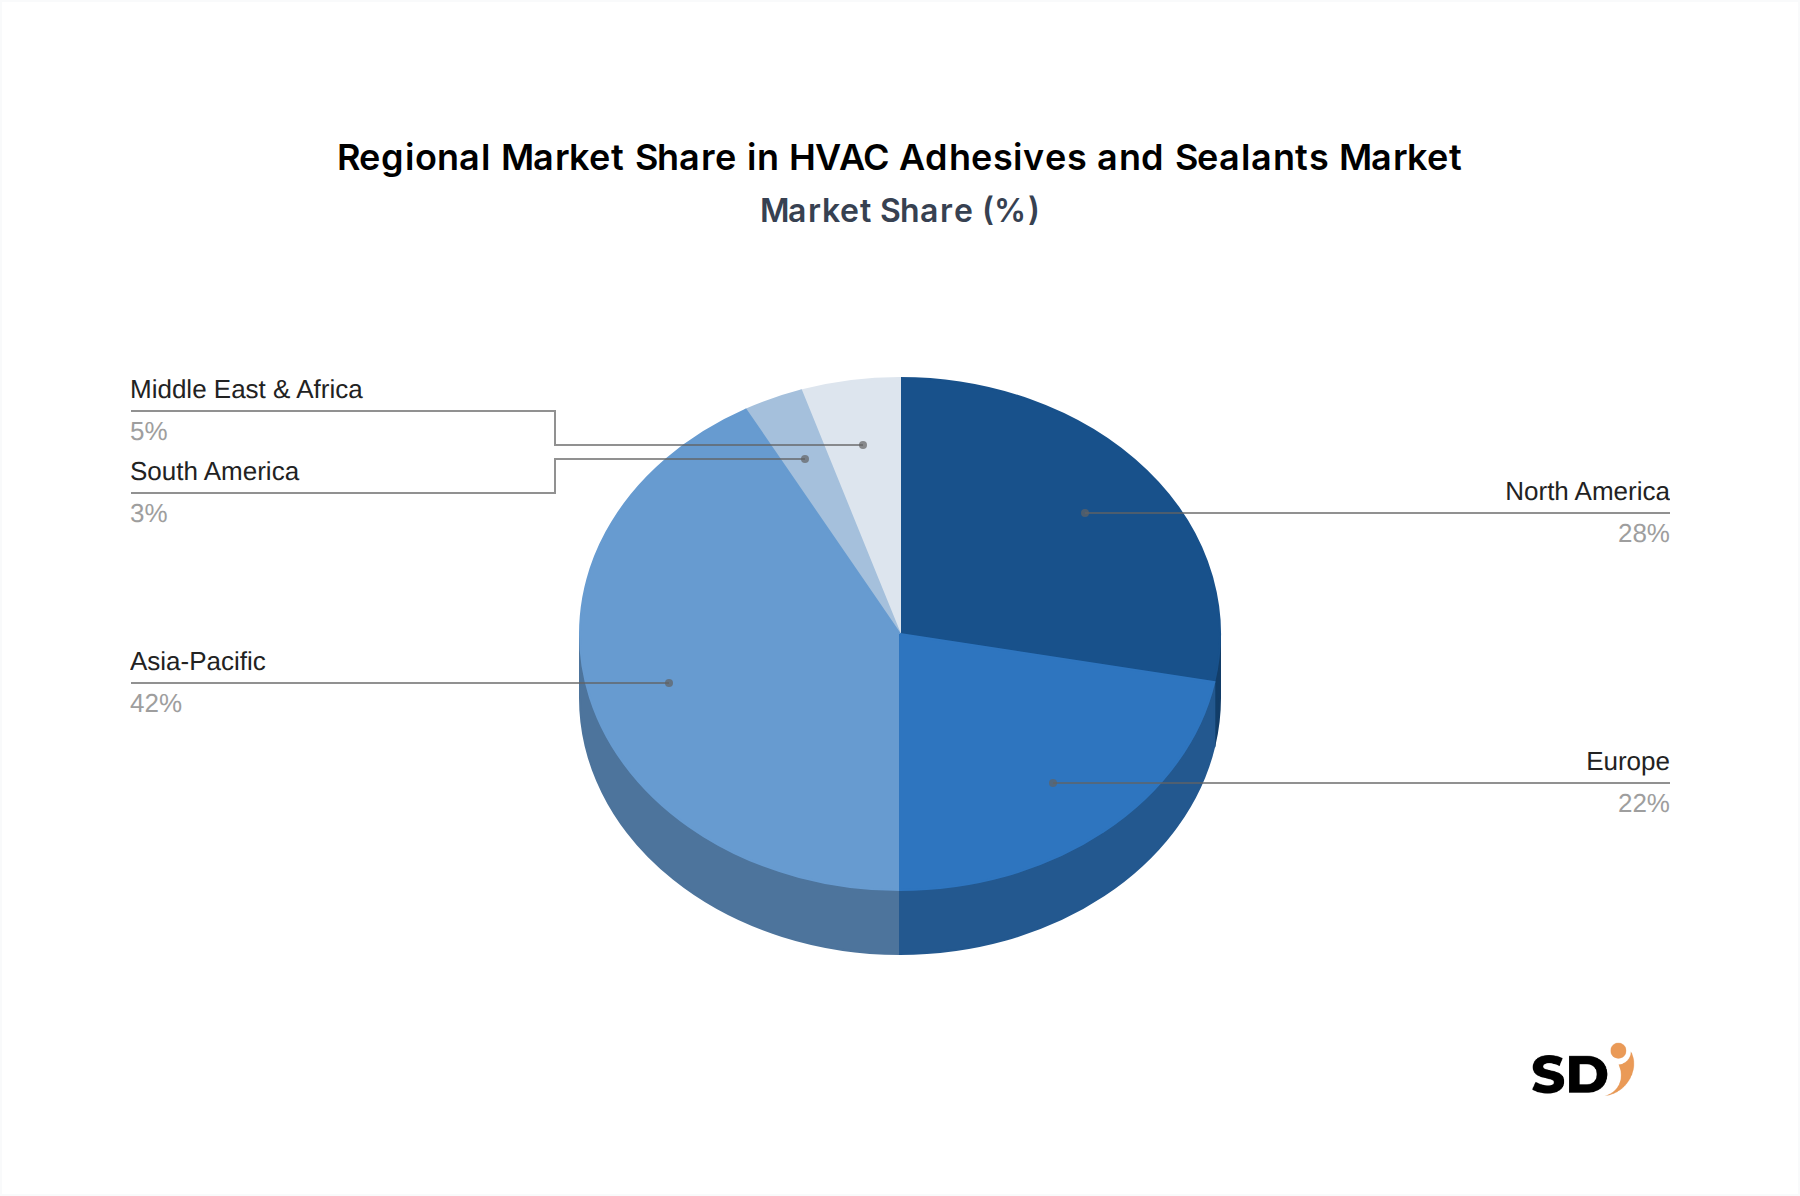
Key drivers include the proliferation of advanced HVAC systems that necessitate high-performance bonding and sealing agents, capable of withstanding extreme temperatures, vibrations, and corrosive environments. Regulatory mandates for reduced volatile organic compound (VOC) emissions are simultaneously catalyzing innovation, fostering a shift towards more sustainable, low-VOC, and solvent-free formulations. Asia Pacific is anticipated to emerge as the dominant regional market, fueled by massive infrastructure investments and burgeoning construction activities. Within the product landscape, the Neutral Cure Silicone Sealant Market is a significant revenue generator, valued for its superior adhesion, flexibility, and non-corrosive properties, making it ideal for a wide array of HVAC applications. Similarly, the Hybrid Adhesive Market is gaining traction due to its versatile performance characteristics. The strategic evolution of the HVAC Adhesives and Sealants Market is also influenced by advancements in the broader Building Materials Market, with an increasing emphasis on integrated, high-performance building envelopes. Companies like Henkel, Sika Group, and HB Fuller are at the forefront of this evolution, investing heavily in R&D to meet evolving performance standards and environmental criteria.
Segment Deep-Dive: Neutral Cure Silicone Sealant Dominance in HVAC Adhesives and Sealants Market
Within the highly specialized HVAC Adhesives and Sealants Market, the Neutral Cure Silicone Sealant segment currently commands a substantial market share, demonstrating strong growth trajectory. This dominance stems from the unique performance attributes that neutral cure silicones offer, which are particularly critical in demanding HVAC environments. Unlike acetoxy cure silicones, neutral cure formulations release alcohol or other non-corrosive by-products during curing, making them safe for use on sensitive metals and plastics commonly found in HVAC components such as copper coils, aluminum ducts, and galvanized steel. This non-corrosive property is paramount in preventing premature degradation and ensuring the longevity of expensive HVAC installations.
Performance Advantages & Applications
Neutral cure silicones exhibit exceptional resistance to extreme temperatures, ranging from sub-zero to high heat, a fundamental requirement for materials used in both heating and cooling units. Their excellent UV stability ensures long-term performance in outdoor components like condensers, while superior moisture resistance prevents leaks and mildew growth in humid conditions, which is vital for maintaining indoor air quality and system efficiency. Furthermore, their inherent flexibility allows them to accommodate thermal expansion and contraction, preventing cracks and loss of adhesion over time. Key applications within HVAC include sealing ductwork, insulating pipe joints, bonding insulation panels, sealing around vents and registers, and providing weatherproofing for outdoor units. This widespread utility underpins the robust expansion of the Neutral Cure Silicone Sealant Market.
Market Dynamics and Competitive Landscape
The demand for neutral cure silicones is further propelled by the increasing complexity and efficiency requirements of modern HVAC systems. As Smart Building Technology Market solutions gain traction, the need for reliable, long-lasting seals that contribute to overall system integrity and energy performance becomes even more critical. Major players in the Specialty Chemicals Market, such as Henkel, Sika Group, Bostik, and BASF, are significant manufacturers in this segment, continually innovating to enhance formulations, improve application ease, and meet stringent regulatory standards for VOC emissions. While neutral cure silicones hold a strong position, the Hybrid Adhesive Market, featuring technologies like silane-modified polymers (SMPs), presents a strong complementary and sometimes competitive offering, particularly where very high strength adhesion combined with flexibility is required. However, the balance of cost-effectiveness, ease of application, and unparalleled environmental resistance ensures that neutral cure silicone sealants maintain their lead in many core HVAC sealing applications. The segment's share is expected to expand further as green building initiatives and energy efficiency mandates become globally pervasive, driving the adoption of high-performance sealing solutions.
Primary Market Drivers & Growth Restraints in HVAC Adhesives and Sealants Market
The growth trajectory of the HVAC Adhesives and Sealants Market is shaped by a confluence of powerful drivers and inherent restraints. Understanding these dynamics is crucial for strategic market positioning.
Key Market Drivers
Surging Construction Activity & Urbanization: Rapid urbanization and industrialization, particularly in the Asia Pacific and Middle East & Africa regions, are spurring unprecedented growth in residential, commercial, and industrial construction. New building projects inherently require extensive HVAC installations, directly translating into increased demand for adhesives and sealants for ductwork, insulation, and component assembly. This aligns closely with growth in the overall Building Materials Market.
Stringent Energy Efficiency Regulations: Governments worldwide are implementing stricter building codes and energy performance standards (ee.g., LEED, BREEAM) to combat climate change and reduce energy consumption. High-performance adhesives and sealants are vital for creating airtight HVAC systems, minimizing energy losses, and improving system efficiency. This regulatory push mandates the use of superior sealing materials, thereby expanding the market.
Enhanced Indoor Air Quality (IAQ) Standards: Growing public awareness and regulatory emphasis on IAQ, especially post-pandemic, are driving the adoption of advanced HVAC systems that prevent the ingress of pollutants and ensure proper ventilation. Sealants play a critical role in preventing air leakage and mold growth within ducts, directly contributing to healthier indoor environments.
Technological Advancements in HVAC Systems: The evolution of more sophisticated and compact HVAC units, including variable refrigerant flow (VRF) systems and modular designs, necessitates specialized adhesives and sealants capable of bonding diverse materials, enduring higher pressures, and facilitating complex assemblies. This innovation trajectory creates a continuous demand for advanced Polymer Adhesives Market products.
Growth Restraints
Volatile Raw Material Prices: The HVAC adhesives and sealants industry is heavily reliant on petrochemical-derived raw materials such such as siloxanes for silicones, polyurethanes, and acrylics. Price fluctuations in crude oil and other chemical intermediates directly impact manufacturing costs, leading to margin pressures for market players and potential price increases for end-users. This affects the broader Specialty Chemicals Market segment.
Stringent Environmental Regulations on VOC Emissions: While driving innovation, increasing regulatory scrutiny over VOC emissions (e.g., California's SCAQMD, EU REACH) poses a significant challenge. Manufacturers must invest heavily in R&D to reformulate products, transitioning from solvent-based to water-based, hot-melt, or 100% solids technologies, which can be costly and time-consuming. Non-compliance can lead to hefty fines and market exclusion.
Intense Competition and Price Sensitivity: The market is characterized by a significant number of regional and global players, leading to intense competition. In certain segments, price becomes a critical deciding factor for procurement, especially for commodity-grade products. This can lead to downward pressure on pricing and profitability for manufacturers.
The global HVAC Adhesives and Sealants Market is characterized by the presence of several multinational chemical and material science companies alongside specialized regional players. These companies are actively engaged in product innovation, strategic partnerships, and mergers & acquisitions to enhance their market footprint and technological capabilities. Key players include:
HB Fuller: A leading global adhesive manufacturer, HB Fuller provides a broad portfolio of high-performance adhesives for various applications, including HVAC. The company focuses on sustainable solutions and specialized formulations for demanding industrial applications.
Henkel: A diversified global leader in adhesive technologies, Henkel offers an extensive range of adhesives, sealants, and functional coatings crucial for HVAC assembly and sealing. Henkel is known for its strong R&D capabilities and comprehensive product portfolio across numerous industries.
Sika Group: A specialty chemicals company with a strong focus on sealing, bonding, damping, reinforcing, and protecting building and industrial applications. Sika offers high-performance sealants and adhesives specifically designed for HVAC ductwork and component sealing.
Adfast: Specializing in sealants, adhesives, and specialty chemical products, Adfast serves various construction and industrial markets, including HVAC. They emphasize innovative, high-quality, and environmentally responsible solutions.
Bostik: As an Arkema company, Bostik is a global leader in specialty adhesives and sealants. It provides advanced bonding and sealing solutions for the construction, industrial, and consumer markets, with a strong presence in HVAC applications, focusing on efficiency and durability.
Airseal: A niche player focusing on specialized sealing and insulation products, often catering to industrial and HVAC applications where airtightness and thermal performance are critical. Their expertise lies in high-performance tapes and sealants.
Design Polymerics: Specializes in producing sealants, coatings, and adhesives for the HVAC, construction, and manufacturing industries. They are known for providing solutions that meet specific performance requirements for duct sealing and thermal insulation.
Euclid Chemical: Primarily focused on concrete and masonry construction products, Euclid Chemical also offers specialized sealants and coatings that find applications in the structural aspects of HVAC installations and building envelopes.
BASF: One of the world's largest chemical producers, BASF supplies a wide range of raw materials, polymers, and specialty chemicals that are integral to the formulation of advanced HVAC adhesives and sealants. They contribute to the Polymer Adhesives Market through their vast chemical expertise.
Strategic Milestones & Recent Developments in HVAC Adhesives and Sealants Market
The HVAC Adhesives and Sealants Market is dynamic, with continuous strategic activities aimed at innovation, market expansion, and sustainability.
Q4 2024: Leading players announced investments in new production capacities for low-VOC and solvent-free adhesive formulations in Asia Pacific, aiming to capture demand from the booming construction sector and stricter environmental regulations.
Q2 2024: Several manufacturers launched new lines of fire-rated sealants specifically designed for HVAC duct penetrations, meeting evolving building safety codes and expanding their product offerings in the Industrial Sealants Market.
Q1 2024: A major Specialty Chemicals Market player acquired a smaller firm specializing in bio-based adhesives, signaling a strategic shift towards more sustainable and environmentally friendly product portfolios in the HVAC sector.
Q3 2023: Strategic partnerships were forged between HVAC system manufacturers and adhesive suppliers to co-develop integrated sealing solutions, ensuring optimal performance and streamlined assembly processes for next-generation systems.
Q1 2023: Developments in the Hybrid Adhesive Market saw the introduction of novel silane-modified polymer (SMP) adhesives offering enhanced flexibility, faster cure times, and superior adhesion to diverse substrates, directly addressing complex HVAC assembly challenges.
Q4 2022: Companies focused on digital transformation initiatives, including implementing AI-driven material discovery platforms to accelerate the development of high-performance and customized adhesive and sealant solutions for the HVAC industry.
Regional Market Analysis & Growth Corridors for HVAC Adhesives and Sealants Market
The global HVAC Adhesives and Sealants Market demonstrates varied growth dynamics across key geographical regions, influenced by economic development, regulatory frameworks, and construction trends.
Asia Pacific: The Fastest-Growing Corridor
Asia Pacific is projected to be the fastest-growing and largest regional market, driven by extensive urbanization, industrialization, and infrastructure development, particularly in China, India, and ASEAN countries. The region's burgeoning middle class, coupled with government investments in smart cities and green buildings, is fueling demand for advanced HVAC systems. This rapid expansion in construction directly translates to a robust Construction Adhesives Market and high consumption of HVAC adhesives and sealants. Furthermore, increasing awareness regarding energy efficiency and indoor air quality in these developing economies is accelerating the adoption of high-performance sealing solutions.
North America & Europe: Mature Markets with Innovation Focus
North America and Europe represent mature markets characterized by stringent environmental regulations and a strong emphasis on energy efficiency and renovation projects. While new construction rates might be slower than in Asia Pacific, the demand for sophisticated, low-VOC, and sustainable HVAC adhesives and sealants remains high. The focus here is on upgrading existing infrastructure to meet evolving green building standards and on innovative materials for high-value applications. The Neutral Cure Silicone Sealant Market and the Hybrid Adhesive Market are particularly strong in these regions due to their superior performance attributes and compliance with strict standards.
Middle East & Africa (MEA): Climate-Driven Demand
The MEA region exhibits significant growth potential, primarily driven by large-scale infrastructure projects, rapid population growth, and the extreme climatic conditions that necessitate efficient air conditioning systems. Countries within the GCC are investing heavily in commercial and residential developments, creating substantial demand for robust and durable HVAC sealing solutions that can withstand high temperatures and harsh environments. South Africa also contributes significantly to this regional growth.
South America: Emerging Opportunities
South America presents an emerging market with gradual growth. Economic stability and increasing foreign investments in countries like Brazil and Argentina are contributing to the expansion of their construction sectors. As building codes evolve and awareness of energy efficiency grows, the demand for specialized HVAC adhesives and sealants is expected to rise steadily, albeit from a lower base compared to other regions.
Investment, M&A & Funding Activity in HVAC Adhesives and Sealants Market
Investment and M&A activity in the HVAC Adhesives and Sealants Market reflect a broader trend within the Specialty Chemicals Market towards consolidation, innovation, and sustainability. Over the past 2-3 years, strategic acquisitions have been a prevalent theme, with larger chemical conglomerates acquiring niche players to bolster their product portfolios, expand geographical reach, or gain access to proprietary technologies. Companies are particularly keen on acquiring firms with expertise in environmentally friendly formulations, such as low-VOC, water-based, and bio-based adhesives and sealants, driven by consumer preference and regulatory pressures.
Private equity and venture capital investments have primarily targeted startups and smaller enterprises focused on disruptive material innovations or advanced application technologies relevant to energy efficiency in buildings. These investments often aim to scale up novel solutions that promise significant performance improvements or cost reductions in HVAC system assembly and maintenance. Strategic partnerships between adhesive manufacturers and HVAC system integrators are also common, aiming to co-develop customized solutions that enhance system performance and simplify installation processes. The Construction Adhesives Market and Building Materials Market segments are attracting significant capital, with investors keen on solutions that contribute to resilient, energy-efficient, and sustainable building envelopes.
Technology Innovation & R&D Trajectory in HVAC Adhesives and Sealants Market
Technology innovation is a cornerstone of growth in the HVAC Adhesives and Sealants Market, driven by evolving performance demands, sustainability imperatives, and the advent of Smart Building Technology Market. R&D efforts are focused on creating solutions that offer enhanced durability, ease of application, and environmental compliance.
1. Advanced Low-VOC and Sustainable Formulations
Perhaps the most disruptive trend is the relentless pursuit of low-VOC (volatile organic compound) and solvent-free adhesive and sealant systems. Driven by stringent environmental regulations and green building standards, R&D is heavily invested in developing water-based, 100% solids, and reactive hot-melt technologies. Bio-based polymers and recycled content are also gaining traction, moving towards a circular economy model. These innovations not only improve indoor air quality but also reduce health risks for applicators, reinforcing the shift away from traditional solvent-borne chemistries.
2. High-Performance Hybrid Polymer Adhesives
Hybrid adhesives, particularly those based on silane-modified polymers (SMPs), represent a significant technological leap. These materials combine the best properties of silicones and polyurethanes, offering superior adhesion to a wide variety of substrates (metals, plastics, concrete), excellent elasticity, UV stability, and paintability. Their versatility makes them ideal for complex HVAC assemblies requiring both strong bonding and flexible sealing. Adoption timelines are accelerating as manufacturers recognize their ability to simplify processes and improve long-term system integrity. The Hybrid Adhesive Market is experiencing rapid growth as a result of these innovations, posing a strong alternative or complement to traditional Neutral Cure Silicone Sealant Market offerings.
3. Smart Adhesives and Functional Integration
Emerging technologies are exploring the integration of smart functionalities directly into adhesives and sealants. This includes self-healing polymers that can repair minor cracks autonomously, reducing maintenance needs and extending product lifespan. Research is also underway on integrating sensors into adhesive layers to monitor bond line integrity, temperature, or moisture levels in real-time within HVAC systems, providing predictive maintenance capabilities. While still largely in the R&D phase, these innovations have the potential to significantly reinforce incumbent business models by offering high-value, digitally-enhanced solutions, transforming the way HVAC systems are installed and monitored.
HVAC Adhesives and Sealants Segmentation
1. Application
1.1. Condenser
1.2. Water Heating and Boiler Units
1.3. Others
2. Types
2.1. Hybrid Adhesive
2.2. Neutral Cure Silicone Sealant
HVAC Adhesives and Sealants Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
HVAC Adhesives and Sealants REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 6% from 2020-2034
Segmentation
By Application
Condenser
Water Heating and Boiler Units
Others
By Types
Hybrid Adhesive
Neutral Cure Silicone Sealant
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Application
5.1.1. Condenser
5.1.2. Water Heating and Boiler Units
5.1.3. Others
5.2. Market Analysis, Insights and Forecast - by Types
5.2.1. Hybrid Adhesive
5.2.2. Neutral Cure Silicone Sealant
5.3. Market Analysis, Insights and Forecast - by Region
5.3.1. North America
5.3.2. South America
5.3.3. Europe
5.3.4. Middle East & Africa
5.3.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Application
6.1.1. Condenser
6.1.2. Water Heating and Boiler Units
6.1.3. Others
6.2. Market Analysis, Insights and Forecast - by Types
6.2.1. Hybrid Adhesive
6.2.2. Neutral Cure Silicone Sealant
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Application
7.1.1. Condenser
7.1.2. Water Heating and Boiler Units
7.1.3. Others
7.2. Market Analysis, Insights and Forecast - by Types
7.2.1. Hybrid Adhesive
7.2.2. Neutral Cure Silicone Sealant
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Application
8.1.1. Condenser
8.1.2. Water Heating and Boiler Units
8.1.3. Others
8.2. Market Analysis, Insights and Forecast - by Types
8.2.1. Hybrid Adhesive
8.2.2. Neutral Cure Silicone Sealant
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Application
9.1.1. Condenser
9.1.2. Water Heating and Boiler Units
9.1.3. Others
9.2. Market Analysis, Insights and Forecast - by Types
9.2.1. Hybrid Adhesive
9.2.2. Neutral Cure Silicone Sealant
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Application
10.1.1. Condenser
10.1.2. Water Heating and Boiler Units
10.1.3. Others
10.2. Market Analysis, Insights and Forecast - by Types
10.2.1. Hybrid Adhesive
10.2.2. Neutral Cure Silicone Sealant
11. Competitive Analysis
11.1. Company Profiles
11.1.1. HB Fuller
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Henkel
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Sika Group
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Adfast
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Bostik
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Airseal
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Design Polymerics
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Euclid Chemical
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. BASF
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: HVAC Adhesives and Sealants Revenue Breakdown (billion, %) by Region 2026 & 2034
Figure 2: North America HVAC Adhesives and Sealants Revenue (billion), by Application 2026 & 2034
Figure 3: North America HVAC Adhesives and Sealants Revenue Share (%), by Application 2026 & 2034
Figure 4: North America HVAC Adhesives and Sealants Revenue (billion), by Types 2026 & 2034
Figure 5: North America HVAC Adhesives and Sealants Revenue Share (%), by Types 2026 & 2034
Figure 6: North America HVAC Adhesives and Sealants Revenue (billion), by Country 2026 & 2034
Figure 7: North America HVAC Adhesives and Sealants Revenue Share (%), by Country 2026 & 2034
Figure 8: South America HVAC Adhesives and Sealants Revenue (billion), by Application 2026 & 2034
Figure 9: South America HVAC Adhesives and Sealants Revenue Share (%), by Application 2026 & 2034
Figure 10: South America HVAC Adhesives and Sealants Revenue (billion), by Types 2026 & 2034
Figure 11: South America HVAC Adhesives and Sealants Revenue Share (%), by Types 2026 & 2034
Figure 12: South America HVAC Adhesives and Sealants Revenue (billion), by Country 2026 & 2034
Figure 13: South America HVAC Adhesives and Sealants Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe HVAC Adhesives and Sealants Revenue (billion), by Application 2026 & 2034
Figure 15: Europe HVAC Adhesives and Sealants Revenue Share (%), by Application 2026 & 2034
Figure 16: Europe HVAC Adhesives and Sealants Revenue (billion), by Types 2026 & 2034
Figure 17: Europe HVAC Adhesives and Sealants Revenue Share (%), by Types 2026 & 2034
Figure 18: Europe HVAC Adhesives and Sealants Revenue (billion), by Country 2026 & 2034
Figure 19: Europe HVAC Adhesives and Sealants Revenue Share (%), by Country 2026 & 2034
Figure 20: Middle East & Africa HVAC Adhesives and Sealants Revenue (billion), by Application 2026 & 2034
Figure 21: Middle East & Africa HVAC Adhesives and Sealants Revenue Share (%), by Application 2026 & 2034
Figure 22: Middle East & Africa HVAC Adhesives and Sealants Revenue (billion), by Types 2026 & 2034
Figure 23: Middle East & Africa HVAC Adhesives and Sealants Revenue Share (%), by Types 2026 & 2034
Figure 24: Middle East & Africa HVAC Adhesives and Sealants Revenue (billion), by Country 2026 & 2034
Figure 25: Middle East & Africa HVAC Adhesives and Sealants Revenue Share (%), by Country 2026 & 2034
Figure 26: Asia Pacific HVAC Adhesives and Sealants Revenue (billion), by Application 2026 & 2034
Figure 27: Asia Pacific HVAC Adhesives and Sealants Revenue Share (%), by Application 2026 & 2034
Figure 28: Asia Pacific HVAC Adhesives and Sealants Revenue (billion), by Types 2026 & 2034
Figure 29: Asia Pacific HVAC Adhesives and Sealants Revenue Share (%), by Types 2026 & 2034
Figure 30: Asia Pacific HVAC Adhesives and Sealants Revenue (billion), by Country 2026 & 2034
Figure 31: Asia Pacific HVAC Adhesives and Sealants Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: HVAC Adhesives and Sealants Revenue billion Forecast, by Application 2020 & 2034
Table 2: HVAC Adhesives and Sealants Revenue billion Forecast, by Types 2020 & 2034
Table 3: HVAC Adhesives and Sealants Revenue billion Forecast, by Region 2020 & 2034
Table 4: North America HVAC Adhesives and Sealants Revenue billion Forecast, by Application 2020 & 2034
Table 5: North America HVAC Adhesives and Sealants Revenue billion Forecast, by Types 2020 & 2034
Table 6: North America HVAC Adhesives and Sealants Revenue billion Forecast, by Country 2020 & 2034
Table 7: United States HVAC Adhesives and Sealants Revenue (billion) Forecast, by Application 2020 & 2034
Table 8: Canada HVAC Adhesives and Sealants Revenue (billion) Forecast, by Application 2020 & 2034
Table 9: Mexico HVAC Adhesives and Sealants Revenue (billion) Forecast, by Application 2020 & 2034
Table 10: South America HVAC Adhesives and Sealants Revenue billion Forecast, by Application 2020 & 2034
Table 11: South America HVAC Adhesives and Sealants Revenue billion Forecast, by Types 2020 & 2034
Table 12: South America HVAC Adhesives and Sealants Revenue billion Forecast, by Country 2020 & 2034
Table 13: Brazil HVAC Adhesives and Sealants Revenue (billion) Forecast, by Application 2020 & 2034
Table 14: Argentina HVAC Adhesives and Sealants Revenue (billion) Forecast, by Application 2020 & 2034
Table 15: Rest of South America HVAC Adhesives and Sealants Revenue (billion) Forecast, by Application 2020 & 2034
Table 16: Europe HVAC Adhesives and Sealants Revenue billion Forecast, by Application 2020 & 2034
Table 17: Europe HVAC Adhesives and Sealants Revenue billion Forecast, by Types 2020 & 2034
Table 18: Europe HVAC Adhesives and Sealants Revenue billion Forecast, by Country 2020 & 2034
Table 19: United Kingdom HVAC Adhesives and Sealants Revenue (billion) Forecast, by Application 2020 & 2034
Table 20: Germany HVAC Adhesives and Sealants Revenue (billion) Forecast, by Application 2020 & 2034
Table 21: France HVAC Adhesives and Sealants Revenue (billion) Forecast, by Application 2020 & 2034
Table 22: Italy HVAC Adhesives and Sealants Revenue (billion) Forecast, by Application 2020 & 2034
Table 23: Spain HVAC Adhesives and Sealants Revenue (billion) Forecast, by Application 2020 & 2034
Table 24: Russia HVAC Adhesives and Sealants Revenue (billion) Forecast, by Application 2020 & 2034
Table 25: Benelux HVAC Adhesives and Sealants Revenue (billion) Forecast, by Application 2020 & 2034
Table 26: Nordics HVAC Adhesives and Sealants Revenue (billion) Forecast, by Application 2020 & 2034
Table 27: Rest of Europe HVAC Adhesives and Sealants Revenue (billion) Forecast, by Application 2020 & 2034
Table 28: Middle East & Africa HVAC Adhesives and Sealants Revenue billion Forecast, by Application 2020 & 2034
Table 29: Middle East & Africa HVAC Adhesives and Sealants Revenue billion Forecast, by Types 2020 & 2034
Table 30: Middle East & Africa HVAC Adhesives and Sealants Revenue billion Forecast, by Country 2020 & 2034
Table 31: Turkey HVAC Adhesives and Sealants Revenue (billion) Forecast, by Application 2020 & 2034
Table 32: Israel HVAC Adhesives and Sealants Revenue (billion) Forecast, by Application 2020 & 2034
Table 33: GCC HVAC Adhesives and Sealants Revenue (billion) Forecast, by Application 2020 & 2034
Table 34: North Africa HVAC Adhesives and Sealants Revenue (billion) Forecast, by Application 2020 & 2034
Table 35: South Africa HVAC Adhesives and Sealants Revenue (billion) Forecast, by Application 2020 & 2034
Table 36: Rest of Middle East & Africa HVAC Adhesives and Sealants Revenue (billion) Forecast, by Application 2020 & 2034
Table 37: Asia Pacific HVAC Adhesives and Sealants Revenue billion Forecast, by Application 2020 & 2034
Table 38: Asia Pacific HVAC Adhesives and Sealants Revenue billion Forecast, by Types 2020 & 2034
Table 39: Asia Pacific HVAC Adhesives and Sealants Revenue billion Forecast, by Country 2020 & 2034
Table 40: China HVAC Adhesives and Sealants Revenue (billion) Forecast, by Application 2020 & 2034
Table 41: India HVAC Adhesives and Sealants Revenue (billion) Forecast, by Application 2020 & 2034
Table 42: Japan HVAC Adhesives and Sealants Revenue (billion) Forecast, by Application 2020 & 2034
Table 43: South Korea HVAC Adhesives and Sealants Revenue (billion) Forecast, by Application 2020 & 2034
Table 44: ASEAN HVAC Adhesives and Sealants Revenue (billion) Forecast, by Application 2020 & 2034
Table 45: Oceania HVAC Adhesives and Sealants Revenue (billion) Forecast, by Application 2020 & 2034
Table 46: Rest of Asia Pacific HVAC Adhesives and Sealants Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our comprehensive market research methodology for the "HVAC Adhesives and Sealants" report employs a rigorous multi-pronged approach, designed to deliver high-fidelity market sizing, accurate forecasts, and actionable strategic insights. This methodology integrates our firm's established static protocols with dynamic, market-specific inferences to provide an unparalleled understanding of the current landscape and future trajectory of this specialized sector. We guarantee an estimated data accuracy level of 85-90% for all quantitative findings.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D / Technical Directors
30%
Procurement / Supply Chain Directors
30%
Product / Market Managers
25%
Field Application Engineers / Technical Sales
15%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Adhesive & Sealant Manufacturers
40%
HVAC System OEMs
30%
Raw Material Suppliers
15%
HVAC Service & Installation Firms
15%
Primary Research
Primary research constitutes the cornerstone of our analysis, accounting for 70-80% of our total research efforts. This intensive qualitative and quantitative outreach involves direct engagement with key stakeholders across the HVAC adhesives and sealants value chain. Our approach emphasizes in-depth interviews, expert panels, and targeted surveys to gather proprietary insights, validate secondary findings, and identify nuanced market dynamics. Key participants in our primary research include:
Company Types:
Adhesive and Sealant Manufacturers (e.g., specialized formulators for HVAC applications)
HVAC System Original Equipment Manufacturers (OEMs)
Raw Material Suppliers (e.g., silicone, polyurethane, epoxy resin producers)
Specialty Chemical Distributors focused on industrial applications
Large-scale HVAC Installation and Service Contractors
Key Stakeholders Interviewed:
R&D Directors or Lead Chemists specializing in adhesive/sealant formulation
Procurement Managers or Supply Chain Directors at HVAC OEM companies
Product Managers or Market Analysts within adhesive/sealant manufacturing firms
Technical Sales Managers or Field Application Engineers serving the HVAC industry
This direct engagement provides critical perspectives on product development trends, adoption rates, supply chain challenges, pricing strategies, and regional market specificities, enabling us to capture real-time market sentiment and emerging opportunities.
Secondary Research & Industry Benchmarking
The remaining 20-30% of our research is dedicated to robust secondary data collection and industry benchmarking. This phase establishes the foundational market context, identifies key players, and corroborates primary research findings. Our secondary research draws exclusively from credible, authoritative sources, avoiding other market research publications to maintain data integrity and uniqueness. Sources include:
Financial Databases: Bloomberg, Factiva, Hoovers, PitchBook for company profiles, financial performance, and M&A activities.
Government Publications: Official statistics and reports from national industrial bodies (e.g., U.S. Census Bureau – Manufacturing Data, European Commission Industry Reports).
Organizational & Trade Association Data: Publications and statistical data from globally recognized industry bodies. Examples include:
Company Annual Reports and Investor Presentations: Direct corporate communications providing insights into strategies, segment performance, and market outlooks.
Technical Journals and Patents: For understanding innovation, material science advancements, and emerging application areas.
Crucially, every report is updated up to the date of purchase, ensuring that our clients receive the most current and relevant market intelligence available.
Demand Modeling & Market Estimation
Our market sizing and forecasting methodologies integrate both top-down and bottom-up approaches, underpinned by multi-level data triangulation to ensure maximum accuracy and reliability. The top-down approach involves analyzing macro-economic indicators, HVAC industry growth rates, and broad market trends to derive initial market estimates. The bottom-up methodology, which is particularly critical for this specialized market, involves granular data aggregation based on specific market drivers and variables, including:
Key Metrics for Bottom-Up Calculation:
Annual HVAC unit production volumes (broken down by condenser, water heating, boiler, and other units) across key geographical regions.
Average adhesive and sealant consumption per HVAC unit (quantified by weight or volume, and differentiated by application and material type).
Average Selling Price (ASP) of various adhesive and sealant formulations relevant to HVAC applications, adjusted for regional variations.
Aftermarket and replacement demand for HVAC units and components, driving demand for repair and maintenance sealants/adhesives.
These granular data points are then projected using a combination of historical growth rates, projected end-user industry expansion (e.g., construction, manufacturing), and expert consensus gathered from primary interviews. The multi-level data triangulation process involves cross-referencing estimates derived from different sources and methodologies, refining discrepancies, and achieving a robust consensus.
Data Accuracy & Quality Check
Our commitment to data accuracy is paramount, targeting an estimated accuracy level of 85-90%. This is achieved through a rigorous, multi-stage validation process:
Cross-Referencing: All quantitative data points, especially market sizes and growth rates, are cross-referenced across multiple primary and secondary sources. Divergences are investigated, reconciled, and validated through additional expert consultations.
Peer Review: The entire research methodology, data sets, and analytical conclusions undergo a stringent internal peer review by senior analysts and subject matter experts to identify and address any potential biases or errors.
Iterative Refinement: Our forecasting models are continuously refined using an iterative process, integrating new data, market developments, and expert feedback to ensure the most current and accurate projections.
Qualitative Validation: Qualitative insights gathered during primary research are used to contextualize and validate quantitative findings, providing a deeper understanding of the market dynamics that drive the numbers.
This systematic approach ensures that our "HVAC Adhesives and Sealants" report provides highly reliable, actionable market intelligence, enabling clients to make informed strategic decisions.
Frequently Asked Questions
1. What disruptive technologies are influencing HVAC adhesives and sealants?
Innovations in polymer science are driving development of bio-based or reactive adhesive systems offering enhanced performance and environmental profiles. Advances in application equipment also optimize efficiency and reduce waste in HVAC installations.
2. How has the HVAC adhesives market recovered post-pandemic?
The market's recovery aligns with increased construction activity and retrofitting projects, spurred by renewed focus on indoor air quality. Supply chain resilience and localized production have become critical long-term structural shifts for companies like Henkel and Bostik.
3. What are the primary challenges facing the HVAC adhesives and sealants market?
Raw material price volatility and stricter environmental regulations pose significant challenges for manufacturers. Ensuring consistent supply chain integrity for components like specialized polymers and additives remains a key risk factor for market players.
4. Which end-user industries drive demand for HVAC adhesives and sealants?
Demand is primarily driven by residential and commercial construction, industrial HVAC manufacturing for units like condensers and water heating systems, and MRO activities. Growing infrastructure projects contribute to sustained demand patterns.
5. How do consumer preferences impact HVAC adhesive purchasing trends?
Increasing consumer emphasis on energy efficiency, indoor air quality, and product sustainability influences purchasing. This drives demand for high-performance, low-VOC sealants and adhesives used in efficient HVAC systems.
6. What recent developments or M&A activities have shaped the HVAC adhesives market?
Major players like HB Fuller, Sika Group, and BASF engage in strategic acquisitions to expand product portfolios and regional reach. Product innovations focus on developing hybrid adhesives and neutral cure silicone sealants with improved application properties and durability.