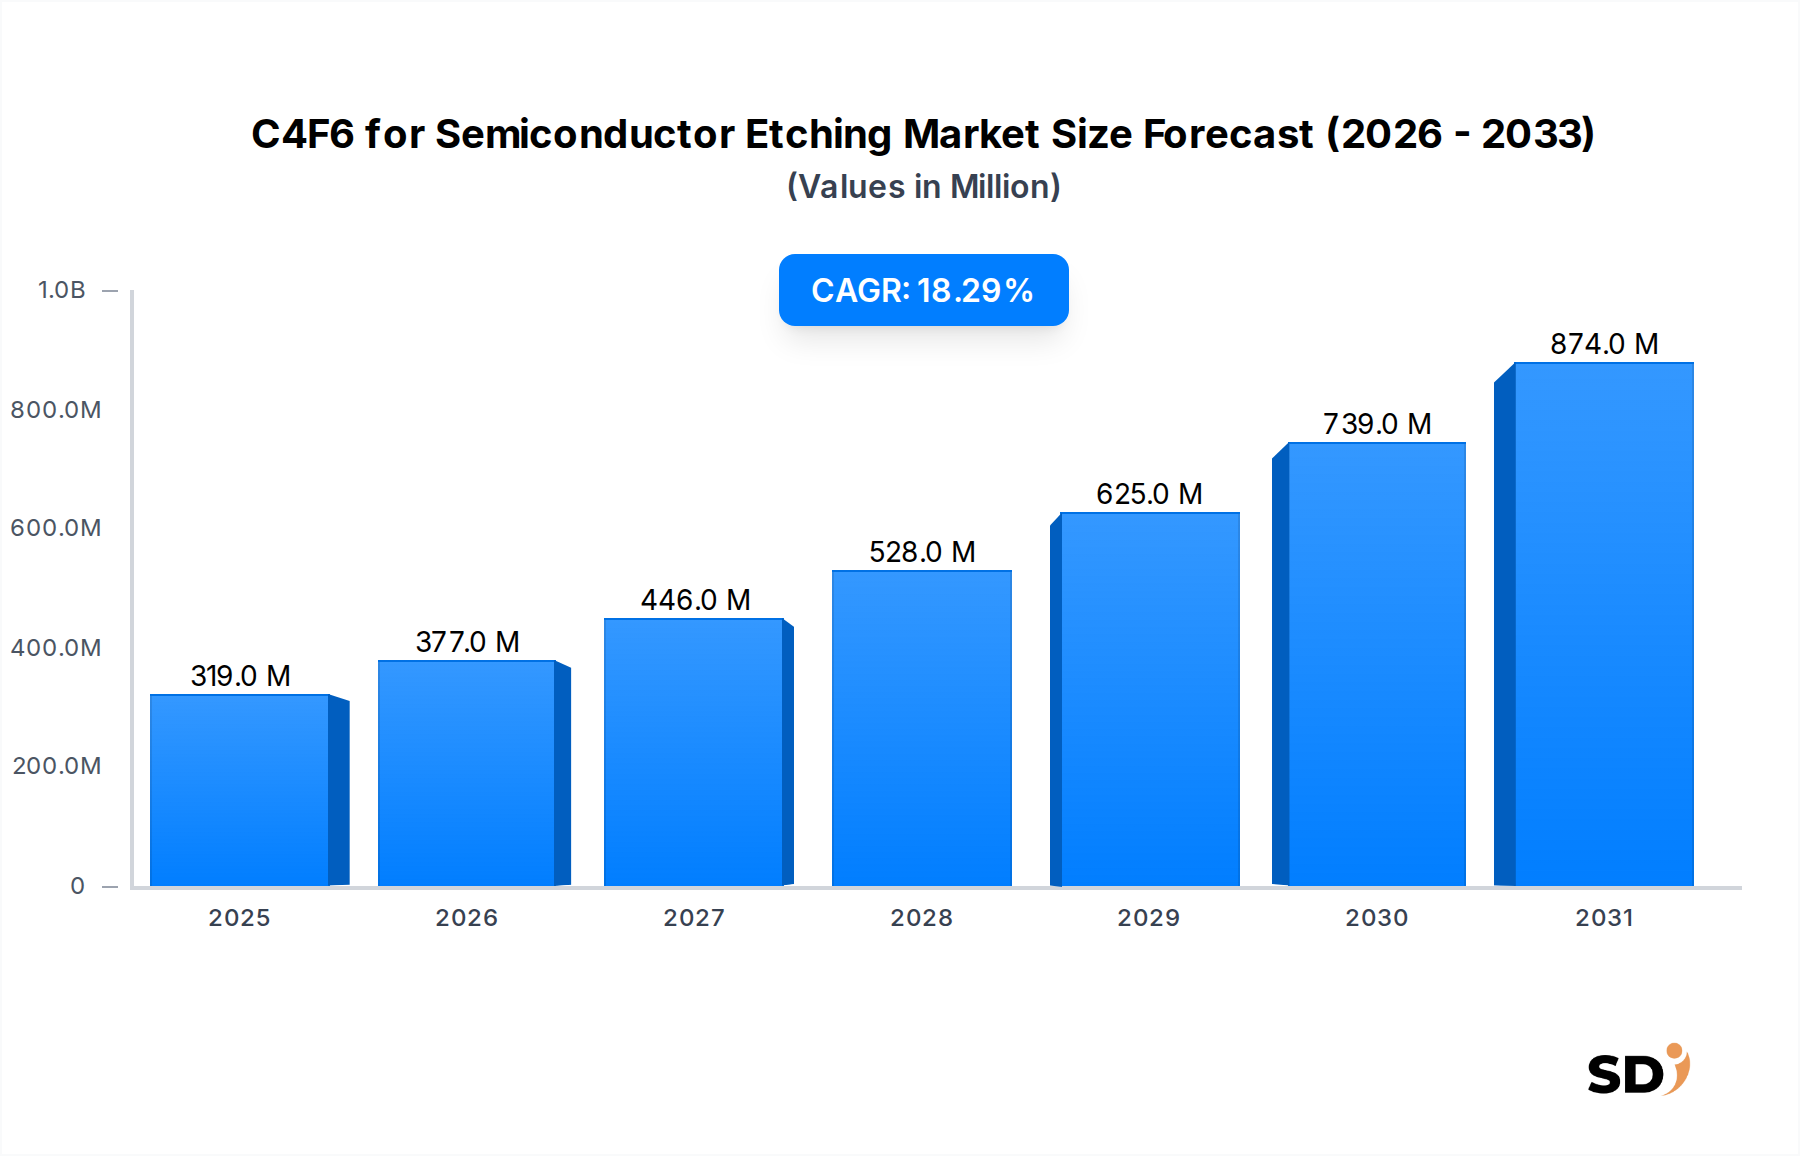
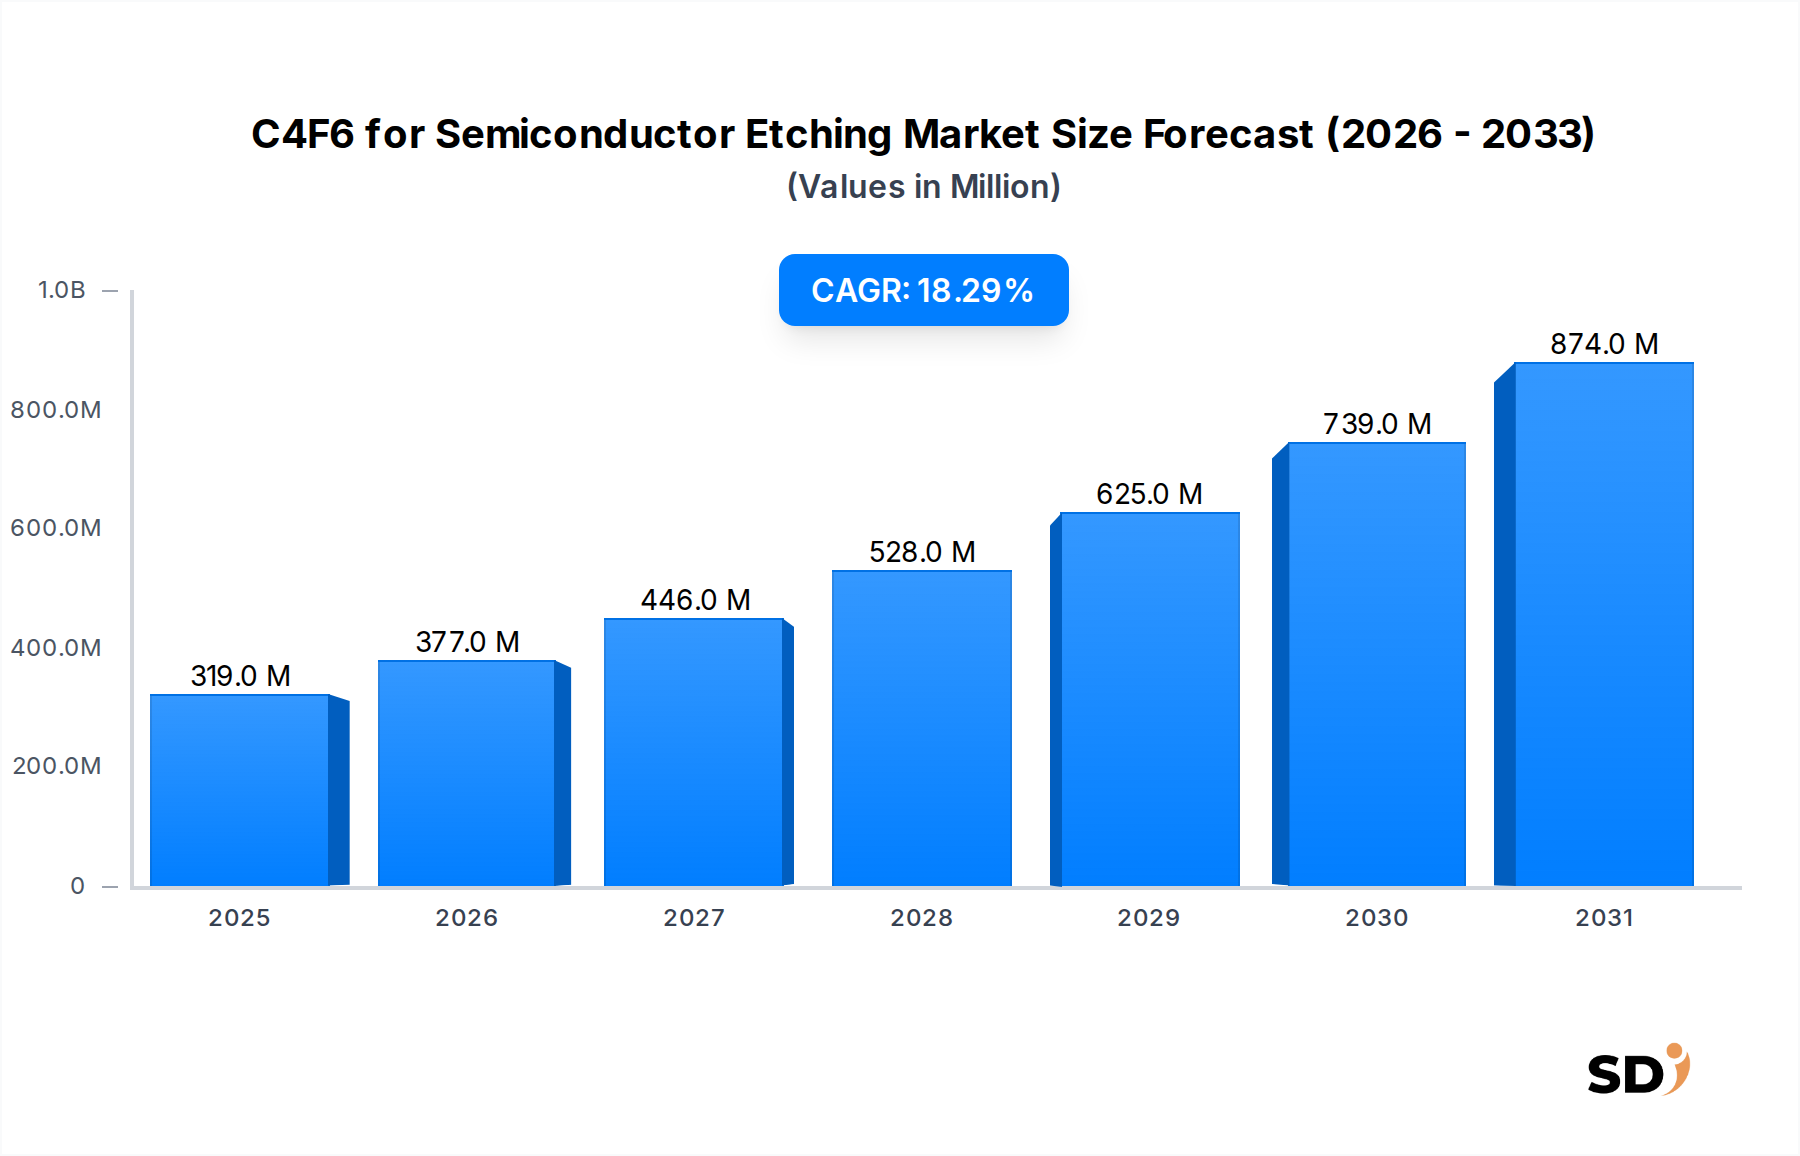
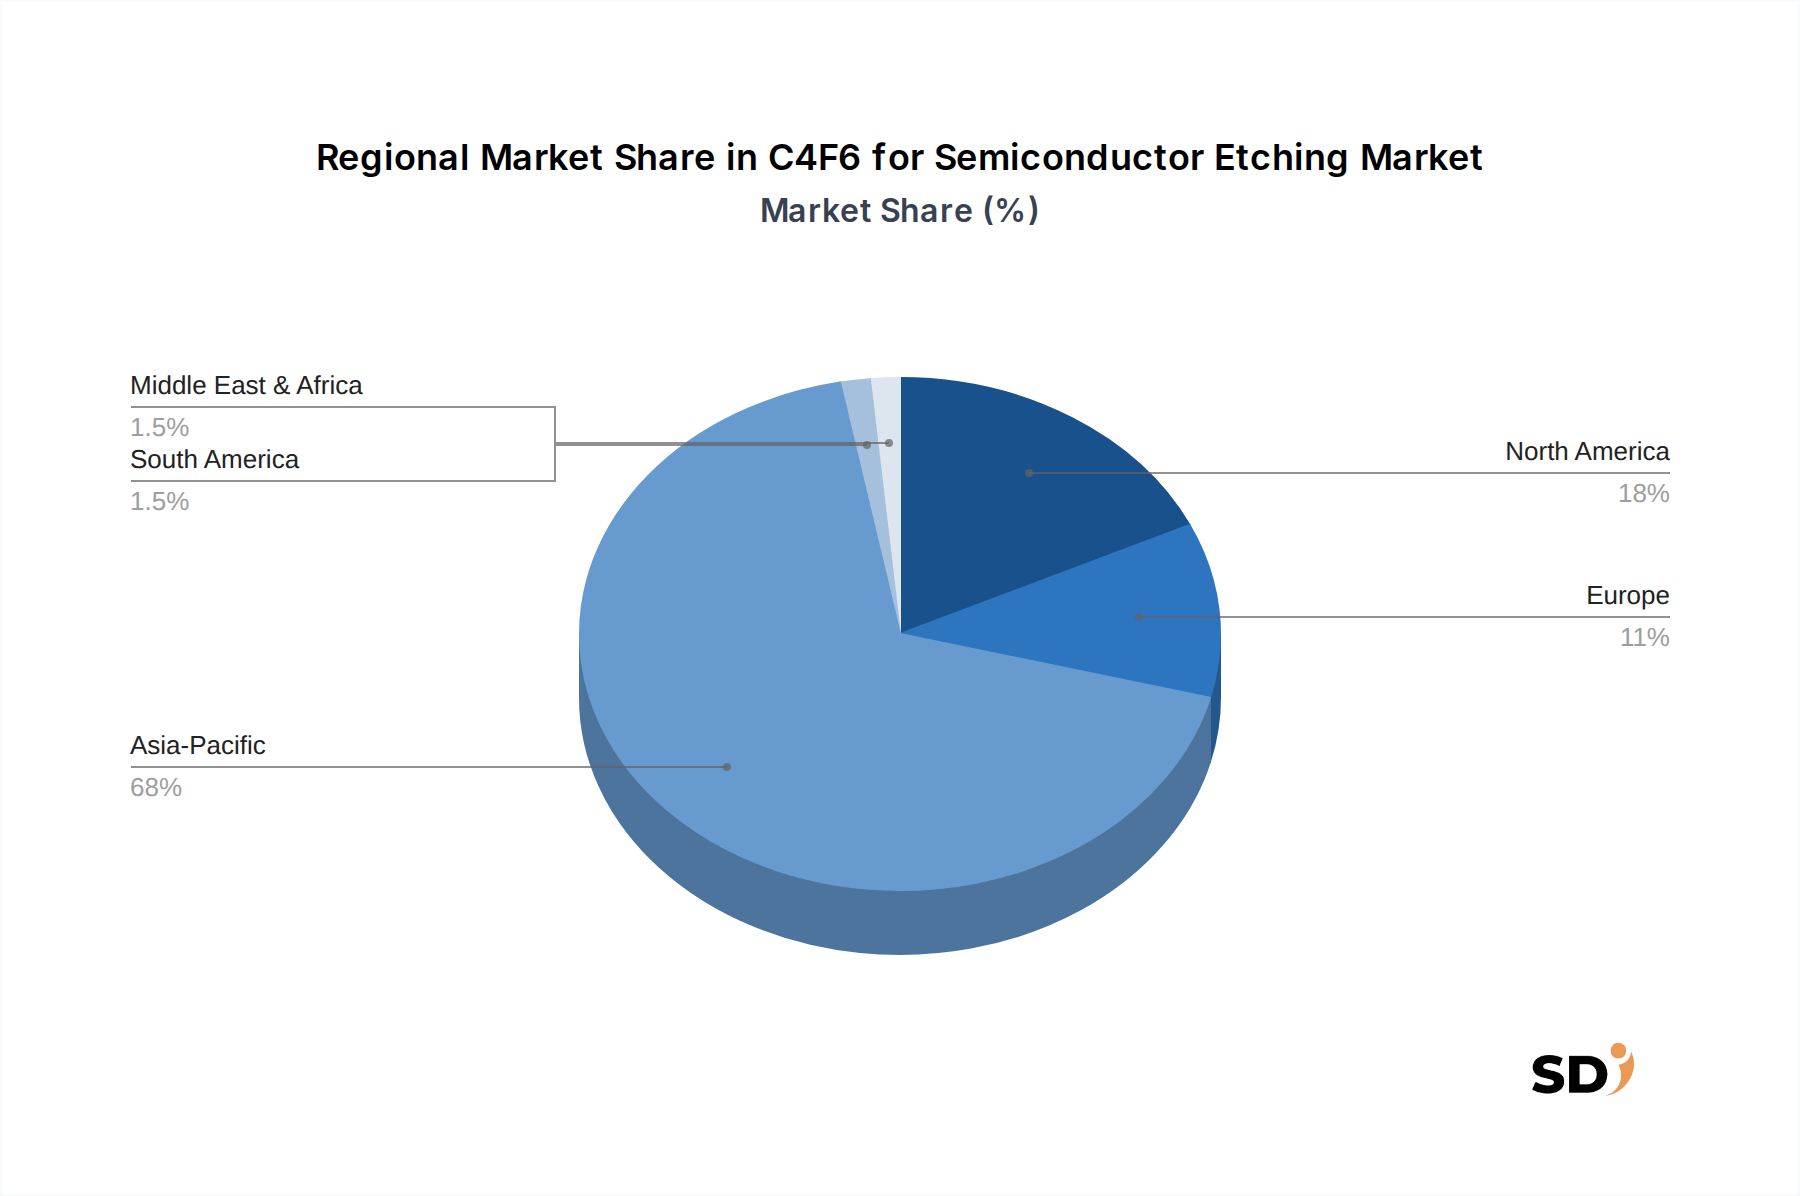
The C4F6 for Semiconductor Etching Market is profoundly influenced by a confluence of potent drivers and inherent constraints. A primary driver is the accelerating pace of semiconductor miniaturization and the adoption of advanced process nodes. The transition from 10nm to 7nm, 5nm, and even 3nm logic technologies, along with the increasing layers in 3D NAND memory, necessitates extremely precise and selective etching. C4F6 offers the unique plasma characteristics required for these sub-critical dimensions and high-aspect-ratio features, driving its demand. For instance, the growing complexity of 3D NAND structures, which now exceed 200 active layers, places unprecedented demands on the anisotropic etching capabilities provided by advanced fluorocarbon gases like C4F6. This technical imperative directly fuels the Etching Gases Market.
Another significant driver stems from the burgeoning demand for high-performance computing, AI accelerators, and data centers. These applications require increasingly powerful and energy-efficient chips, leading to higher wafer starts and greater material consumption, including C4F6. The rapid expansion of the Advanced Packaging Market also contributes, as advanced chip stacking and interconnect technologies often require new etching chemistries. However, the market faces considerable constraints. Foremost among these are environmental concerns associated with fluorocarbon gases. C4F6, like many other perfluorocompounds (PFCs), has a high global warming potential (GWP), leading to stringent regulations and industry pressure to reduce emissions or find alternatives. This poses a significant challenge for the Fluorocarbon Gases Market as a whole.
Furthermore, the high cost of manufacturing and purifying ultra-high purity C4F6 is a constraint, impacting the overall cost of ownership for semiconductor fabs. Supply chain volatility, exacerbated by geopolitical factors and increasing demand, can also disrupt the availability of key raw materials sourced from the Fluorine Chemicals Market. Finally, the emergence of alternative etching chemistries, such as C5F8 or C3F8, or even novel non-fluorinated plasma chemistries, presents a competitive threat. While C4F6 remains superior for many critical applications, ongoing R&D in these alternatives could potentially displace C4F6 in certain segments, compelling suppliers to continuously innovate and optimize their C4F6 offerings.