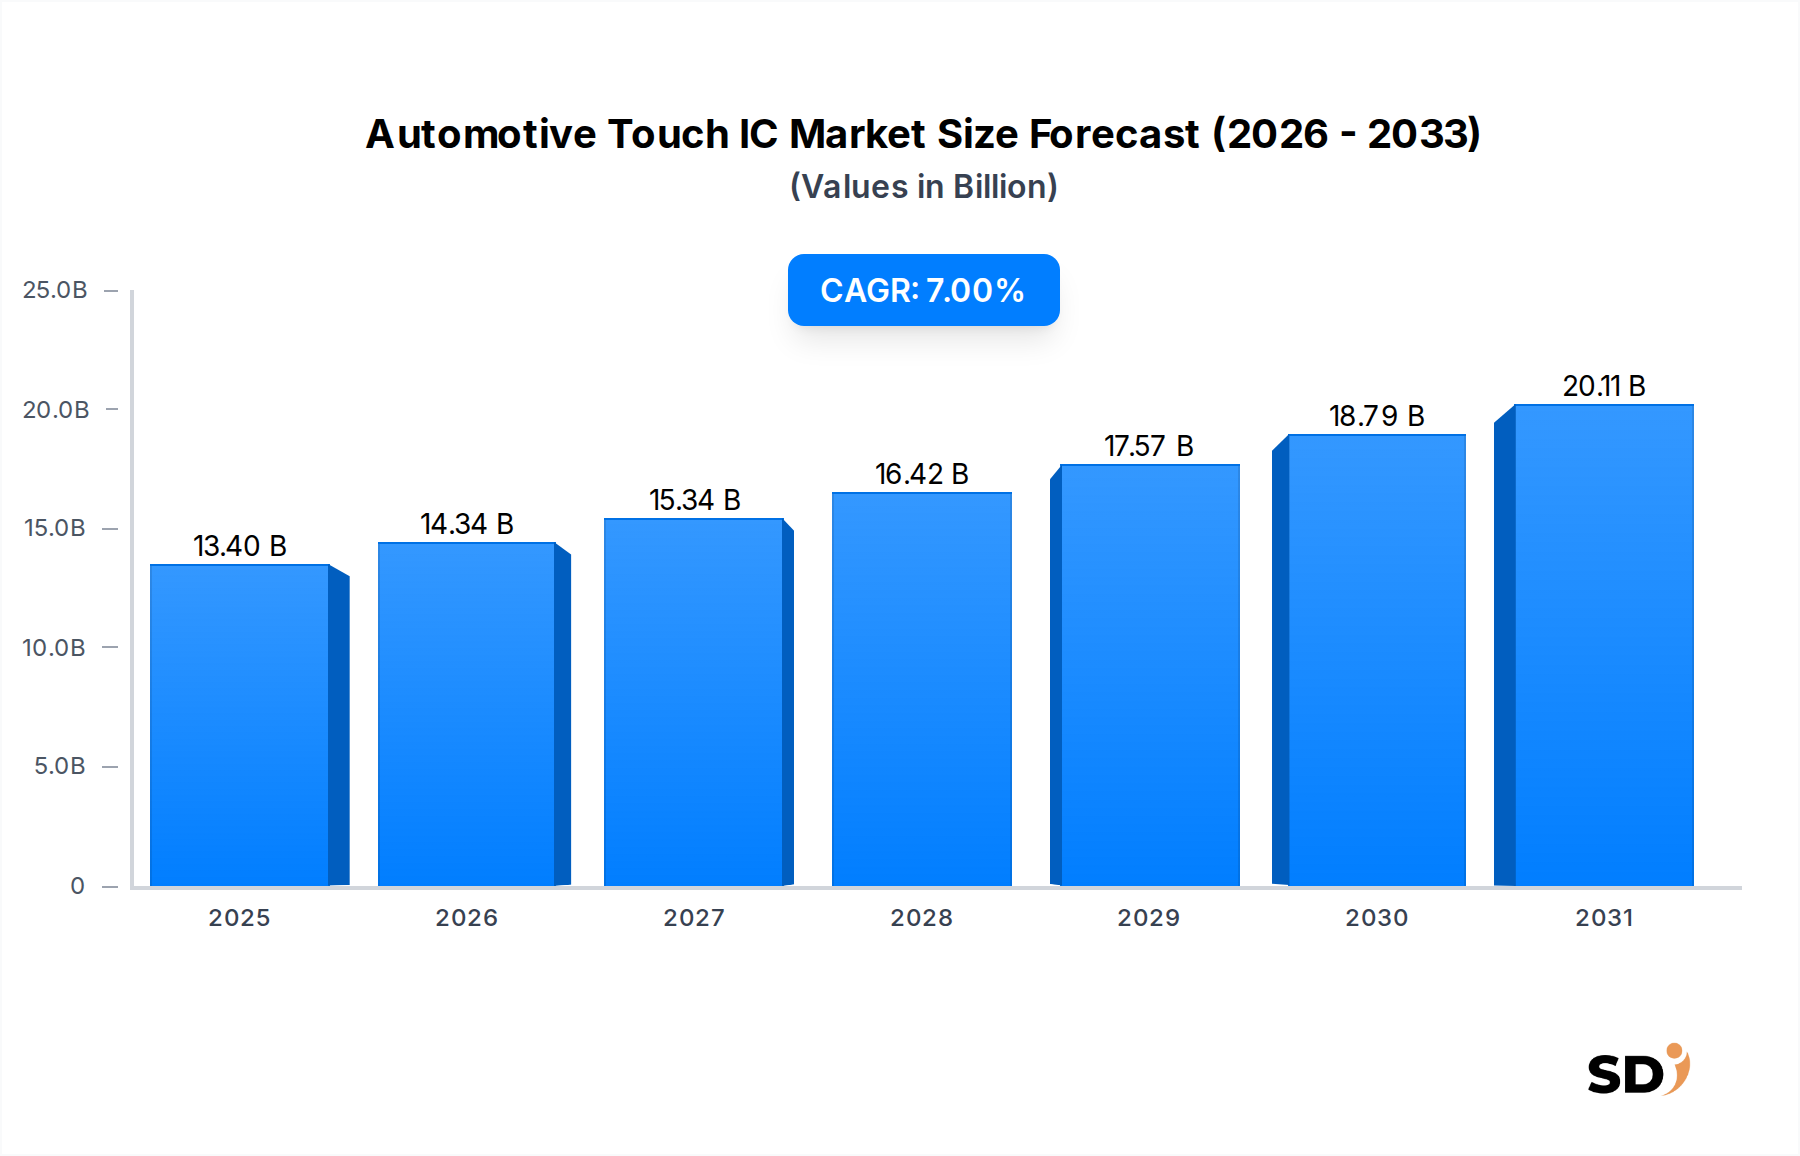
The Automotive Touch IC Market exhibits distinct regional dynamics, driven by varying automotive production capacities, technology adoption rates, and consumer preferences. While the market is global, certain regions are positioned as leaders in terms of revenue share and growth trajectory.
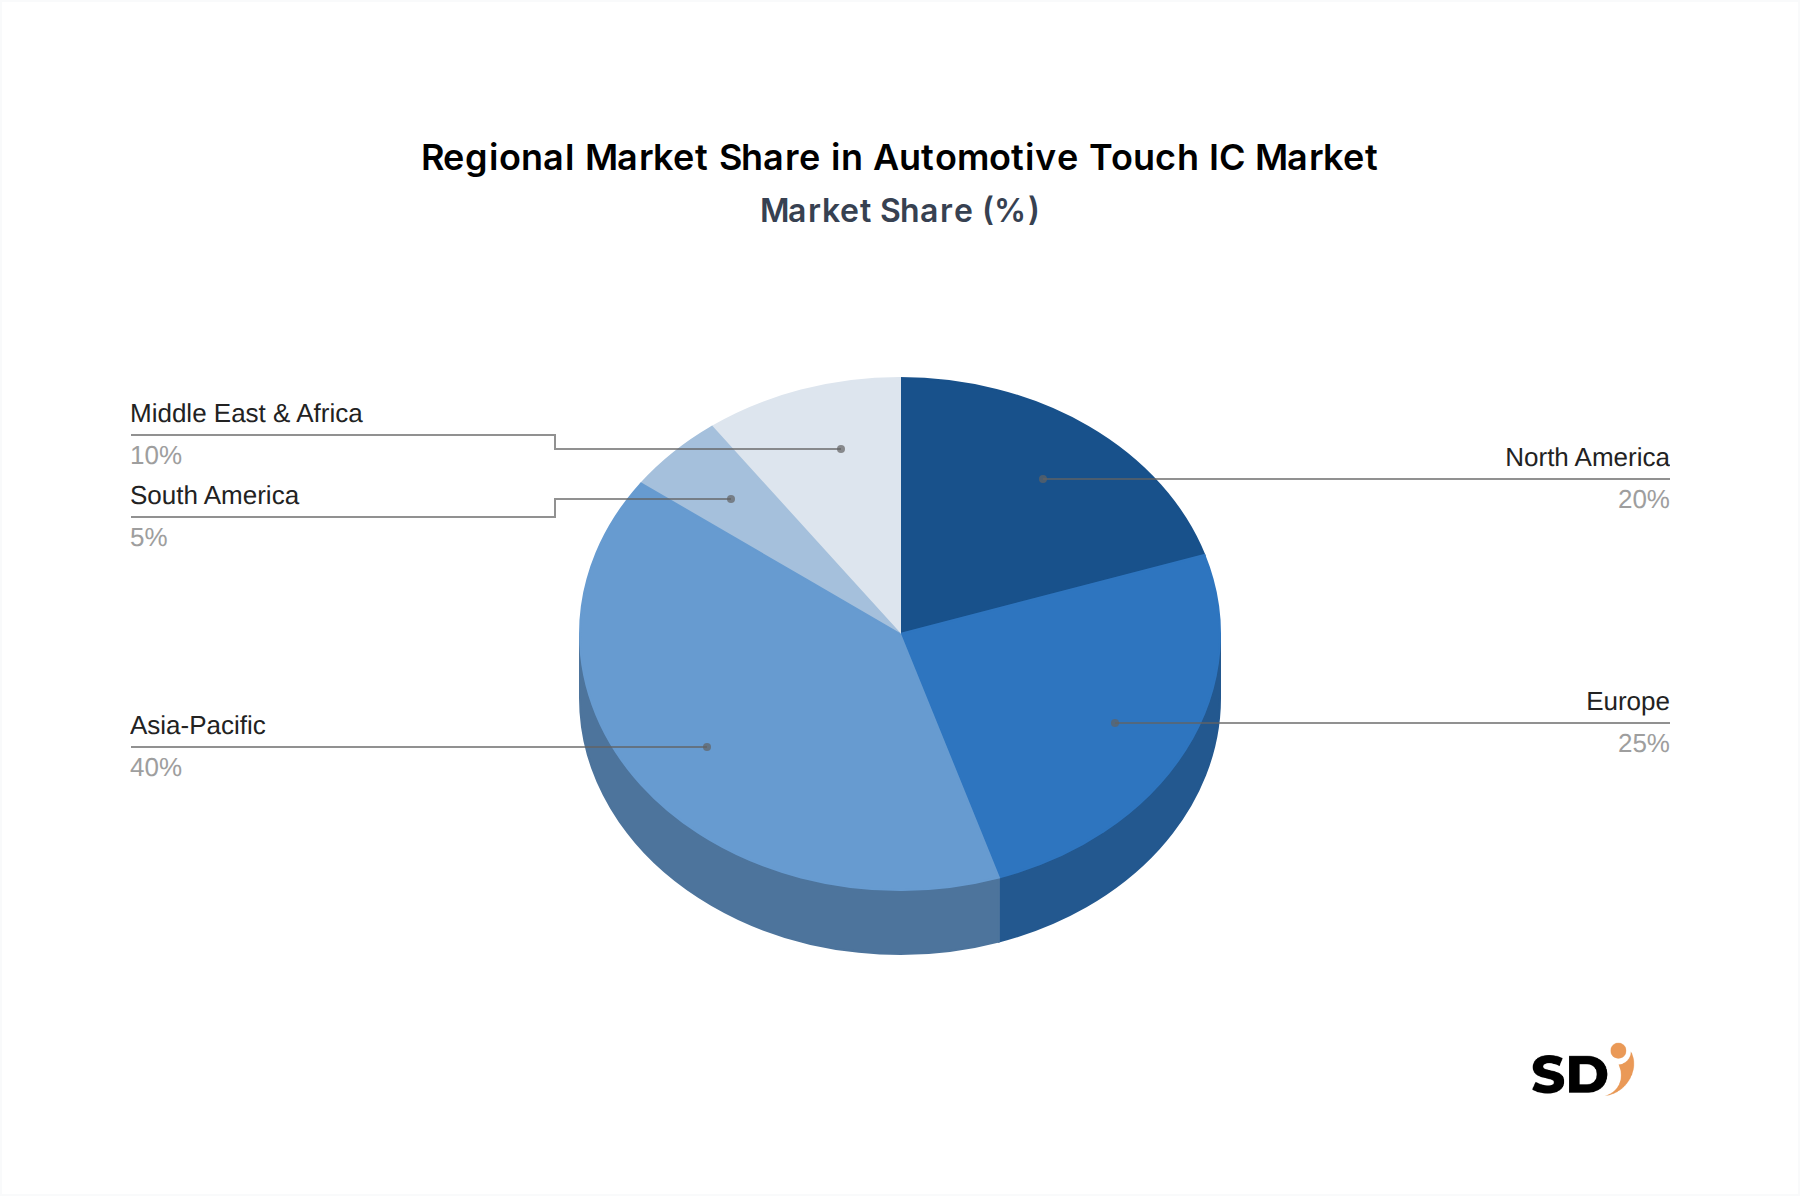
Asia Pacific currently holds the dominant revenue share, accounting for an estimated 40-45% of the global market in 2025. This region is also projected to be the fastest-growing segment, with a high CAGR estimated between 7.5-8.0% over the forecast period. The primary demand driver here is the robust automotive manufacturing base, particularly in countries like China, Japan, and South Korea, coupled with the rapid proliferation of electric vehicles and aggressive adoption of digital cockpits. The large volume of vehicle production and the consumer inclination towards feature-rich infotainment systems in these markets significantly boost the demand for advanced touch ICs.
Europe represents another substantial market, contributing an estimated 25-30% of the global revenue. The region is expected to demonstrate steady growth with a CAGR ranging from 6.0-6.5%. Demand is primarily fueled by the strong presence of premium and luxury automotive brands that prioritize sophisticated Human Machine Interface (HMI) systems and advanced driver assistance features. Stringent safety regulations and a focus on intuitive controls also drive innovation and adoption of high-performance touch solutions. Germany, France, and the UK are key contributors.
North America holds a significant market share, approximately 20-25%, with a healthy growth outlook at a CAGR of 6.5-7.0%. This region benefits from high technology adoption rates, increasing sales of connected and electric vehicles, and a strong consumer preference for large, interactive displays. The demand for advanced Automotive Infotainment Market solutions, seamlessly integrated with navigation and connectivity, is a major growth catalyst.
Middle East & Africa (MEA) and South America (SAM) collectively account for the remaining share, approximately 10-15%. While smaller in absolute terms, these regions are emerging and are expected to exhibit high growth rates, possibly exceeding 8.0% CAGR, driven by increasing disposable incomes, expanding automotive manufacturing capabilities, and a growing influx of technologically advanced vehicles. However, market maturity is lower, and infrastructure development continues to be a factor influencing adoption.