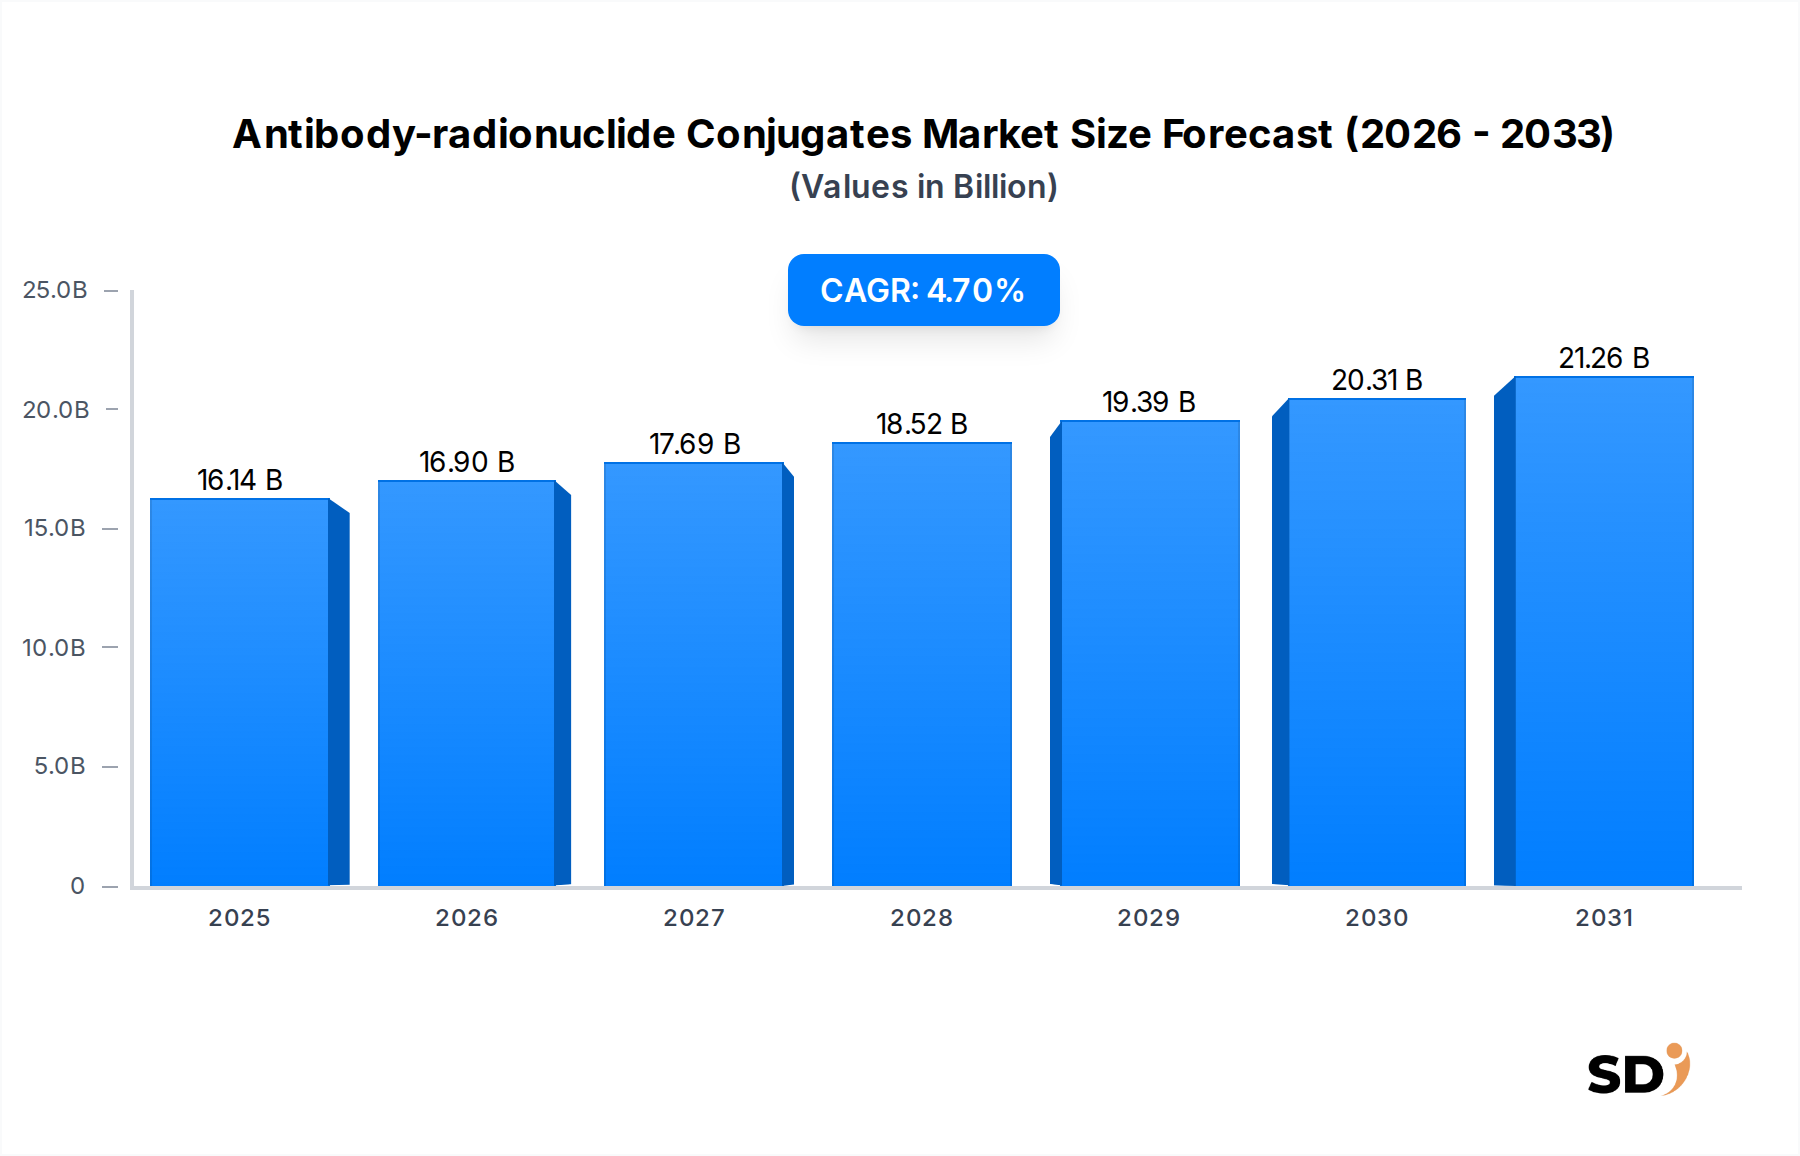
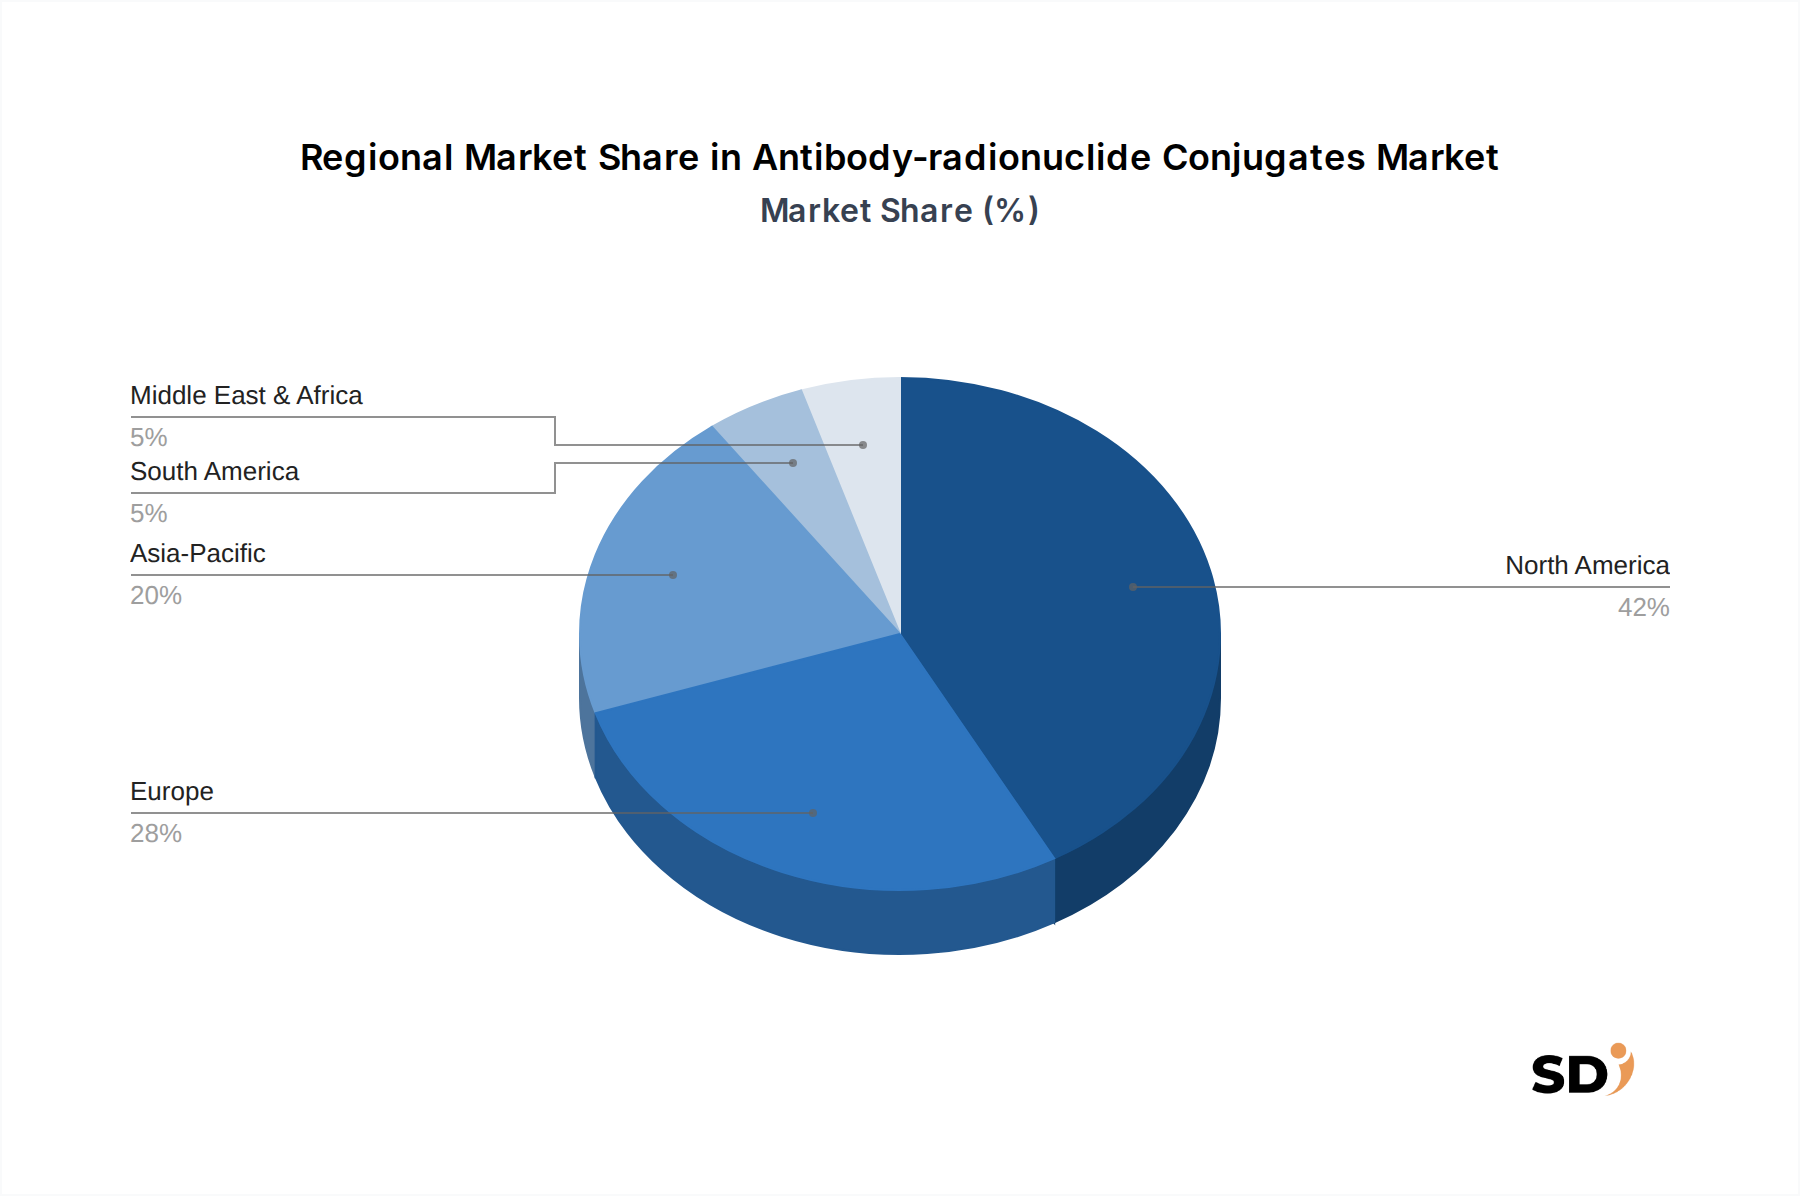
The Antibody-radionuclide Conjugates Market is influenced by a complex interplay of powerful growth drivers and significant constraining factors. A primary driver is the escalating global cancer burden. According to the World Health Organization, cancer incidence is projected to rise significantly in the coming decades, creating an urgent demand for advanced and more effective therapeutic solutions. This drives substantial investment into novel treatments like ARCs, which offer enhanced specificity and reduced systemic toxicity compared to conventional therapies. Furthermore, advancements in precision medicine and personalized oncology approaches are catalyzing market growth. ARCs inherently align with these trends by targeting specific biomarkers expressed by cancer cells, thereby improving therapeutic outcomes and minimizing off-target effects. This alignment is also evident in the robust growth observed in the Targeted Therapy Market, where ARCs represent a leading-edge modality.
Another significant driver is the continuous innovation in radiopharmaceutical research and development. This includes the discovery of new therapeutic radionuclides, the development of more stable and efficient linker technologies for conjugating antibodies to isotopes, and sophisticated imaging techniques that guide treatment. Increasing R&D expenditure by pharmaceutical and biotechnology companies, coupled with government funding for cancer research, is accelerating the development and clinical translation of next-generation ARCs. The expanding diagnostic utility of ARCs, particularly in imaging specific tumor types, also contributes to their adoption, often paving the way for subsequent therapeutic applications. The rising number of regulatory approvals for new ARCs, supported by favorable regulatory pathways for breakthrough therapies, further fuels market expansion.
Conversely, several constraints impede the Antibody-radionuclide Conjugates Market's full potential. The high development costs associated with ARCs, spanning from extensive preclinical research to lengthy and expensive clinical trials, represent a significant barrier to entry and market growth. The manufacturing complexities inherent in producing both the specific antibodies and the short-lived radionuclides, followed by their precise conjugation, pose substantial challenges. Supply chain vulnerabilities for critical medical isotopes, many of which are produced in a limited number of aging nuclear reactors globally, present a constant risk of shortages and price volatility. This concern is particularly acute for the Medical Isotopes Market, where disruptions can severely impact ARC production schedules. Additionally, the stringent regulatory requirements for handling, transporting, and administering radioactive materials contribute to operational complexities and higher costs. Limited awareness and specialized infrastructure in emerging economies also restrict broader adoption, highlighting the need for sustained education and investment to overcome these hurdles.