Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
Air Cooled Fuel Cell Stack Market Evolution & 2033 Growth
Air Cooled Fuel Cell Stack
Air Cooled Fuel Cell Stack Market Evolution & 2033 Growth
Air Cooled Fuel Cell Stack by Capacity (Low Power, Medium Power, High Power), by Fuel Cell Type (Proton Exchange Membrane Fuel Cells (PEMFC/PEFC), Solid Oxide Fuel Cells (SOFC), Phosphoric Acid Fuel Cells (PAFC), Alkaline Fuel Cells (AFC), Molten Carbonate Fuel Cells (MCFC), Others), by Component (Membrane Electrode Assembly (MEA), Bipolar Plates, Gas Diffusion Layer (GDL), End Plates & Tie Rods, Gaskets/Seals, Cooling Fans & Air Management Systems, Others), by Application (Portable Power Systems, Backup Power Systems, Stationary Power Generation, Material Handling Equipment, Unmanned Aerial Vehicles (UAVs), Others), by End User (Residential, Commercial, Industrial), by Power Output (Below 5 kW, 5 kW – 20 kW, 20 kW – 80 kW, 80 kW – 120 kW, 120 kW – 200 kW, Above 200 kW), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Jul 2, 2026|Base Year : 2025|Pages : 127
Key Insights into the Air Cooled Fuel Cell Stack Market
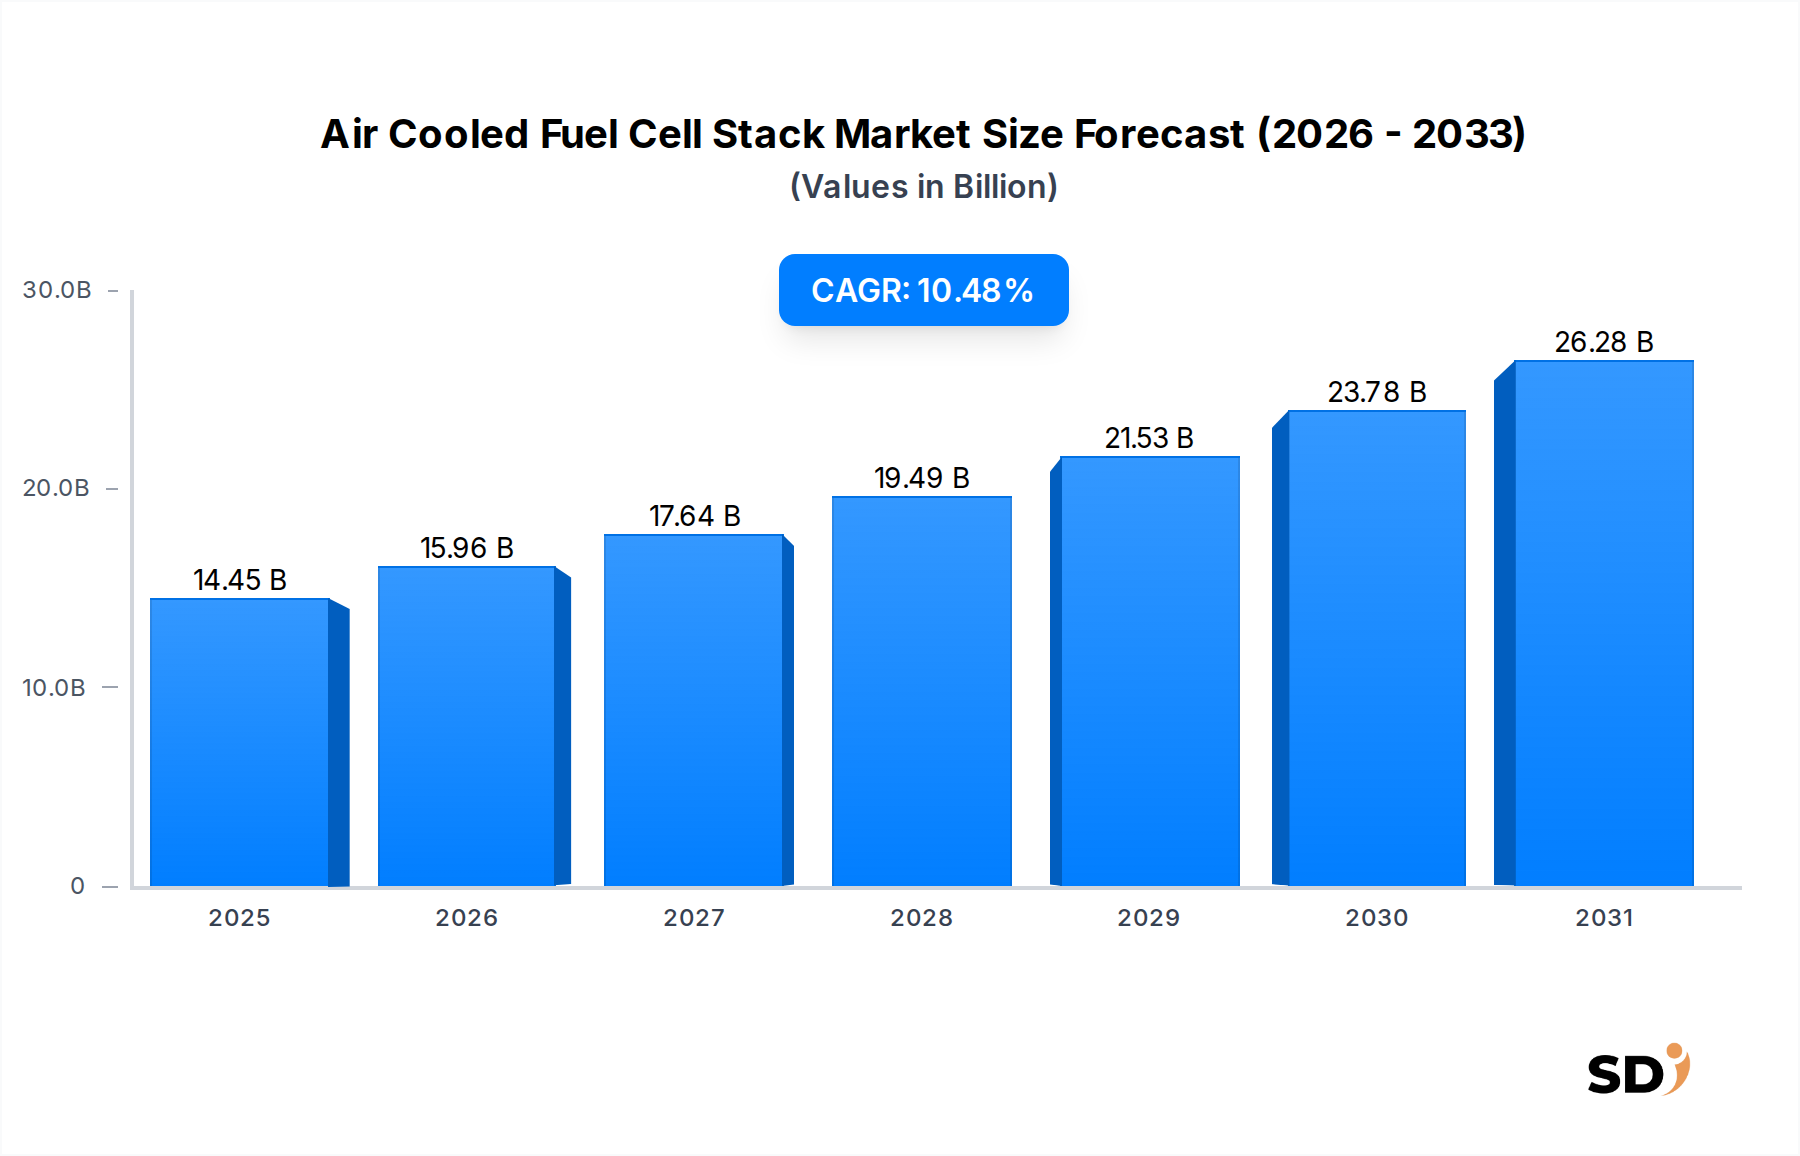
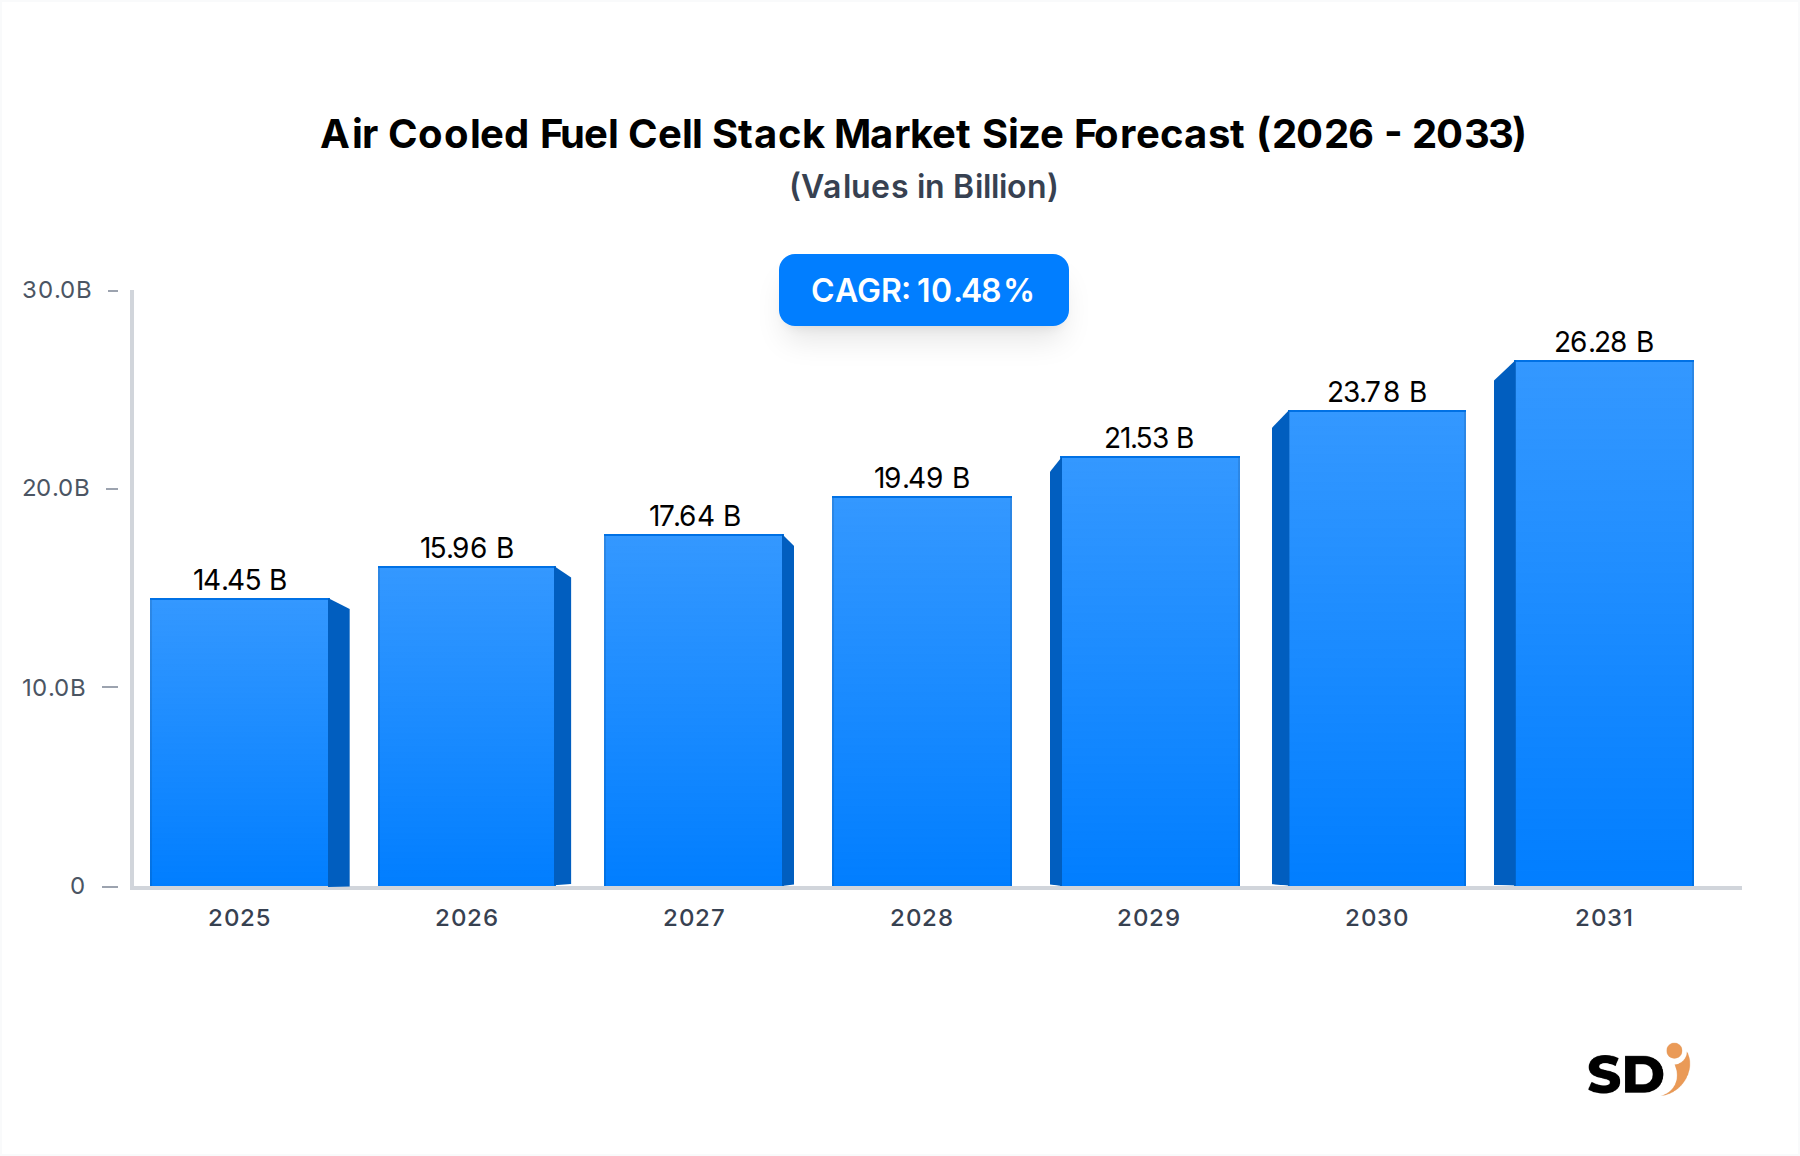
The Air Cooled Fuel Cell Stack Market is experiencing robust growth, primarily driven by the escalating demand for clean energy solutions across various applications. Valued at an estimated USD 14.45 billion in 2025, the market is projected to expand significantly, exhibiting a Compound Annual Growth Rate (CAGR) of 10.48% through the forecast period. This impressive growth trajectory is underpinned by the inherent advantages of air-cooled systems, such as their simplicity, reduced weight, and lower cost compared to liquid-cooled counterparts, making them ideal for specific power output ranges and applications. Key demand drivers include the increasing adoption of fuel cells in portable power systems, backup power solutions, and certain segments of the material handling equipment market. Furthermore, advancements in membrane electrode assembly (MEA) technology and bipolar plate materials are enhancing efficiency and durability, thereby accelerating market penetration.
Air Cooled Fuel Cell Stack Market Size (In Billion)
30.0B
20.0B
10.0B
0
14.45 B
2025
15.96 B
2026
17.64 B
2027
19.49 B
2028
21.53 B
2029
23.78 B
2030
26.28 B
2031
Macro tailwinds such as stringent environmental regulations promoting zero-emission technologies, government incentives for fuel cell deployment, and growing investments in hydrogen infrastructure are significantly propelling the Air Cooled Fuel Cell Stack Market. The shift towards electrification in various industries, coupled with the need for reliable and continuous power supply in remote or critical applications, further fuels this demand. The expanding Proton Exchange Membrane Fuel Cell Market, which frequently utilizes air-cooled stacks for lower power applications, is a direct beneficiary of these trends. Similarly, the burgeoning interest in the Hydrogen Fuel Cell Market across mobility and stationary power generation sectors provides a substantial growth impetus. While liquid-cooled systems dominate high-power applications, air-cooled stacks are finding their niche in less demanding environments, offering compelling value propositions. The outlook for the Air Cooled Fuel Cell Stack Market remains highly positive, with continuous innovation in materials science and manufacturing processes expected to further optimize performance and reduce costs, opening new application frontiers and consolidating its position within the broader Clean Energy Technologies Market. Strategic partnerships and R&D focused on stack miniaturization and power density improvements are anticipated to be critical factors shaping future market dynamics."
"
Portable Power Systems Segment in the Air Cooled Fuel Cell Stack Market
The Portable Power Systems segment stands as the dominant application in the Air Cooled Fuel Cell Stack Market, commanding a substantial revenue share due to its intrinsic alignment with the operational characteristics of air-cooled technology. Air-cooled fuel cell stacks offer significant advantages for portable devices, including simplified design, lighter weight, and reduced footprint, which are critical parameters for mobile and easily deployable power solutions. Their elimination of complex liquid cooling loops translates into lower manufacturing costs and enhanced reliability, making them highly attractive for applications ranging from consumer electronics to military field equipment and remote sensing devices. This segment's dominance is further solidified by the increasing demand for off-grid power, extended battery life, and rapid refueling capabilities that traditional battery technologies often struggle to meet.
Key players such as Intelligent Energy Limited and Horizon Fuel Cell Technologies have made significant strides in this segment, developing compact and robust air-cooled stacks specifically tailored for portable power systems. The flexibility of these stacks to operate efficiently over a range of temperatures without requiring auxiliary cooling systems also contributes to their suitability for diverse environmental conditions encountered in portable applications. While the Material Handling Equipment Market also utilizes fuel cells, the specific design advantages of air-cooled stacks are most pronounced in the lower power output ranges typically associated with portable power. This trend is further supported by the growing market for Unmanned Aerial Vehicles (UAVs) which benefit immensely from the high energy density and silent operation offered by air-cooled fuel cells, providing significantly longer flight times compared to battery-powered alternatives.
The dominance of the Portable Power Systems segment is expected to continue, albeit with potential shifts in sub-segment composition as new applications emerge. While its revenue share is substantial, the segment is also characterized by intense competition and a continuous drive for miniaturization and cost reduction. Innovations in the Membrane Electrode Assembly Market, particularly those leading to higher power densities at ambient temperatures, directly benefit this segment. The ongoing evolution of the Proton Exchange Membrane Fuel Cell Market, which forms the core technology for most air-cooled stacks, will further reinforce the segment's growth. The emphasis on ruggedization and ease of integration will remain pivotal for players aiming to capture a larger share within this dynamic and evolving landscape of the Air Cooled Fuel Cell Stack Market, ensuring its continued leadership in the foreseeable future."
"
Key Market Drivers and Constraints in the Air Cooled Fuel Cell Stack Market
The Air Cooled Fuel Cell Stack Market is profoundly influenced by a confluence of drivers and constraints that shape its growth trajectory. A primary driver is the accelerating global imperative for decarbonization, which mandates a shift towards zero-emission energy solutions. This is quantified by international agreements and national policies targeting significant reductions in greenhouse gas emissions, driving increased investment in technologies like air-cooled fuel cells, particularly in the Hydrogen Fuel Cell Market. For instance, the European Union's target of reducing net greenhouse gas emissions by at least 55% by 2030 relative to 1990 levels directly promotes the adoption of such clean energy alternatives.
Another significant driver is the increasing demand for portable and backup power systems across various sectors. The reliance on uninterrupted power supply for critical infrastructure and remote operations, coupled with the limitations of conventional battery technologies in terms of energy density and recharge time, positions air-cooled fuel cells as an attractive alternative. This is evident in the robust growth observed in the Portable Power Systems Market and the Material Handling Equipment Market, where fuel cells offer extended operating times and rapid refueling, leading to improved productivity and operational efficiency.
However, several constraints temper the market's growth. The most prominent is the relatively higher upfront cost of fuel cell systems compared to established power generation technologies, such as internal combustion engines or even advanced battery systems. While operational costs may be lower over the long term, the initial capital expenditure remains a significant barrier for many potential end-users. Furthermore, the limited hydrogen refueling infrastructure, especially outside of specific industrial corridors or research hubs, restricts broader adoption. Despite efforts to expand the Hydrogen Fuel Cell Market, the current infrastructure density is insufficient to support widespread deployment in consumer and general commercial applications. Another constraint includes the durability and lifetime of certain stack components, notably in the Membrane Electrode Assembly Market, which require continuous research and development to meet the longevity expectations of industrial and automotive applications. These factors collectively create a nuanced environment for growth within the Air Cooled Fuel Cell Stack Market, necessitating strategic innovation and supportive policy frameworks to overcome the prevailing hurdles."
"
Competitive Ecosystem of Air Cooled Fuel Cell Stack Market
The competitive landscape of the Air Cooled Fuel Cell Stack Market is characterized by a mix of established energy solution providers, specialized fuel cell manufacturers, and emerging technology innovators. These companies are focused on enhancing power density, reducing costs, and expanding application versatility:
Ballard Power Systems: A leading global provider of clean energy fuel cell solutions, Ballard is known for its durable and high-performance PEM fuel cell products, targeting various applications from heavy-duty motive power to stationary power generation, often leveraging its stack technology in different cooling configurations.
Plug Power Inc.: A key player in the hydrogen economy, Plug Power specializes in end-to-end hydrogen fuel cell solutions, particularly for material handling equipment and electric fleet vehicles, where its GenDrive units often incorporate advanced stack designs for efficiency and reliability.
Intelligent Energy Limited: Renowned for its lightweight and high-power-density fuel cell stacks, Intelligent Energy focuses on applications requiring compact and efficient power, including automotive, UAVs, and portable power systems, where air-cooling offers significant advantages.
PowerCell Sweden AB: A developer and manufacturer of fuel cell stacks and systems for vehicle, marine, and stationary applications, PowerCell is known for its compact and robust designs, often contributing to the broader Hydrogen Fuel Cell Market with diverse cooling solutions.
SFC Energy AG: Specializing in direct methanol fuel cells (DMFC) and hydrogen fuel cells, SFC Energy provides clean power solutions for stationary, mobile, and portable applications, emphasizing long-term autonomy and reliability for off-grid power requirements.
Horizon Fuel Cell Technologies: A global leader in fuel cell educational products and light-duty fuel cell applications, Horizon focuses on making hydrogen and fuel cell technology accessible and applicable across various small-scale power demands, including portable power systems.
Doosan Fuel Cell Co., Ltd.: Primarily known for its stationary fuel cell power plants, Doosan also contributes to the broader fuel cell industry with diverse stack technologies, aiming to provide reliable and efficient power generation solutions.
ElringKlinger AG: A major automotive supplier, ElringKlinger focuses on developing and producing high-performance components for fuel cells, including bipolar plates and sealing systems, which are crucial for enhancing the efficiency and longevity of both air- and liquid-cooled stacks.
Nedstack Fuel Cell Technology B.V.: A specialist in large PEM fuel cell solutions for mission-critical applications such as telecom backup power and maritime, Nedstack focuses on high-power and long-lifetime stacks, contributing to the industrial segment of the Air Cooled Fuel Cell Stack Market.
Ceres Power Holdings plc: Known for its SteelCell® solid oxide fuel cell (SOFC) technology, Ceres Power licenses its proprietary technology to global manufacturers, enabling highly efficient and flexible power generation for various applications, including potentially air-cooled systems in specific configurations, thereby impacting the Solid Oxide Fuel Cell Market."
"
Recent Developments & Milestones in the Air Cooled Fuel Cell Stack Market
January 2024: Intelligent Energy announced a new generation of its lightweight 800W fuel cell stack for drone applications, improving power-to-weight ratio and operational efficiency, directly impacting the Portable Power Systems Market within the Air Cooled Fuel Cell Stack Market.
November 2023: SFC Energy AG introduced new EFOY H-series hydrogen fuel cells designed for enhanced performance in extreme conditions, expanding their portable and stationary power offerings and strengthening their position in critical infrastructure backup.
September 2023: Ballard Power Systems unveiled plans to expand its manufacturing capabilities for fuel cell components, including membrane electrode assemblies and bipolar plates, to meet the growing demand in the Automotive Fuel Cell Market and other sectors.
July 2023: Plug Power Inc. announced several new partnerships for the deployment of green hydrogen and fuel cell solutions in material handling operations across Europe, further solidifying its presence in the Material Handling Equipment Market.
April 2023: Horizon Fuel Cell Technologies launched a new line of compact, air-cooled hydrogen fuel cell generators aimed at the recreational vehicle and outdoor power market, emphasizing quiet operation and extended runtime over traditional generators.
February 2023: PowerCell Sweden AB successfully completed a testing program for its fuel cell stack technology in maritime applications, demonstrating its robustness and readiness for broader commercialization within demanding industrial environments.
December 2022: ElringKlinger AG invested in a new production facility for metallic bipolar plates, aiming to scale up production and reduce costs for a critical component across various fuel cell types, including those used in the Air Cooled Fuel Cell Stack Market.
October 2022: Ceres Power Holdings plc deepened its collaboration with Bosch on the development of Solid Oxide Fuel Cell Market systems, expanding the application scope for high-efficiency stationary power generation."
"
Regional Market Breakdown for Air Cooled Fuel Cell Stack Market
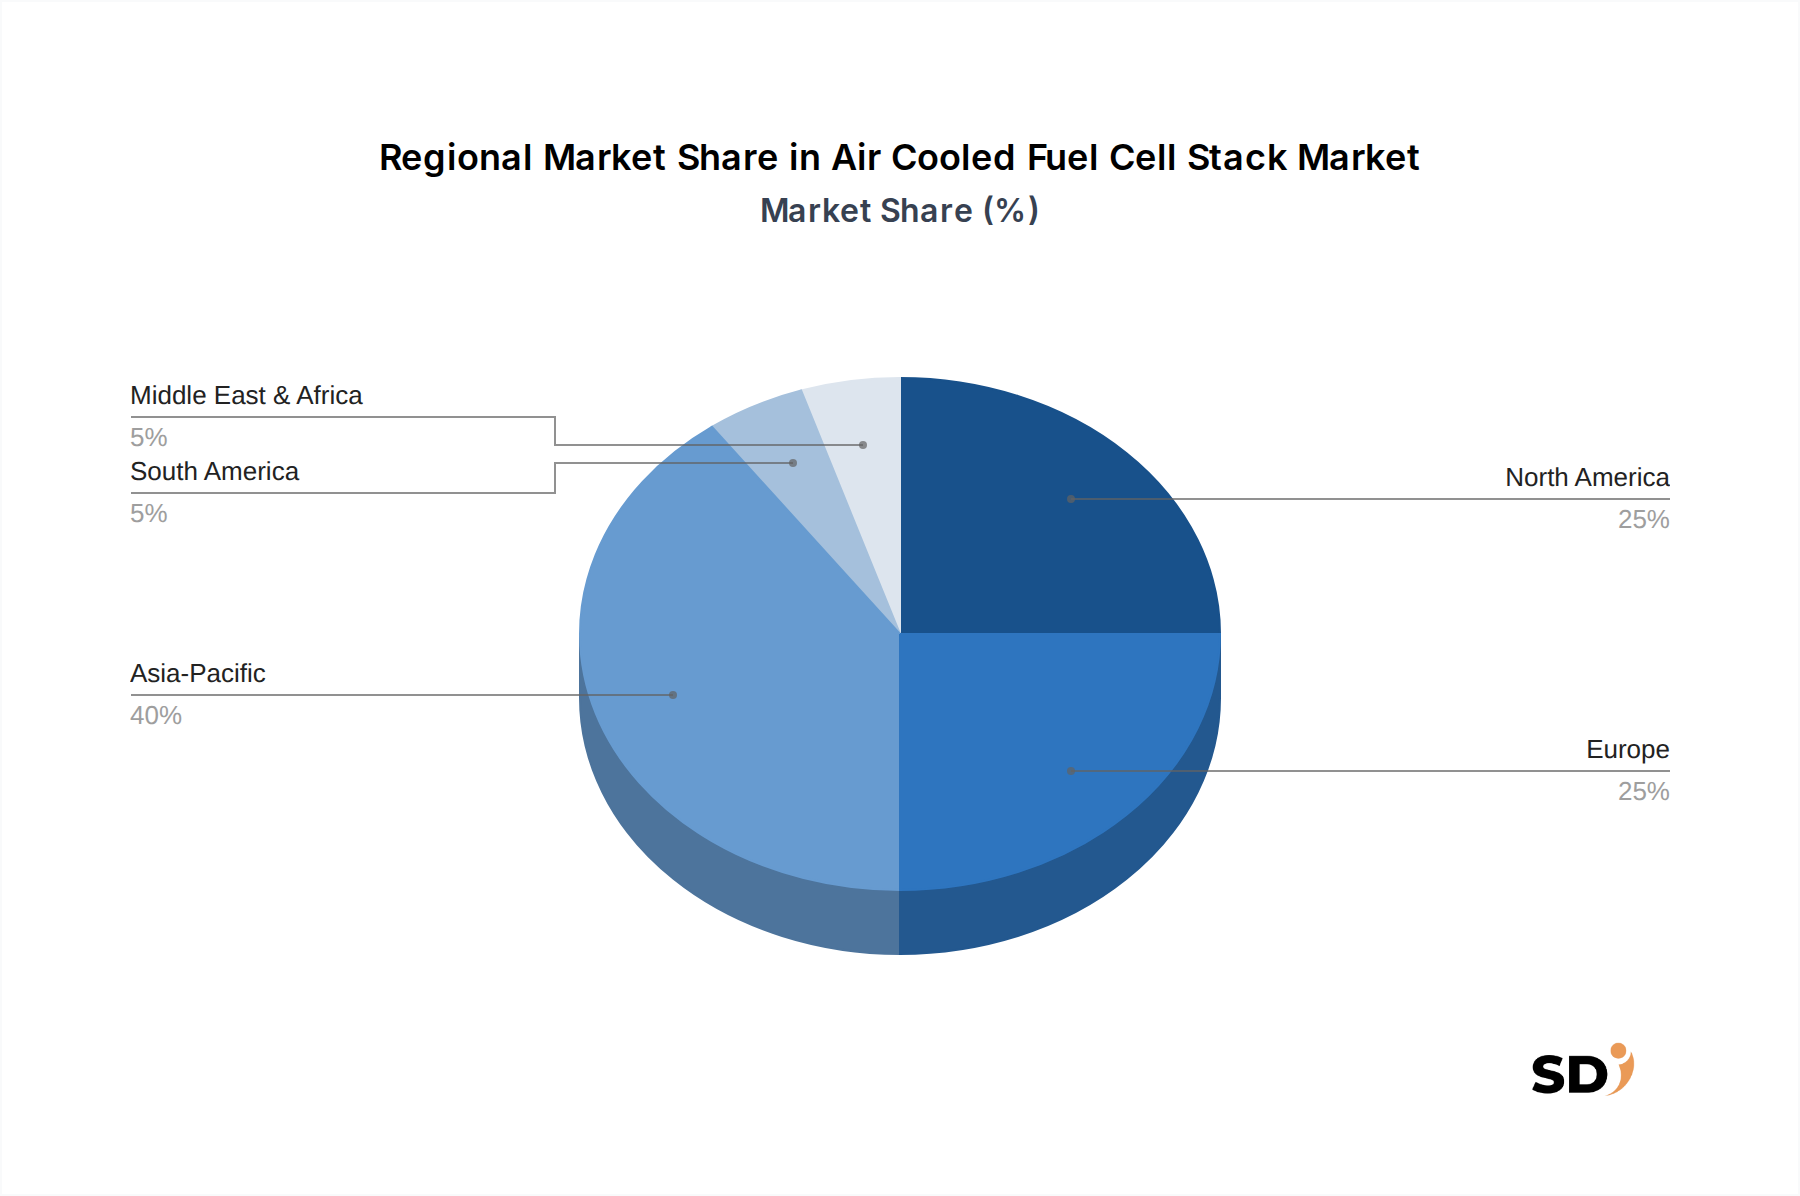
The Air Cooled Fuel Cell Stack Market demonstrates varied growth dynamics and adoption patterns across key global regions. Asia Pacific is currently the largest and fastest-growing region, projected to exhibit a CAGR exceeding 12.5% during the forecast period. This dominance is attributed to robust industrialization, significant investments in renewable energy infrastructure, and government initiatives promoting hydrogen fuel cell technology in countries like China, Japan, and South Korea. The region is a hub for electronics manufacturing and portable device markets, driving the demand for compact, air-cooled power solutions, particularly in the Portable Power Systems Market and light-duty material handling. Increased adoption of electric vehicles and focus on sustainable mobility also underpins the growth of the Automotive Fuel Cell Market within the region.
Europe represents a mature yet dynamic market, expected to maintain a CAGR of approximately 9.8%. The region benefits from strong regulatory support for decarbonization, ambitious hydrogen strategies, and a well-established automotive sector transitioning to cleaner technologies. Countries like Germany and the UK are at the forefront of fuel cell research and commercialization, with significant uptake in backup power and specialized industrial applications. The focus on developing the overall Hydrogen Fuel Cell Market and the Clean Energy Technologies Market is a primary demand driver, alongside strategic investments in expanding refueling infrastructure.
North America, with an anticipated CAGR of around 9.0%, is a significant market, primarily driven by early adoption in the Material Handling Equipment Market (e.g., forklifts in warehouses) and increasing interest in drone technology and portable electronics. Government incentives and corporate commitments to sustainability are bolstering demand, particularly in the United States and Canada. The strong presence of research institutions and technology innovators also contributes to market expansion and product development in the Membrane Electrode Assembly Market.
Middle East & Africa and South America are emerging regions in the Air Cooled Fuel Cell Stack Market, albeit from a lower base, exhibiting CAGRs between 7.5% and 8.5%. Growth in these regions is primarily spurred by the need for reliable off-grid power solutions in remote areas, increasing energy independence, and the nascent adoption of fuel cells in industrial applications. While still in early stages, increasing awareness and foreign direct investment in clean energy projects are expected to accelerate market penetration in the coming years."
"
Pricing Dynamics & Margin Pressure in Air Cooled Fuel Cell Stack Market
The pricing dynamics within the Air Cooled Fuel Cell Stack Market are influenced by a delicate balance of technological maturity, manufacturing scale, and competitive intensity. Average selling prices (ASPs) for air-cooled stacks have shown a gradual downward trend over the past few years, largely due to advancements in manufacturing processes, economies of scale, and increased competition. For low-power portable applications (e.g., sub-5 kW), stacks can range from USD 500 to USD 3,000, while medium-power systems (e.g., 5 kW – 20 kW) used in material handling or backup power may range from USD 5,000 to USD 20,000. High-power variants, though less common for purely air-cooled, would command significantly higher prices. This trend is expected to continue as component costs, particularly those associated with the Membrane Electrode Assembly Market and bipolar plates, decline due to innovation and higher production volumes.
Margin structures across the value chain are currently under pressure. Upstream component suppliers, especially those dealing with platinum group metals (PGMs) for catalysts, face volatility in raw material prices. Midstream stack manufacturers contend with the need for significant R&D investment to improve power density and durability, alongside the constant push for cost reduction from OEMs. Downstream system integrators face competitive pricing from alternative power solutions. Key cost levers include the cost of platinum loading in MEAs, the manufacturing complexity of bipolar plates, and the efficiency of cooling fans and air management systems. While the Air Cooled Fuel Cell Stack Market offers inherent cost advantages over liquid-cooled systems by eliminating pumps, radiators, and associated plumbing, the overall system cost (including balance-of-plant components) remains a critical hurdle for broader market adoption, particularly when competing with mature battery technologies or conventional generators. Strategic sourcing, vertical integration, and aggressive automation in manufacturing are crucial for maintaining healthy margins. The increasing scale of the Hydrogen Fuel Cell Market generally contributes to cost reductions across the supply chain, benefiting air-cooled variants as well."
"
Supply Chain & Raw Material Dynamics for Air Cooled Fuel Cell Stack Market
The supply chain for the Air Cooled Fuel Cell Stack Market is complex and multifaceted, with critical upstream dependencies that influence cost and availability. Key inputs include platinum group metals (PGMs) for catalysts, specialized polymers for membranes in the Proton Exchange Membrane Fuel Cell Market, graphite or stainless steel for bipolar plates, and various polymers and composites for gaskets and end plates. The price volatility of PGMs, particularly platinum, which is a significant component in the Membrane Electrode Assembly Market, poses a substantial sourcing risk. Geopolitical factors and mining output fluctuations can lead to significant price swings, directly impacting the manufacturing cost of the stacks.
Other critical raw materials include carbon paper or cloth for gas diffusion layers (GDLs) and high-performance engineering plastics for various structural components. The production of these materials requires specialized manufacturing processes and expertise, creating a concentrated supplier base for certain components. For instance, the quality and cost-effectiveness of bipolar plates are pivotal, with materials like graphite composite or metallic alloys dominating. Supply chain disruptions, as witnessed during global events, can lead to delays in component delivery and increased logistical costs, impacting production schedules and profitability across the Air Cooled Fuel Cell Stack Market.
Manufacturers are increasingly focusing on diversification of their raw material sourcing and the development of alternative, lower-cost materials to mitigate these risks. Efforts to reduce platinum loading, recycle PGMs, and develop non-PGM catalysts are ongoing research areas aimed at enhancing supply chain resilience and reducing reliance on volatile commodities. The price trend for platinum has historically been cyclical, with recent periods showing some stability but always susceptible to demand shifts from automotive catalytic converters and investment. The increasing scale of the overall Hydrogen Fuel Cell Market and the Clean Energy Technologies Market is expected to drive more robust and localized supply chains over time, but upstream dependencies remain a critical consideration for the sustained growth and cost competitiveness of air-cooled fuel cell stacks.
10.3. Market Analysis, Insights and Forecast - by Component
10.3.1. Membrane Electrode Assembly (MEA)
10.3.2. Bipolar Plates
10.3.3. Gas Diffusion Layer (GDL)
10.3.4. End Plates & Tie Rods
10.3.5. Gaskets/Seals
10.3.6. Cooling Fans & Air Management Systems
10.3.7. Others
10.4. Market Analysis, Insights and Forecast - by Application
10.4.1. Portable Power Systems
10.4.2. Backup Power Systems
10.4.3. Stationary Power Generation
10.4.4. Material Handling Equipment
10.4.5. Unmanned Aerial Vehicles (UAVs)
10.4.6. Others
10.5. Market Analysis, Insights and Forecast - by End User
10.5.1. Residential
10.5.2. Commercial
10.5.3. Industrial
10.6. Market Analysis, Insights and Forecast - by Power Output
10.6.1. Below 5 kW
10.6.2. 5 kW – 20 kW
10.6.3. 20 kW – 80 kW
10.6.4. 80 kW – 120 kW
10.6.5. 120 kW – 200 kW
10.6.6. Above 200 kW
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Ballard Power Systems
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Plug Power Inc.
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Intelligent Energy Limited
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. PowerCell Sweden AB
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. SFC Energy AG
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Horizon Fuel Cell Technologies
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Doosan Fuel Cell Co. Ltd.
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. ElringKlinger AG
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Nedstack Fuel Cell Technology B.V.
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Ceres Power Holdings plc
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Others
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Air Cooled Fuel Cell Stack Revenue Breakdown (billion, %) by Region 2026 & 2034
Figure 2: North America Air Cooled Fuel Cell Stack Revenue (billion), by Capacity 2026 & 2034
Figure 3: North America Air Cooled Fuel Cell Stack Revenue Share (%), by Capacity 2026 & 2034
Figure 4: North America Air Cooled Fuel Cell Stack Revenue (billion), by Fuel Cell Type 2026 & 2034
Figure 5: North America Air Cooled Fuel Cell Stack Revenue Share (%), by Fuel Cell Type 2026 & 2034
Figure 6: North America Air Cooled Fuel Cell Stack Revenue (billion), by Component 2026 & 2034
Figure 7: North America Air Cooled Fuel Cell Stack Revenue Share (%), by Component 2026 & 2034
Figure 8: North America Air Cooled Fuel Cell Stack Revenue (billion), by Application 2026 & 2034
Figure 9: North America Air Cooled Fuel Cell Stack Revenue Share (%), by Application 2026 & 2034
Figure 10: North America Air Cooled Fuel Cell Stack Revenue (billion), by End User 2026 & 2034
Figure 11: North America Air Cooled Fuel Cell Stack Revenue Share (%), by End User 2026 & 2034
Figure 12: North America Air Cooled Fuel Cell Stack Revenue (billion), by Power Output 2026 & 2034
Figure 13: North America Air Cooled Fuel Cell Stack Revenue Share (%), by Power Output 2026 & 2034
Figure 14: North America Air Cooled Fuel Cell Stack Revenue (billion), by Country 2026 & 2034
Figure 15: North America Air Cooled Fuel Cell Stack Revenue Share (%), by Country 2026 & 2034
Figure 16: South America Air Cooled Fuel Cell Stack Revenue (billion), by Capacity 2026 & 2034
Figure 17: South America Air Cooled Fuel Cell Stack Revenue Share (%), by Capacity 2026 & 2034
Figure 18: South America Air Cooled Fuel Cell Stack Revenue (billion), by Fuel Cell Type 2026 & 2034
Figure 19: South America Air Cooled Fuel Cell Stack Revenue Share (%), by Fuel Cell Type 2026 & 2034
Figure 20: South America Air Cooled Fuel Cell Stack Revenue (billion), by Component 2026 & 2034
Figure 21: South America Air Cooled Fuel Cell Stack Revenue Share (%), by Component 2026 & 2034
Figure 22: South America Air Cooled Fuel Cell Stack Revenue (billion), by Application 2026 & 2034
Figure 23: South America Air Cooled Fuel Cell Stack Revenue Share (%), by Application 2026 & 2034
Figure 24: South America Air Cooled Fuel Cell Stack Revenue (billion), by End User 2026 & 2034
Figure 25: South America Air Cooled Fuel Cell Stack Revenue Share (%), by End User 2026 & 2034
Figure 26: South America Air Cooled Fuel Cell Stack Revenue (billion), by Power Output 2026 & 2034
Figure 27: South America Air Cooled Fuel Cell Stack Revenue Share (%), by Power Output 2026 & 2034
Figure 28: South America Air Cooled Fuel Cell Stack Revenue (billion), by Country 2026 & 2034
Figure 29: South America Air Cooled Fuel Cell Stack Revenue Share (%), by Country 2026 & 2034
Figure 30: Europe Air Cooled Fuel Cell Stack Revenue (billion), by Capacity 2026 & 2034
Figure 31: Europe Air Cooled Fuel Cell Stack Revenue Share (%), by Capacity 2026 & 2034
Figure 32: Europe Air Cooled Fuel Cell Stack Revenue (billion), by Fuel Cell Type 2026 & 2034
Figure 33: Europe Air Cooled Fuel Cell Stack Revenue Share (%), by Fuel Cell Type 2026 & 2034
Figure 34: Europe Air Cooled Fuel Cell Stack Revenue (billion), by Component 2026 & 2034
Figure 35: Europe Air Cooled Fuel Cell Stack Revenue Share (%), by Component 2026 & 2034
Figure 36: Europe Air Cooled Fuel Cell Stack Revenue (billion), by Application 2026 & 2034
Figure 37: Europe Air Cooled Fuel Cell Stack Revenue Share (%), by Application 2026 & 2034
Figure 38: Europe Air Cooled Fuel Cell Stack Revenue (billion), by End User 2026 & 2034
Figure 39: Europe Air Cooled Fuel Cell Stack Revenue Share (%), by End User 2026 & 2034
Figure 40: Europe Air Cooled Fuel Cell Stack Revenue (billion), by Power Output 2026 & 2034
Figure 41: Europe Air Cooled Fuel Cell Stack Revenue Share (%), by Power Output 2026 & 2034
Figure 42: Europe Air Cooled Fuel Cell Stack Revenue (billion), by Country 2026 & 2034
Figure 43: Europe Air Cooled Fuel Cell Stack Revenue Share (%), by Country 2026 & 2034
Figure 44: Middle East & Africa Air Cooled Fuel Cell Stack Revenue (billion), by Capacity 2026 & 2034
Figure 45: Middle East & Africa Air Cooled Fuel Cell Stack Revenue Share (%), by Capacity 2026 & 2034
Figure 46: Middle East & Africa Air Cooled Fuel Cell Stack Revenue (billion), by Fuel Cell Type 2026 & 2034
Figure 47: Middle East & Africa Air Cooled Fuel Cell Stack Revenue Share (%), by Fuel Cell Type 2026 & 2034
Figure 48: Middle East & Africa Air Cooled Fuel Cell Stack Revenue (billion), by Component 2026 & 2034
Figure 49: Middle East & Africa Air Cooled Fuel Cell Stack Revenue Share (%), by Component 2026 & 2034
Figure 50: Middle East & Africa Air Cooled Fuel Cell Stack Revenue (billion), by Application 2026 & 2034
Figure 51: Middle East & Africa Air Cooled Fuel Cell Stack Revenue Share (%), by Application 2026 & 2034
Figure 52: Middle East & Africa Air Cooled Fuel Cell Stack Revenue (billion), by End User 2026 & 2034
Figure 53: Middle East & Africa Air Cooled Fuel Cell Stack Revenue Share (%), by End User 2026 & 2034
Figure 54: Middle East & Africa Air Cooled Fuel Cell Stack Revenue (billion), by Power Output 2026 & 2034
Figure 55: Middle East & Africa Air Cooled Fuel Cell Stack Revenue Share (%), by Power Output 2026 & 2034
Figure 56: Middle East & Africa Air Cooled Fuel Cell Stack Revenue (billion), by Country 2026 & 2034
Figure 57: Middle East & Africa Air Cooled Fuel Cell Stack Revenue Share (%), by Country 2026 & 2034
Figure 58: Asia Pacific Air Cooled Fuel Cell Stack Revenue (billion), by Capacity 2026 & 2034
Figure 59: Asia Pacific Air Cooled Fuel Cell Stack Revenue Share (%), by Capacity 2026 & 2034
Figure 60: Asia Pacific Air Cooled Fuel Cell Stack Revenue (billion), by Fuel Cell Type 2026 & 2034
Figure 61: Asia Pacific Air Cooled Fuel Cell Stack Revenue Share (%), by Fuel Cell Type 2026 & 2034
Figure 62: Asia Pacific Air Cooled Fuel Cell Stack Revenue (billion), by Component 2026 & 2034
Figure 63: Asia Pacific Air Cooled Fuel Cell Stack Revenue Share (%), by Component 2026 & 2034
Figure 64: Asia Pacific Air Cooled Fuel Cell Stack Revenue (billion), by Application 2026 & 2034
Figure 65: Asia Pacific Air Cooled Fuel Cell Stack Revenue Share (%), by Application 2026 & 2034
Figure 66: Asia Pacific Air Cooled Fuel Cell Stack Revenue (billion), by End User 2026 & 2034
Figure 67: Asia Pacific Air Cooled Fuel Cell Stack Revenue Share (%), by End User 2026 & 2034
Figure 68: Asia Pacific Air Cooled Fuel Cell Stack Revenue (billion), by Power Output 2026 & 2034
Figure 69: Asia Pacific Air Cooled Fuel Cell Stack Revenue Share (%), by Power Output 2026 & 2034
Figure 70: Asia Pacific Air Cooled Fuel Cell Stack Revenue (billion), by Country 2026 & 2034
Figure 71: Asia Pacific Air Cooled Fuel Cell Stack Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Air Cooled Fuel Cell Stack Revenue billion Forecast, by Capacity 2020 & 2034
Table 2: Air Cooled Fuel Cell Stack Revenue billion Forecast, by Fuel Cell Type 2020 & 2034
Table 3: Air Cooled Fuel Cell Stack Revenue billion Forecast, by Component 2020 & 2034
Table 4: Air Cooled Fuel Cell Stack Revenue billion Forecast, by Application 2020 & 2034
Table 5: Air Cooled Fuel Cell Stack Revenue billion Forecast, by End User 2020 & 2034
Table 6: Air Cooled Fuel Cell Stack Revenue billion Forecast, by Power Output 2020 & 2034
Table 7: Air Cooled Fuel Cell Stack Revenue billion Forecast, by Region 2020 & 2034
Table 8: North America Air Cooled Fuel Cell Stack Revenue billion Forecast, by Capacity 2020 & 2034
Table 9: North America Air Cooled Fuel Cell Stack Revenue billion Forecast, by Fuel Cell Type 2020 & 2034
Table 10: North America Air Cooled Fuel Cell Stack Revenue billion Forecast, by Component 2020 & 2034
Table 11: North America Air Cooled Fuel Cell Stack Revenue billion Forecast, by Application 2020 & 2034
Table 12: North America Air Cooled Fuel Cell Stack Revenue billion Forecast, by End User 2020 & 2034
Table 13: North America Air Cooled Fuel Cell Stack Revenue billion Forecast, by Power Output 2020 & 2034
Table 14: North America Air Cooled Fuel Cell Stack Revenue billion Forecast, by Country 2020 & 2034
Table 15: United States Air Cooled Fuel Cell Stack Revenue (billion) Forecast, by Application 2020 & 2034
Table 16: Canada Air Cooled Fuel Cell Stack Revenue (billion) Forecast, by Application 2020 & 2034
Table 17: Mexico Air Cooled Fuel Cell Stack Revenue (billion) Forecast, by Application 2020 & 2034
Table 18: South America Air Cooled Fuel Cell Stack Revenue billion Forecast, by Capacity 2020 & 2034
Table 19: South America Air Cooled Fuel Cell Stack Revenue billion Forecast, by Fuel Cell Type 2020 & 2034
Table 20: South America Air Cooled Fuel Cell Stack Revenue billion Forecast, by Component 2020 & 2034
Table 21: South America Air Cooled Fuel Cell Stack Revenue billion Forecast, by Application 2020 & 2034
Table 22: South America Air Cooled Fuel Cell Stack Revenue billion Forecast, by End User 2020 & 2034
Table 23: South America Air Cooled Fuel Cell Stack Revenue billion Forecast, by Power Output 2020 & 2034
Table 24: South America Air Cooled Fuel Cell Stack Revenue billion Forecast, by Country 2020 & 2034
Table 25: Brazil Air Cooled Fuel Cell Stack Revenue (billion) Forecast, by Application 2020 & 2034
Table 26: Argentina Air Cooled Fuel Cell Stack Revenue (billion) Forecast, by Application 2020 & 2034
Table 27: Rest of South America Air Cooled Fuel Cell Stack Revenue (billion) Forecast, by Application 2020 & 2034
Table 28: Europe Air Cooled Fuel Cell Stack Revenue billion Forecast, by Capacity 2020 & 2034
Table 29: Europe Air Cooled Fuel Cell Stack Revenue billion Forecast, by Fuel Cell Type 2020 & 2034
Table 30: Europe Air Cooled Fuel Cell Stack Revenue billion Forecast, by Component 2020 & 2034
Table 31: Europe Air Cooled Fuel Cell Stack Revenue billion Forecast, by Application 2020 & 2034
Table 32: Europe Air Cooled Fuel Cell Stack Revenue billion Forecast, by End User 2020 & 2034
Table 33: Europe Air Cooled Fuel Cell Stack Revenue billion Forecast, by Power Output 2020 & 2034
Table 34: Europe Air Cooled Fuel Cell Stack Revenue billion Forecast, by Country 2020 & 2034
Table 35: United Kingdom Air Cooled Fuel Cell Stack Revenue (billion) Forecast, by Application 2020 & 2034
Table 36: Germany Air Cooled Fuel Cell Stack Revenue (billion) Forecast, by Application 2020 & 2034
Table 37: France Air Cooled Fuel Cell Stack Revenue (billion) Forecast, by Application 2020 & 2034
Table 38: Italy Air Cooled Fuel Cell Stack Revenue (billion) Forecast, by Application 2020 & 2034
Table 39: Spain Air Cooled Fuel Cell Stack Revenue (billion) Forecast, by Application 2020 & 2034
Table 40: Russia Air Cooled Fuel Cell Stack Revenue (billion) Forecast, by Application 2020 & 2034
Table 41: Benelux Air Cooled Fuel Cell Stack Revenue (billion) Forecast, by Application 2020 & 2034
Table 42: Nordics Air Cooled Fuel Cell Stack Revenue (billion) Forecast, by Application 2020 & 2034
Table 43: Rest of Europe Air Cooled Fuel Cell Stack Revenue (billion) Forecast, by Application 2020 & 2034
Table 44: Middle East & Africa Air Cooled Fuel Cell Stack Revenue billion Forecast, by Capacity 2020 & 2034
Table 45: Middle East & Africa Air Cooled Fuel Cell Stack Revenue billion Forecast, by Fuel Cell Type 2020 & 2034
Table 46: Middle East & Africa Air Cooled Fuel Cell Stack Revenue billion Forecast, by Component 2020 & 2034
Table 47: Middle East & Africa Air Cooled Fuel Cell Stack Revenue billion Forecast, by Application 2020 & 2034
Table 48: Middle East & Africa Air Cooled Fuel Cell Stack Revenue billion Forecast, by End User 2020 & 2034
Table 49: Middle East & Africa Air Cooled Fuel Cell Stack Revenue billion Forecast, by Power Output 2020 & 2034
Table 50: Middle East & Africa Air Cooled Fuel Cell Stack Revenue billion Forecast, by Country 2020 & 2034
Table 51: Turkey Air Cooled Fuel Cell Stack Revenue (billion) Forecast, by Application 2020 & 2034
Table 52: Israel Air Cooled Fuel Cell Stack Revenue (billion) Forecast, by Application 2020 & 2034
Table 53: GCC Air Cooled Fuel Cell Stack Revenue (billion) Forecast, by Application 2020 & 2034
Table 54: North Africa Air Cooled Fuel Cell Stack Revenue (billion) Forecast, by Application 2020 & 2034
Table 55: South Africa Air Cooled Fuel Cell Stack Revenue (billion) Forecast, by Application 2020 & 2034
Table 56: Rest of Middle East & Africa Air Cooled Fuel Cell Stack Revenue (billion) Forecast, by Application 2020 & 2034
Table 57: Asia Pacific Air Cooled Fuel Cell Stack Revenue billion Forecast, by Capacity 2020 & 2034
Table 58: Asia Pacific Air Cooled Fuel Cell Stack Revenue billion Forecast, by Fuel Cell Type 2020 & 2034
Table 59: Asia Pacific Air Cooled Fuel Cell Stack Revenue billion Forecast, by Component 2020 & 2034
Table 60: Asia Pacific Air Cooled Fuel Cell Stack Revenue billion Forecast, by Application 2020 & 2034
Table 61: Asia Pacific Air Cooled Fuel Cell Stack Revenue billion Forecast, by End User 2020 & 2034
Table 62: Asia Pacific Air Cooled Fuel Cell Stack Revenue billion Forecast, by Power Output 2020 & 2034
Table 63: Asia Pacific Air Cooled Fuel Cell Stack Revenue billion Forecast, by Country 2020 & 2034
Table 64: China Air Cooled Fuel Cell Stack Revenue (billion) Forecast, by Application 2020 & 2034
Table 65: India Air Cooled Fuel Cell Stack Revenue (billion) Forecast, by Application 2020 & 2034
Table 66: Japan Air Cooled Fuel Cell Stack Revenue (billion) Forecast, by Application 2020 & 2034
Table 67: South Korea Air Cooled Fuel Cell Stack Revenue (billion) Forecast, by Application 2020 & 2034
Table 68: ASEAN Air Cooled Fuel Cell Stack Revenue (billion) Forecast, by Application 2020 & 2034
Table 69: Oceania Air Cooled Fuel Cell Stack Revenue (billion) Forecast, by Application 2020 & 2034
Table 70: Rest of Asia Pacific Air Cooled Fuel Cell Stack Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Primary research constitutes 75% of our total research efforts, focusing on gathering first-hand insights directly from industry stakeholders. This involves a robust methodology of in-depth interviews (IDIs), extensive surveys, and targeted expert consultations. Our efforts are aimed at validating secondary data, understanding market dynamics, uncovering unmet needs, and assessing future market potential directly from those shaping the industry. Key opinion leaders and decision-makers across the value chain are targeted for their strategic perspectives and operational intelligence.
Our primary research engagement specifically includes interviews with the following key stakeholders:
Director of Fuel Cell Engineering
Product Line Manager, Portable Power Solutions
Head of Procurement, Advanced Materials
VP of Business Development, UAV & Robotics Division
Participants in our primary research are drawn from diverse company types integral to the air-cooled fuel cell stack ecosystem, including:
Air-Cooled Fuel Cell Stack Manufacturers
Key Component Suppliers (e.g., Membrane, Bipolar Plate, Gas Diffusion Layer (GDL), Cooling Fans & Air Management Systems)
System Integrators & Original Equipment Manufacturers (OEMs) for specific applications
Specialized Materials & Chemical Providers for catalysts and fuel components
Energy Storage & Power Solutions Providers deploying fuel cells in their offerings
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Director of Fuel Cell Engineering
30%
Product Line Manager, Portable Power Solutions
25%
Head of Procurement, Advanced Materials
25%
VP of Business Development, UAV & Robotics Division
20%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Air-Cooled Fuel Cell Stack Manufacturers
35%
Key Component Suppliers
25%
System Integrators & OEMs
20%
Specialized Materials & Chemical Providers
10%
Energy Storage & Power Solutions Providers
10%
Secondary Research & Industry Benchmarking
Secondary research accounts for 25% of our methodology, providing the foundational data, market landscapes, and validation points for primary insights. This phase involves a comprehensive review of publicly available information, investor presentations, annual reports, financial disclosures, and product specifications from leading market players. Our data sourcing leverages premium financial databases and authenticated public repositories.
Key secondary data sources utilized include:
Financial Databases: Bloomberg, Factiva, Hoovers, PitchBook, for company financials, investment trends, and strategic intelligence.
Governmental Publications: Official reports, policy documents, and statistical data from relevant national and international governmental bodies (.gov).
Industry Associations & Non-Profits: Research papers, whitepapers, and market reports published by credible industry associations and non-profit organizations (.org) dedicated to hydrogen and fuel cell technologies.
Relevant industry associations and regulatory bodies critical to this market include:
Hydrogen Council
Fuel Cell & Hydrogen Energy Association (FCHEA)
International Partnership for Hydrogen and Fuel Cells in the Economy (IPHE)
International Energy Agency (IEA)
Demand Modeling & Market Estimation
Our market estimation employs a rigorous combination of top-down and bottom-up methodologies, meticulously reconciled through multi-level data triangulation. The top-down approach involves analyzing macroeconomic factors, industry-wide growth projections, and overall technological adoption rates for fuel cell technologies, then disaggregating these down to the specific segments of air-cooled fuel cell stacks. The bottom-up approach aggregates granular data points collected from primary and secondary research, building the total market size from individual components and applications.
Specific metrics and variables utilized for the bottom-up market size calculation include:
Annual Unit Shipments (broken down by Capacity: Low, Medium, High Power, and by Application)
Average Selling Price (ASP) per kW/unit across different capacity ranges, fuel cell types, and end-user segments
Installed Power Output (in kW) for specific applications like portable power, backup systems, and material handling equipment
Market Penetration Rate within emerging application segments such as Unmanned Aerial Vehicles (UAVs) and robotics
Data triangulation ensures the robustness of our market figures by cross-referencing information from multiple independent sources, thereby minimizing potential biases and enhancing the reliability of our forecasts.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 88% for all market figures and forecasts presented in this report. This high level of accuracy is achieved through a multi-stage validation process that includes cross-validation with multiple primary and secondary sources, expert panel discussions, and the application of proprietary statistical modeling techniques.
Every report is dynamic and continuously updated to reflect the latest market developments, technological advancements, and shifts in regulatory landscapes. This ensures that the data provided is current and relevant up to the date of purchase, offering our clients the most timely and actionable market intelligence.
Frequently Asked Questions
1. What emerging technologies challenge the Air Cooled Fuel Cell Stack market?
The market faces competition from advanced battery technologies like lithium-ion, especially in portable and automotive segments. Additionally, other fuel cell types, such as Solid Oxide Fuel Cells (SOFC) and Phosphoric Acid Fuel Cells (PAFC), offer alternatives for specific stationary or high-power applications.
2. How are end-user preferences impacting Air Cooled Fuel Cell Stack adoption?
End-user preferences are shifting towards efficient, low-maintenance power solutions for commercial and industrial applications. Increased demand for backup power and material handling equipment, driven by operational continuity needs, fuels adoption of stacks with specific power outputs like 5 kW – 20 kW.
3. What recent developments shape the Air Cooled Fuel Cell Stack market?
Key companies like Ballard Power Systems and Plug Power Inc. are consistently investing in R&D to enhance efficiency and reduce costs. This includes advancements in Membrane Electrode Assembly (MEA) and Bipolar Plates to improve stack performance and expand application scope in sectors like UAVs and stationary power.
4. Which region leads the Air Cooled Fuel Cell Stack market and why?
Asia-Pacific, particularly China, Japan, and South Korea, is projected to dominate the market with an estimated 40% share. This leadership stems from substantial government investments in hydrogen infrastructure, robust automotive manufacturing, and high industrial adoption for material handling and stationary power applications.
5. How do regulations influence the Air Cooled Fuel Cell Stack industry?
Regulations promoting clean energy and reducing carbon emissions significantly impact market growth. Government incentives and mandates for zero-emission vehicles and stationary power generation encourage the adoption of fuel cell technologies globally, stimulating innovation and market entry.
6. What are the primary challenges facing the Air Cooled Fuel Cell Stack market?
High initial manufacturing costs and the limited hydrogen refueling infrastructure pose significant adoption challenges. Supply chain complexities for critical components like Gas Diffusion Layers (GDL) and specialized cooling systems also impact production scalability and market penetration, especially in emerging regions.